
If your 2026 planning assumes that business partnership dissolution starts with a filing, you’re already late. Most partnership failures begin earlier, inside operational friction, cross-border tax mismatches, and clauses that no one tested until the relationship broke.
For multinational businesses connected to Israel, the risk isn’t only that a partner exits. The deeper risk is that the exit triggers tax closure, freezes banking relationships, disrupts licenses, and exposes offshore assets to a fight over valuation and control. Conventional guides focus on paperwork. Serious commercial strategy starts earlier, when the partners still have room to shape their position, timing, and narrative.
Introduction to Dissolution Risks
A foreign investor and an Israeli operating partner may look stable on paper. Then one partner signals a withdrawal, the bank asks questions, and key suppliers stop extending credit because no one can explain who still has authority to bind the business.
That scenario isn’t rare. Nearly seven out of ten partnerships in the U.S. fail, significantly exceeding the global average and exposing a structural weakness in business relationships, according to this partnership failure discussion. For any group with Israeli operations, that statistic matters less as trivia and more as a warning. The relationship usually fails before the legal file opens.
Why standard dissolution planning misses the real danger
Most partners prepare for growth. Few prepare for controlled separation. As a result, they ignore the same disciplines that appear in any serious risk mitigation planning guide, namely trigger mapping, authority controls, document preservation, and communication sequencing.
Those omissions become expensive when the business spans jurisdictions. A partner’s departure can affect customer contracts, tax treatment, beneficial ownership disclosures, and internal approvals at once. If the agreement doesn’t define who decides what during the crisis window, every urgent decision becomes a dispute.
Practical rule: Business partnership dissolution is not a single event. It is an operational chain reaction that starts before formal notice.
What sophisticated clients need to protect early
Non-Israeli clients often focus first on court remedies. That instinct misses the commercial reality. In many disputes, the immediate objective isn’t dissolution itself. The objective is preserving liquidity, protecting signing authority, containing reputational fallout, and keeping the stronger side from rewriting facts through silence or delay.
A disciplined early response usually includes:
- Trigger review: Identify whether a notice, transfer, insolvency event, or governance breach has already activated dissolution rights.
- Control map: Confirm who currently controls bank accounts, tax filings, customer notices, and regulated licenses.
- Evidence freeze: Preserve shareholder or partnership communications, board materials, valuation inputs, and payment records.
- Cross-border scan: Check whether any assets, receivables, or entities sit outside Israel and need separate treatment.
That is where business partnership dissolution becomes strategic analysis, not clerical cleanup.
Establishing Legal Foundations
The legal starting point is simple, but many partnerships still miss it. A partnership is legally dissolved when events like partner withdrawal or the sale of 50% of interests within 12 months occur, triggering a technical termination under law, as summarized in this legal overview of dissolution and termination.
For Israeli and multinational clients, the practical lesson is sharper. The dispute may feel relational, but the law often treats it as a defined status change with immediate effects on authority, tax timing, and winding-up duties.
Dissolution is not the same as termination
Dissolution ends the partnership relationship as it existed. It does not instantly erase the entity. The partnership can continue to exist legally while debts are settled, operations stop, and assets are distributed.
That distinction matters when one side assumes it can walk away and leave administration behind. It can’t. Until the winding-up process closes correctly, liabilities and representation issues may continue.
Triggers that require close drafting
Several events commonly trigger dissolution. They include resignation, withdrawal, expulsion, bankruptcy, illegality, death, insolvency, mutual agreement, serious medical misfortune, and fiduciary breach. In Israel-focused practice, one additional point matters a great deal. If the partnership agreement says nothing to the contrary, a partnership may dissolve automatically when one partner notifies the others of an intent to leave, as noted in this guide to establishing business entities in Israel.
That default rule surprises foreign founders. They often assume that a notice of departure merely starts negotiations. In many structures, it may do more than that.
A weak partnership agreement doesn’t create flexibility. It transfers control to default rules.
Clauses that reduce accidental outcomes
Israeli commercial drafting should address more than ownership percentages. It should decide whether a departure causes automatic dissolution, whether buyout rights suspend that result, who controls the valuation date, and how interim authority works.
A non-compete clause also needs careful treatment, especially if a departing partner can exploit clients, staff, or know-how while the valuation dispute remains open. For a practical business perspective on restrictive covenants, this Paradigm International non-compete guide is useful background reading when aligning exit restraints with commercial reality.
Drafting should also state any intended limitation on a partner’s right to seek court dissolution with precision. Under Israeli law, vague wording is not enough. The limitation must be explicit, as discussed in this Israeli case law update on dissolution rights.
Preparing for Strategic Exit
By the time lawyers receive a panicked message saying the partnership has collapsed, the collapse usually began much earlier. Research identifies a five-phase dissolution model, stresses, growing dissatisfactions, deterioration, pre-dissolution, and termination, that explains why partnerships crumble long before legal action starts, as set out in this research paper on partnership dissolution phases.
That model is useful because it changes what the client should inspect first. The immediate legal issue may be authority or notice. The underlying commercial issue is often long-term trust failure.
The signs that matter before anyone files anything
In the stresses phase, the partnership still functions, but friction becomes repetitive. In growing dissatisfactions, complaints gain structure. In deterioration, the sides stop sharing assumptions. That is usually where the most expensive mistakes happen, because the partners remain legally tied while acting like opponents.
The pre-dissolution phase often includes private advisor outreach, draft notices, side conversations with banks, and selective information sharing. Termination arrives later, after positions harden.
A practical due diligence screen
Before formal steps, counsel should test the partnership on four tracks at once:
-
Document authority
Review the partnership agreement, amendments, powers of attorney, signature matrices, and side letters. Many disputes turn on a side document, not the main agreement. -
Financial integrity
Reconcile management accounts, tax filings, shareholder loans, related-party payments, and any unexplained withdrawals. If one side doesn’t trust the books, every later valuation will become a fight. -
Operational dependence
Identify which partner controls customer relationships, platforms, banking access, compliance records, and staff loyalty. A paper majority means little if the other side controls daily execution. -
Stakeholder exposure
Map lenders, landlords, regulators, key customers, and international affiliates. Each one may need a different communication sequence.
The best time to structure an exit is before the partners agree that they need one.
What works in practice
Periodic health checks are useful when they are specific and enforceable. The stronger approach is not vague relationship maintenance. It is scheduled review of role clarity, communication quality, financial transparency, and strategic alignment, followed by written action items if confidence drops. In more structured matters, firms such as RNC Group use phased analysis to identify influential factors before the dispute turns into a public collapse.
What does not work is sentimental delay. If the deterioration phase has begun, waiting for emotions to improve often gives the better-positioned partner time to move assets, influence staff, or frame the story externally.
Negotiation and Exit Strategies
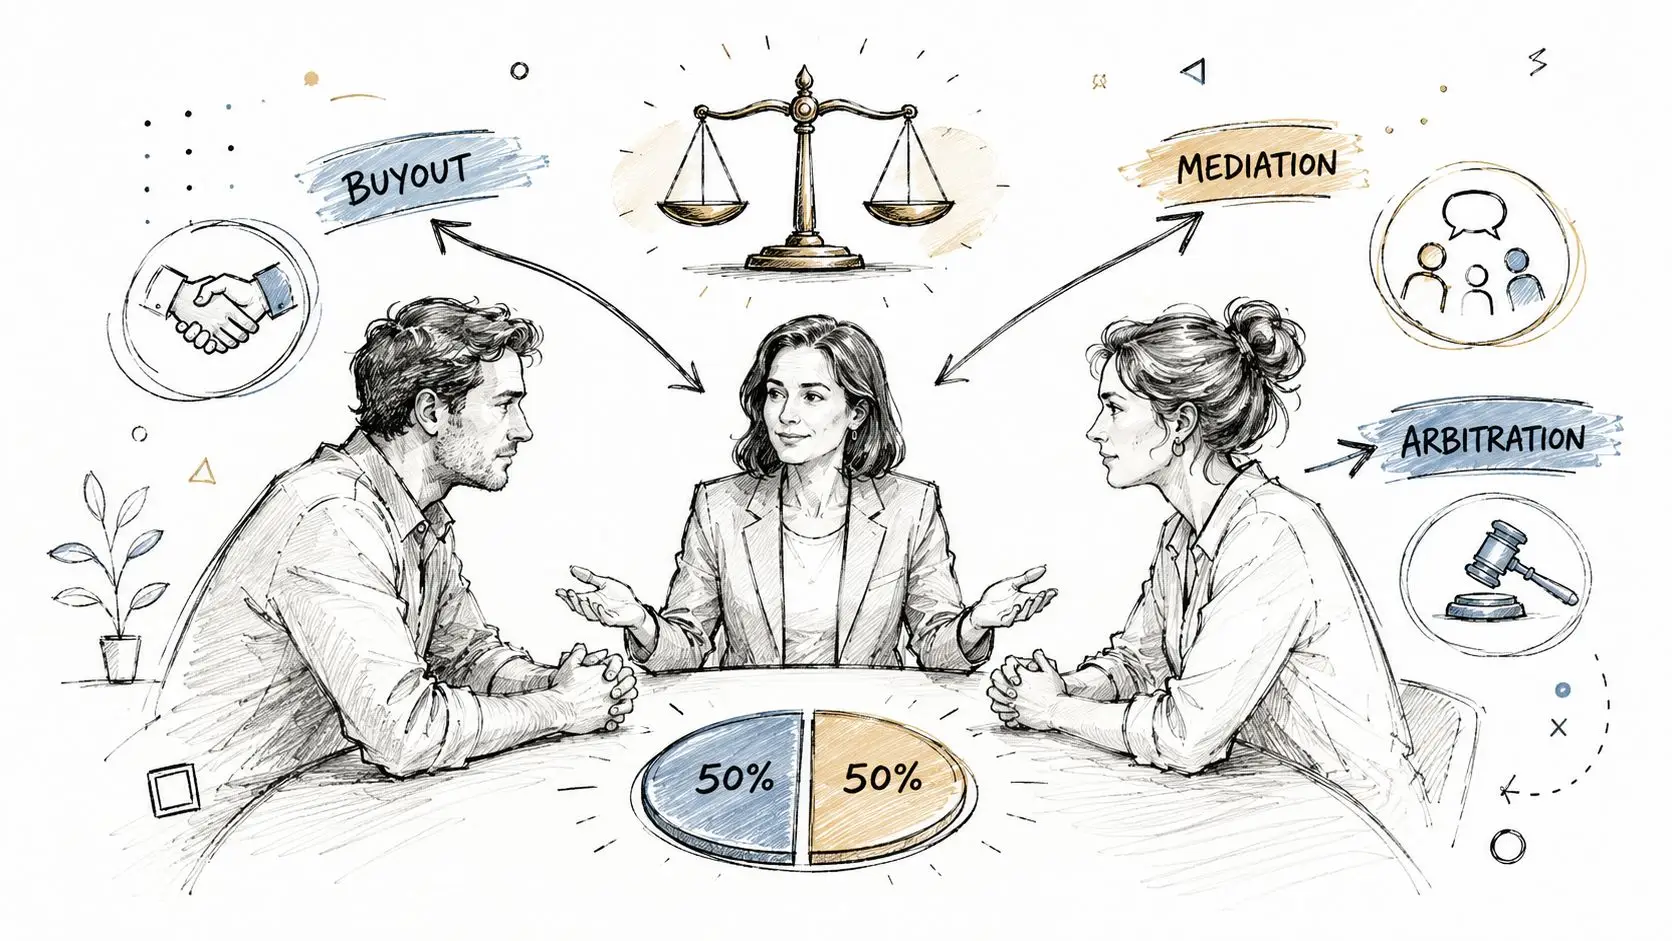
When control is evenly split, delay becomes a weapon. Structured buyouts with professional appraisals and mediation serve as proven mechanisms to resolve deadlocks, recommended when partner control is evenly split, according to this analysis of why business partnerships fail and how to succeed.
That point deserves emphasis in Israeli commercial disputes involving foreign parties. A 50-50 structure often looks balanced during formation and unworkable during exit. No side can force ordinary decisions without creating power struggles over operations, salaries, or information.
Comparing the main exit routes
The right route depends on urgency, evidence quality, and the level of trust still available.
| Route | When it fits | Main advantage | Main weakness |
|---|---|---|---|
| Negotiated buyout | One side wants continuity | Preserves business value | Fails if valuation trust is low |
| Mediation | Communication still possible | Faster and less adversarial | Needs both sides to engage |
| Arbitration | Technical dispute with contract support | Greater procedural control | Can still become expensive |
| Litigation | Fraud, concealment, or urgent coercive relief | Court orders can compel action | Public exposure and slower momentum |
Buyout terms that reduce later warfare
A buyout should not stop at price. It must also allocate tax burdens, define the valuation date, assign responsibility for pending claims, and control customer communication. If the price is clear but indemnities are vague, the dispute changes shape.
Useful points to settle early include:
- Valuation method: State whether adjusted book value, discounted cash flow, or capitalization of earnings applies.
- Payment structure: Allow staged payments if liquidity is tight, but secure them properly.
- Conduct restrictions: Limit client poaching, staff solicitation, and unilateral public statements.
- Records access: Keep audit rights alive for a defined post-closing period.
Why mediation often outperforms early court action
Mediation works best when the partners still need a practical commercial answer. The mediator can test assumptions, separate emotional grievance from financial reality, and narrow the issues before reputational damage spreads.
Litigation has its place. If one partner is hiding records, draining funds, or breaching fiduciary duties, court relief may be unavoidable. Still, many multinational clients underestimate how quickly public proceedings affect lending, counterparties, and market perception in Israel.
Decision point: If the partnership still has operating value, protect that value before arguing about blame.
Valuation and Asset Division Methodology
Most failed dissolutions don’t fail because the partners lacked a grievance. They fail because they handled valuation casually, mixed personal and business assets, or filed closure documents too late. A disciplined process is available. A four-stage framework spans negotiation (1–3 months), valuation (2–4 weeks), distribution (4–8 weeks), and legal closure (2–4 weeks), with best-case resolutions in 4–6 weeks, according to this dissolution process framework.
Dissolution framework overview
| Stage | Duration | Key Actions | Pitfalls |
|---|---|---|---|
| Negotiation | 1–3 months | Draft dissolution terms, allocate responsibilities, set dispute path | Valuation fights, unclear authority, no counsel input |
| Valuation | 2–4 weeks | Use neutral appraisal, identify debts, confirm equity positions | Informal pricing, incomplete records, disputed assumptions |
| Distribution | 4–8 weeks | Transfer assets, liquidate where needed, settle payments | Delays in title transfer, payment slippage, missing consents |
| Legal closure | 2–4 weeks | File closure papers, cancel permits, close accounts | Missed deadlines, inaccurate filings, unfinished notifications |
How to approach valuation credibly
Neutral valuation reduces noise. It does not remove conflict, but it anchors the discussion in a method both sides can test. For business owners who want a practical overview before engaging appraisers, this guide to small business valuation offers a useful primer on common approaches.
The valuation file should include more than revenue history. It should also examine contingent liabilities, shareholder loans, unpaid tax exposure, dependency on a departing partner, and whether goodwill belongs to the entity or to individual relationships.
Informal valuations feel efficient at the start and become evidence problems later.
Asset division under Israeli liquidation logic
For Israeli partnerships, assets must first pay creditors. Only the remaining funds should then move to the partners according to their relative ownership shares, as outlined in this Israeli guide on partnership liquidation.
That sequence sounds obvious, yet partners often reverse it in practice. They argue about residual value before they have settled vendor claims, tax obligations, and account reconciliation. That approach usually invites personal exposure and later clawback disputes.
Managing Contracts and Cross Border Disputes
Cross-border business partnership dissolution usually fails at the seams. One jurisdiction treats the exit as a buyout. Another treats it as a wind-down. The contract says one thing, the tax advisor says another, and the bank refuses instructions until beneficial ownership becomes clear.
The scale of that problem is no longer anecdotal. 35% of international partnership dissolutions were stalled by conflicting tax treatments of buyout versus wind-down structures across borders in 2024-2025, according to this cross-border dissolution analysis.
Contract clauses that deserve immediate review
Not every dispute belongs in court. First, counsel should inspect the documents that shape commercial continuity:
- Termination clauses: Do they end related service, licensing, or supply arrangements automatically, or only after notice?
- Change-of-control language: Could a buyout trigger consent rights in financing or distribution agreements?
- Dispute resolution terms: Do they require arbitration, expert determination, or a specific forum?
- Governing law split: Do the operating documents and the key commercial contracts point to different legal systems?
That review often shows why one exit structure preserves value while another destroys it. A clean local buyout may create foreign tax friction. A formal wind-down may solve tax characterization but damage customer continuity.
Litigation versus ADR in cross-border matters
Multinational clients usually weigh three factors: speed, control, and enforceability.
Litigation offers stronger coercive tools. It can help when a partner withholds records, misuses authority, or threatens dissipation of assets. However, it increases publicity risk and may complicate settlement posture across multiple jurisdictions.
Mediation and arbitration offer more confidentiality and procedural flexibility. They often work better when the dispute is technical, document-heavy, and focused on price, authority, or post-exit restraints. They work less well when one side needs immediate injunctive relief.
Israeli administrative steps that foreign clients often miss
Once liquidation moves from strategy to execution, filing mechanics matter. The Israeli Registrar of Partnerships accepts liquidation documents through three official channels: the online portal, mail to the Regulations Authority in Jerusalem, or in-person submission on Sundays and Wednesdays between 8:30 and 12:30, with prior appointment booking strongly recommended, according to the Israeli government partnership liquidation service.
Foreign clients also need to plan for bank behavior. Even where the formal legal route is available, banks may slow account activity if signatory authority is disputed, documentation is incomplete, or the ownership story changes mid-process. In practice, that means the legal team and the finance team must coordinate notices, resolutions, and supporting records before approaching the bank.
Isolating international tax exposure while preserving liquidity
The central cross-border trade-off is this. A structure that minimizes tax friction abroad may trap cash needed in Israel. A structure that preserves Israeli liquidity may trigger adverse treatment elsewhere.
A workable strategy often includes:
- Separating domestic operations: Ring-fence the Israeli revenue stream and customer contracts where possible.
- Identifying offshore bottlenecks: Track which partner controls non-Israeli accounts, IP holding entities, or foreign receivables.
- Sequencing the exit: Decide whether the commercial separation should happen before the formal legal separation, or the reverse.
- Allocating tax responsibility clearly: State who bears legacy liabilities, audit cooperation duties, and filing obligations by jurisdiction.
Clients often want one universal settlement document. Cross-border disputes usually need a coordinated document set instead, with one core commercial agreement and jurisdiction-specific implementation pieces.
Conclusion with Checklist and Media Tactics
A sound business partnership dissolution plan does two things at once. It closes legal exposure and controls the story that customers, lenders, employees, and counterparties will hear during the exit.
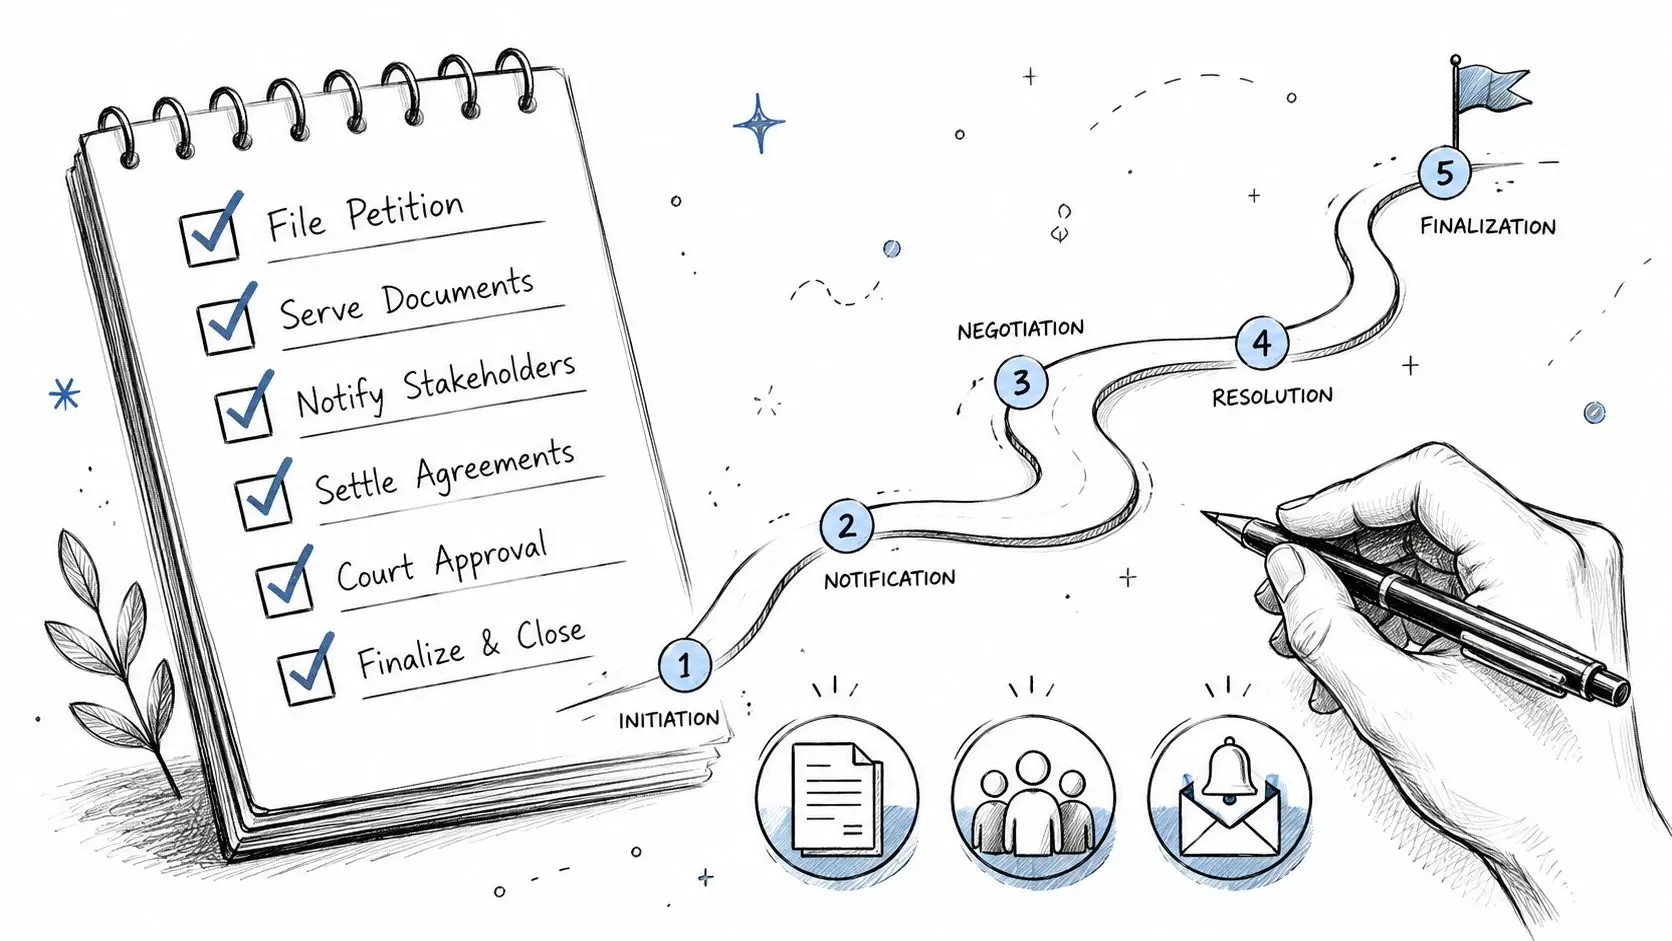
Closing checklist for a controlled exit
- Confirm the trigger: Identify whether notice, transfer, insolvency, or breach has already activated dissolution rights.
- Lock the record: Preserve communications, accounting files, approvals, and access logs before narratives diverge.
- Choose the route: Decide whether buyout, mediation, arbitration, or litigation best protects value.
- Fix the valuation date: Prevent tactical manipulation through later withdrawals, bookings, or side payments.
- Pay in the right order: Settle creditors before distributing residual value.
- File and notify correctly: Complete registrar, tax, license, banking, and counterparty notices in a coordinated sequence.
Media and reputation control
Commercial fallout often comes from messaging failures, not the legal result. One partner speaks to staff too early. Another reassures a customer with facts that later change. A supplier hears rumors before receiving formal notice.
The safer approach is disciplined and brief. Prepare one internal message, one external customer line, and one lender-facing explanation. Keep all statements consistent with the legal documents and avoid assigning blame while negotiations remain active.
A controlled message preserves leverage. An emotional message destroys it.
The recommended strategic path is to treat dissolution as a phased commercial operation, not merely a legal breakup. That approach reduces avoidable conflict, protects liquidity, and gives multinational clients a better chance of exiting Israeli-connected partnerships without turning a business separation into a broader crisis.
Avoid costly mistakes and contact RNC Group now through the firm’s contact page for a personalized review of your partnership exit, cross-border exposure, and filing strategy.
This article provides general information only and does not constitute legal advice, tax advice, or a substitute for case-specific counsel. Reliance on any part of this article without a full review of the relevant agreements, facts, jurisdictions, and regulatory posture may create legal and commercial risk.