
A stock purchase agreement can transfer ownership in a minute, yet allocate financial risk for years. One SEC-filed agreement fixed closing at 10:00 a.m. Pacific Time, while another made closing effective at 12:01 a.m. Pacific Time on the closing date. Those details matter because ownership, economic entitlement, conditions precedent, and liability may begin at different moments. SEC-filed stock purchase agreement
Foreign buyers entering an Israeli transaction should therefore treat the agreement as a controlled risk system. The document must coordinate price, tax, employment, title, approvals, disclosure, remedies, and dispute procedure. A template copied from another jurisdiction rarely provides that coordination.
Why a Stock Purchase Agreement Is a Risk-Allocation Engine, Not a Transfer Form
The most dangerous SPA mistake starts with the wrong premise. The buyer isn’t merely purchasing shares. The buyer is purchasing a corporate history, including obligations that may emerge after signing and after closing.
A stock purchase agreement sets the price, determines when economic ownership begins, and decides who pays when the target’s condition differs from the parties’ assumptions. It also establishes the claim window, recovery source, notice process, and governing forum. Those functions turn the agreement into a post-closing liability ledger.
The risk ledger behind the headline price
A buyer may negotiate an attractive headline price and still accept excessive exposure through weak adjustments, a narrow indemnity, or an early escrow release. Conversely, a seller may obtain a strong cash price but retain an open-ended liability burden through uncapped warranties.
Practical Law’s 2024 review compared 23 private M&A purchase agreements signed in 2023 with 74 signed in 2022. The review reported that 45% of the 2023 sample used all-cash consideration, while 26% included escrow or holdback protection. Practical Law market review
Those figures don’t dictate a deal position. They show that consideration and recovery mechanics vary, even within standardized documents. The negotiating question is practical: which party should bear each risk, and what mechanism can fund recovery?
A digital ownership structure can add another layer. Clients considering tokenized equity should separately review the Blocsys guide to tokenization, then reconcile any digital ledger with the company’s legal share register and transfer documents.
Signing is not the risk endpoint
At signing, representations may be accurate. At closing, a permit may have expired, a tax position may have changed, or an employee claim may have surfaced. The bring-down condition and interim covenants must address that timing gap.
Indemnity usually runs from selling shareholders to the buyer, rather than from the acquired company. After closing, claims against the target often provide limited practical value because the buyer already owns that company. Commentary on M&A indemnification
Practical rule: Negotiate the indemnity schedule with the same care as the purchase price.
The agreement should connect representations, disclosure schedules, specific indemnities, escrow, baskets, caps, survival periods, and claim procedures. Each clause must support the same risk allocation. If one clause expands liability while another removes the remedy, the buyer may discover the conflict only after loss occurs.
Stock Purchase Agreement Versus Asset Purchase Agreement
The choice between an SPA and an asset purchase agreement isn’t procedural. It prices the difference between continuity and selection.
An SPA transfers the shares, so the target company remains intact. Its contracts, permits, employees, assets, liabilities, records, and litigation history stay inside the entity. That structure often supports operational continuity, but it also exposes the buyer to hidden liabilities.
An asset purchase agreement identifies the assets and liabilities that move. The buyer can select equipment, intellectual property, inventory, or contracts, while excluding other items. However, assignment requirements, employee arrangements, tax treatment, and liabilities that transfer by law can make the process heavier.
| Dimension | Stock Purchase Agreement | Asset Purchase Agreement |
|---|---|---|
| Tax exposure | The buyer acquires the target’s existing tax history and must examine Israeli residence, withholding, and prior filings. | The parties allocate assets and liabilities directly, but tax consequences may arise at company and shareholder levels. |
| Liability transfer | The target retains known and unknown liabilities, including potential tax, employment, product, and litigation exposure. | The buyer can define assumed liabilities, yet mandatory successor liabilities may still apply. |
| Contract continuity | Contracts usually remain with the target, although change-of-control clauses may require consent. | The buyer may need assignments and third-party approvals for contracts, leases, and licenses. |
| Closing mechanics | The parties address share authority, shareholder approvals, pre-emption rights, registers, and corporate records. | The parties convey assets, transfer permits where possible, allocate employees, and document each excluded liability. |
The trade-off foreign buyers should price
An SPA usually offers cleaner operational continuity. The buyer avoids transferring every contract individually and preserves the target’s corporate relationships. That convenience has a price, namely the need for deeper diligence and stronger post-closing protection.
An APA offers sharper asset selection. The buyer may avoid unwanted liabilities and acquire only the business components that create value. The buyer then carries a heavier implementation burden, because contracts, employees, licenses, data, and intellectual property may require separate treatment.
Israeli counsel should also examine company records, transfer restrictions, tax withholding, sector approvals, and any obligations attached to public support or Investment Center undertakings. The correct structure depends on risk tolerance, tax advice, continuity requirements, and the seller’s ability to provide credible security.
The faster closing structure isn’t always the cheaper structure. Buyers should price inherited risk and implementation risk separately.
Anatomy of a Stock Purchase Agreement Clause by Clause
A strong SPA turns commercial decisions into enforceable sequences. Each clause answers a distinct question about timing, proof, allocation, or recovery.
Price and adjustment mechanics
The purchase-price clause must identify the economic model. A locked-box approach fixes value by reference to historic accounts and restricts value leakage after the locked-box date. Completion accounts reprice the transaction using actual cash, debt, and working capital at closing.
A common completion-accounts process uses a seller-prepared estimate before closing, followed by a buyer-reviewed statement after closing. The parties then make a true-up payment if actual metrics differ from the agreed target. Purchase-price adjustment guidance
The drafting decision concerns accounting principles, hierarchy, dispute experts, permitted leakage, and payment security. A vague working-capital definition creates a valuation dispute after closing.
Conditions and closing
Conditions precedent may include regulatory approvals, third-party consents, required corporate approvals, and the absence of a defined material adverse change. Israeli-specific conditions may include tax clearances, share-register steps, foreign investment considerations, or compliance with Investment Center undertakings.
The agreement should state whether each representation must be accurate at signing, closing, or both. It should also identify which conditions the buyer may waive and which conditions protect public policy or third-party rights.
Representations and warranties
Representations cover the facts supporting the deal. Typical schedules address corporate authority, capitalization, financial statements, tax, employment, intellectual property, contracts, permits, insurance, litigation, data, and compliance.
The buyer should connect each material diligence issue to a disclosure schedule or a specific indemnity. The seller should avoid broad statements that exceed available knowledge and records. Both parties should define knowledge, materiality, and disclosure precisely.
Indemnity and recovery
Indemnity provisions establish scope, caps, baskets, de minimis thresholds, exclusions, mitigation, claim notice, and exclusive-remedy rules. Fundamental, tax, fraud, and title matters often require separate treatment from ordinary business warranties.
General representations commonly survive 6 to 24 months, according to M&A commentary. Fundamental representations commonly receive 3 to 6 years, or sometimes indefinite survival. Representation survival analysis Market overview of warranty survival
Escrow and covenants
Escrow converts a contractual promise into available recovery. One SEC-filed agreement required a $3,000,000 indemnity escrow, while another defined an indemnity escrow of $712,500. SEC-filed escrow example
Restrictive covenants address non-compete, non-solicit, confidentiality, and founder conduct. Post-closing covenants should cover cooperation, further assurances, records, tax filings, transition support, and access to information.
Sample Clause Language and Drafting Tips
Sample language helps expose hidden choices. Counsel should adapt each provision to the transaction’s governing law, tax structure, seller group, and disclosure record.
| Clause Type | Recommended Language | Common Drafting Error |
|---|---|---|
| Price adjustment | “The Final Purchase Price shall equal the Estimated Purchase Price, adjusted dollar-for-dollar for the variance between Closing Working Capital and Target Working Capital.” | Leaving accounting principles, review rights, or expert determination unclear. |
| Earn-out | “The Earn-Out Amount shall equal the agreed revenue and gross-margin formula, calculated from defined financial statements and reduced only by expressly permitted deductions.” | Using undefined revenue, margin, customer, or accounting terms. |
| Bring-down | “The Seller’s representations identified as Closing Representations shall be true as of Closing, except for changes expressly disclosed by section reference.” | Treating every representation as repeated automatically, or using an undefined materiality standard. |
| Indemnity | “The Sellers shall indemnify the Buyer for covered losses after the applicable de minimis threshold and basket, subject to the agreed cap and survival period.” | Omitting joint-and-several liability when minority sellers may lack recovery capacity. |
| Escrow release | “The Escrow Agent shall release undisputed funds on the scheduled release date, while retaining amounts subject to properly notified claims until resolution.” | Releasing the entire fund before disputed claims receive a defined process. |
Drafting the price formula
An earn-out formula must define revenue recognition, gross-margin calculation, accounting consistency, permitted business changes, and access to records. Otherwise, the buyer may control the metric while the seller carries the performance risk.
A completion statement clause should identify who prepares the statement, which accounting rules prevail, and how an independent expert resolves disagreement. The agreement should also specify whether that expert decides accounting questions only.
Controlling disclosure and bring-down
A disclosure should identify the affected representation by section reference. General disclosure language rarely gives the buyer enough notice and rarely gives the seller reliable protection.
The bring-down clause should distinguish signing-date truth from closing-date truth. It should also explain whether materiality qualifiers apply to the condition, the representation, or both.
Making indemnity collectible
The parties should coordinate the cap, basket, de minimis threshold, survival period, escrow, set-off rights, and seller liability allocation. A cap without a solvent obligor or security mechanism may provide only theoretical protection.
The escrow agreement must address release dates, interest, deductions, joint instructions, disputed claims, and the agent’s authority. A seller note may also support set-off, if the transaction uses deferred consideration.
Due Diligence and Tax Considerations for Cross-Border Deals
Diligence should produce drafting instructions, not a disconnected report. Every material finding should enter a defined risk bucket before execution.
A missing license may become a closing condition. An underfunded pension obligation may require a specific indemnity. Unfiled Israeli returns may require a tax indemnity, a price adjustment, or a condition requiring filings and clearance.
Turning findings into deal decisions
Use four practical categories:
- Deal-killer: The buyer cannot accept the risk, even with price protection.
- Price adjustment: The parties can quantify the exposure and reflect it in value.
- Specific indemnity: The exposure remains uncertain, so the seller funds the defined risk.
- General warranty: The issue fits ordinary business risk and falls within negotiated caps and survival.
This triage prevents the SPA from becoming a warehouse for unresolved diligence. It also forces the parties to distinguish uncertainty from unacceptable risk.
Israeli tax and cross-border hooks
Foreign buyers should examine Israeli withholding on consideration paid to non-resident sellers. The payment process should identify certificates, exemptions, clearance requirements, gross-up exposure, and responsibility for delay.
The Israeli Tax Ordinance may also make section 104H and 104H1 tax rulings relevant to qualifying reorganizations or transfers. Tax advisers should confirm the statutory route and ruling conditions before the parties fix the transaction steps.
US-linked structures require separate analysis of FIRPTA-style concerns where relevant. EU-connected arrangements may raise DAC6 reporting triggers for cross-border structures. Treaty eligibility also requires factual verification, including residence, beneficial ownership, and procedural compliance.
Tax language must match the payment mechanics. A tax indemnity cannot repair a closing process that fails to obtain the required clearance.
The SPA should allocate responsibility for filings, cooperation, records, audits, refund claims, and tax authority correspondence. Israeli and home-jurisdiction advisers should reconcile those provisions before signing.
Negotiation Tactics That Hold Up After Signing
A party that fights every clause usually spends negotiating capital badly. The stronger approach identifies where residual risk will concentrate after closing, then trades lower-impact points for durable protection.
The buyer should usually focus on indemnity scope, knowledge qualifiers, survival periods, disclosure standards, and recovery security. The seller should focus on certainty of payment, liability caps, claim procedures, exclusive remedies, and finality.
Sequence the negotiation
Start with a short risk map. Identify the few exposures that could materially change the investment case, such as tax, employment, intellectual property ownership, regulatory authorization, or founder conduct.
Then make selective concessions. Boilerplate representations, routine notice mechanics, and low-impact covenants may offer useful trading value. The buyer can redeploy that value into a specific indemnity, a longer relevant survival period, or a better escrow release condition.
Escrow works best when it matches the risk. A broad fund may frustrate the seller and still fail to address a specialized tax exposure. A targeted holdback with clear release milestones often produces better alignment.
Israel-related execution tactics
Foreign counsel should obtain an Israeli-law review before the redline hardens. The Israeli auditor should also align with the seller’s tax representations, because accounting treatment and legal wording often diverge.
Founders who remain involved create a conduct risk that price alone cannot solve. Restrictive covenants, reporting duties, access controls, and defined transition obligations usually address that risk more directly than an inflated purchase-price holdback.
Concede language that doesn’t change the outcome. Contest language that controls recovery after the relationship deteriorates.
Common Pitfalls and How Israeli Cross-Border Deals Break Them
Standard SPA language often fails because it assumes the target’s jurisdiction, records, tax system, and corporate practice resemble the drafting lawyer’s home market. Israeli transactions can expose those assumptions quickly.
A short survival period may expire before a tax audit, employment claim, or warranty issue becomes actionable. A low cap may exclude fundamental, tax, fraud, or Israeli Securities Law exposure. An escrow may release before the parties resolve a properly notified claim.
Align remedies with Israeli realities
The agreement should tie survival to the relevant limitation period where appropriate. Tax and fundamental warranties may need separate periods from ordinary business warranties.
The governing-law clause should state what it governs. Contractual obligations may follow Delaware law, while title, corporate authority, transfer approvals, fiduciary duties, and regulatory matters may depend on Israeli mandatory law. One SEC-filed agreement expressly applied Delaware law to the agreement and related tort and inducement claims, illustrating the importance of drafting the scope clearly. SEC governing-law example
The forum clause must match the enforcement plan. A court, arbitration tribunal, or foreign judgment may offer different routes for urgent relief and asset recovery.
Check closing mechanics before signing
Israeli company records, tax withholding, share-register updates, foreign currency payments, beneficial ownership, sanctions, antitrust filings, and sector approvals can delay completion. The parties should assign each deliverable to a named person and define the consequence of failure.
Defined terms must also work together. Knowledge qualifiers, materiality scrapes, disclosure schedules, baskets, caps, and exclusive-remedy language should produce one coherent remedy system.
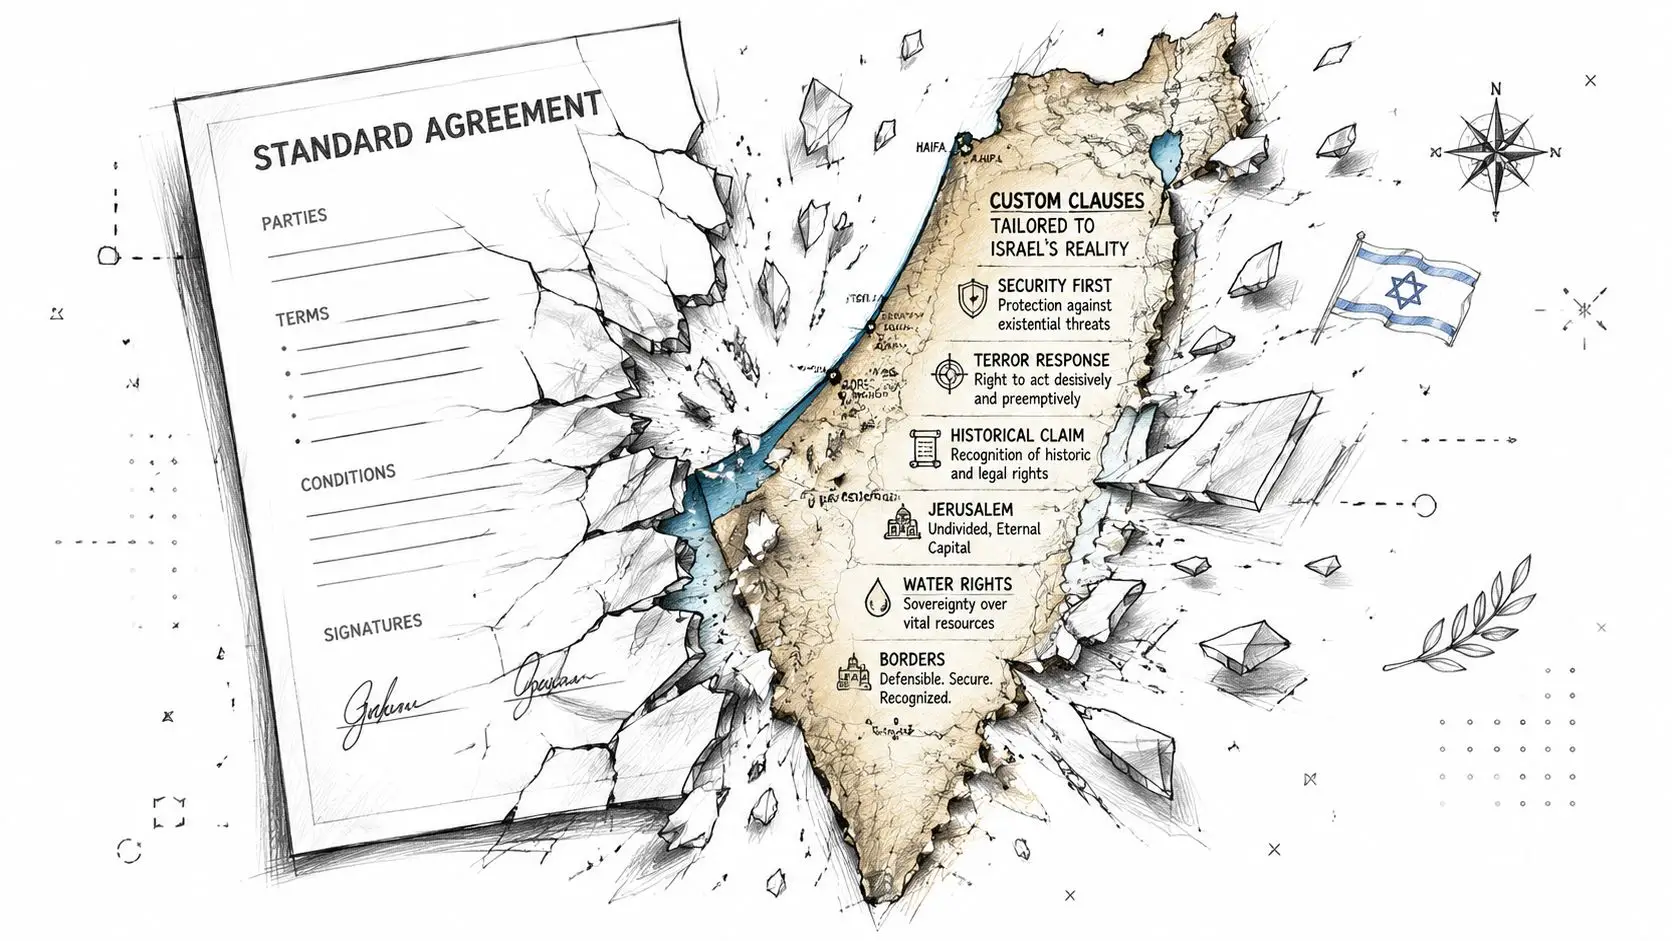
Copied representations may misstate Israeli employment duties, tax positions, corporate authority, or mandatory rules. A local-law and tax review should validate every assumption before execution.
Post-Closing Dispute Prevention and Management Strategy
The best dispute protocol starts before closing. The parties should sign the closing statement, approve net-debt and working-capital schedules, identify covenant owners, and preserve the evidence supporting each calculation.
A claims calendar should track warranty, tax, escrow, earn-out, and post-closing covenant periods. The buyer should maintain one notice file, while senior management should set internal escalation thresholds before a disagreement becomes a relationship crisis.
Build the recovery process
Escrow instructions should state the release timetable, permitted deductions, joint directions, interest treatment, and the procedure for disputed claims. The agreement should also identify whether the agent can act on a unilateral claim notice or requires instructions from both sides.
Cross-border parties should maintain a translation-controlled schedule. They should preserve emails, board approvals, auditor workpapers, tax filings, payment records, and closing certificates in an accessible repository.
Israeli disputes may benefit from early mediation or neutral evaluation, especially for working-capital adjustments and technical valuation questions. Urgent injunctive relief and company-law remedies may still require immediate court action.
Use a disciplined claim sequence
Before filing, verify the notice deadline, escrow availability, governing law, forum, arbitration rules, enforcement route, and applicable limitation period. Then test whether the claimed loss fits the negotiated definition and whether the buyer preserved mitigation evidence.
A practical sequence looks like this:
- Identify the clause: Match the fact to the representation, covenant, indemnity, or adjustment mechanism.
- Preserve proof: Secure financial records, correspondence, approvals, and expert analysis.
- Give compliant notice: Follow the contractual channel and include the required detail.
- Escalate proportionately: Use management discussion, mediation, or expert determination where suitable.
- Protect urgent rights: Seek interim relief promptly when delay may impair recovery.
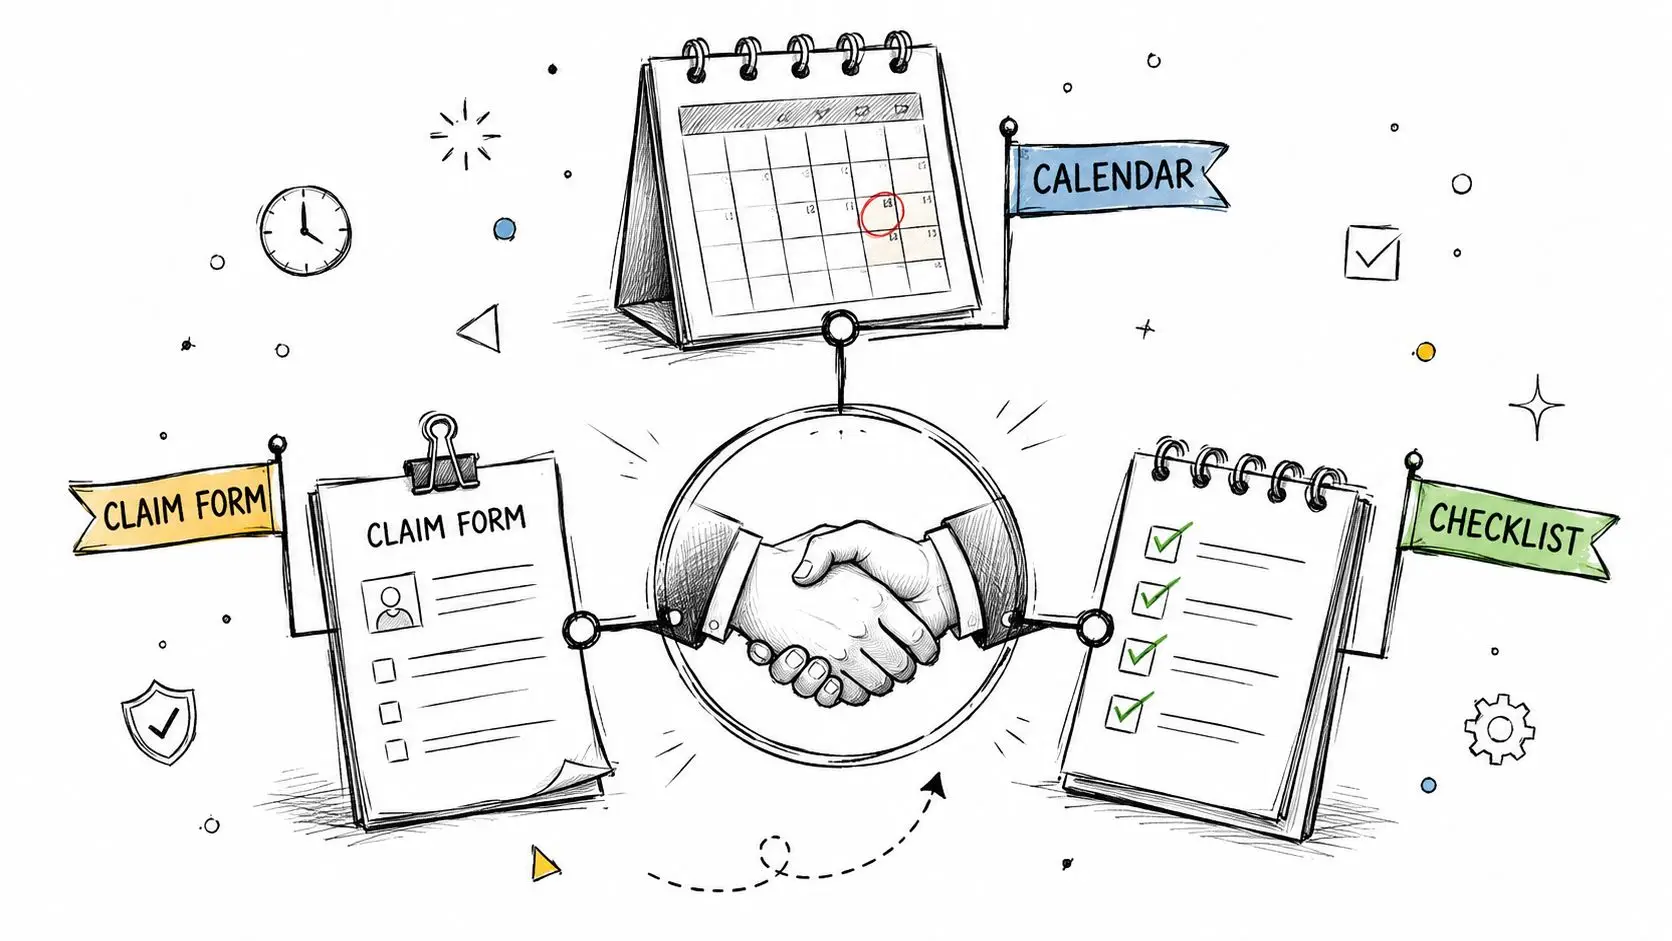
The recommended strategic path is to coordinate Israeli counsel, home-jurisdiction counsel, tax advisers, and dispute counsel around one post-closing file. That coordination contains cost without forcing an early settlement of a valid claim.
A stock purchase agreement transfers everything – including what you did not check.
Representations, indemnities, escrow and closing conditions decide who carries the company’s history. In a share deal, diligence gaps become your liabilities.
We draft and negotiate stock purchase agreements in Israeli and cross-border deals. Reach us on WhatsApp or by email.
RNC Group advises Israeli and foreign businesses on stock purchase agreements, M&A structuring, cross-border contract risk, and post-closing disputes. The firm can coordinate Israeli-law analysis, multilingual documentation, tax and closing support, and phased dispute strategy; clients should contact RNC Group before signing or asserting a claim.
This article provides general information, not legal, tax, accounting, or investment advice. The law and transaction facts may change the analysis, so readers should obtain advice on their specific stock purchase agreement before relying on this material.
This article does not constitute legal advice and is not a substitute for consulting with a qualified attorney. Do not rely on the contents of this article for taking or refraining from taking any action.