
A limited partnership agreement, or LPA, is the central contract governing a hybrid business structure with two legally distinct classes of participants: at least one general partner manages the enterprise and bears potentially unlimited liability, while one or more limited partners contribute capital and generally limit their economic risk to their agreed contribution.
That definition matters when an Israeli company invests across borders, a foreign sponsor forms a private fund, or founders separate operational control from investor capital. The difficult question isn't just what is limited partnership agreement. It's whether the document preserves the intended division between control, economics, liability, and exit rights under the governing law.
Table of Contents
- Introduction – The Strategic Role of a Limited Partnership Agreement
- Understanding the Two-Tier Liability Structure
- Essential Clauses That Define Governance and Capital
- LPA vs Other Business Entities – Flexibility and Control
- Cross-Border Pitfalls – Management Participation and Tax Risk
- Drafting for Exit and Dispute Resolution
- Conclusion – Building a Robust Partnership Strategy
Introduction – The Strategic Role of a Limited Partnership Agreement
A cross-border investor may receive a partnership certificate, subscription documents, a side letter, and a lengthy LPA at the same time. The certificate may establish the vehicle. The subscription document may record the investor's commitment. The side letter may provide negotiated rights. But the LPA is normally the principal operating contract that determines how those documents work together.
The U.S. Internal Revenue Service defines a partnership broadly as an arrangement in which at least two individuals or entities conduct business, contribute money, property, labor, or expertise, and share profits and losses. The IRS also states that a formal written agreement isn't required for a partnership to exist, which means an LPA doesn't create every partnership relationship from nothing. Instead, the written agreement records and organizes the parties' bargain in a form that can govern their rights in practice. The IRS partnership statistics guidance provides the relevant federal framing.
The document behind the label
A limited partnership is designed to separate management authority from invested capital. The general partner, or GP, typically manages the enterprise. Limited partners, or LPs, generally receive economic rights without taking on ordinary management responsibility.
That arrangement only works when the agreement addresses the details that arise after signing. Contributions, ownership or profit-sharing percentages, distributions, voting and consent rights, management powers, transfers, new admissions, withdrawal, dissolution, and disputes all need an operational rule. A short partnership deed that says one party manages and others invest leaves too much unresolved.
The historical development of limited partnerships reinforces the point. Early U.S. limited-partnership statutes appeared in New York and Connecticut in 1822, followed by Pennsylvania in 1836. The first Uniform Limited Partnership Act was adopted in 1916, with later revisions in 1976, 1985, and 2001. Those milestones show why an LPA must be read with the statute governing the partnership rather than treated as a universal template. The historical legal survey on limited partnerships describes that statutory progression.
Practical rule: The LPA should be tested against the formation statute, the tax structure, the commercial deal, and the documents investors actually sign. A provision that works under one jurisdiction may not produce the same result elsewhere.
The strategic value lies in coordination. A carefully drafted LPA can allow a sponsor to retain management authority while giving investors defined information and consent rights. It can also allocate economics differently from voting power, provided the agreement states those distinctions clearly and remains consistent with mandatory law.
Understanding the Two-Tier Liability Structure
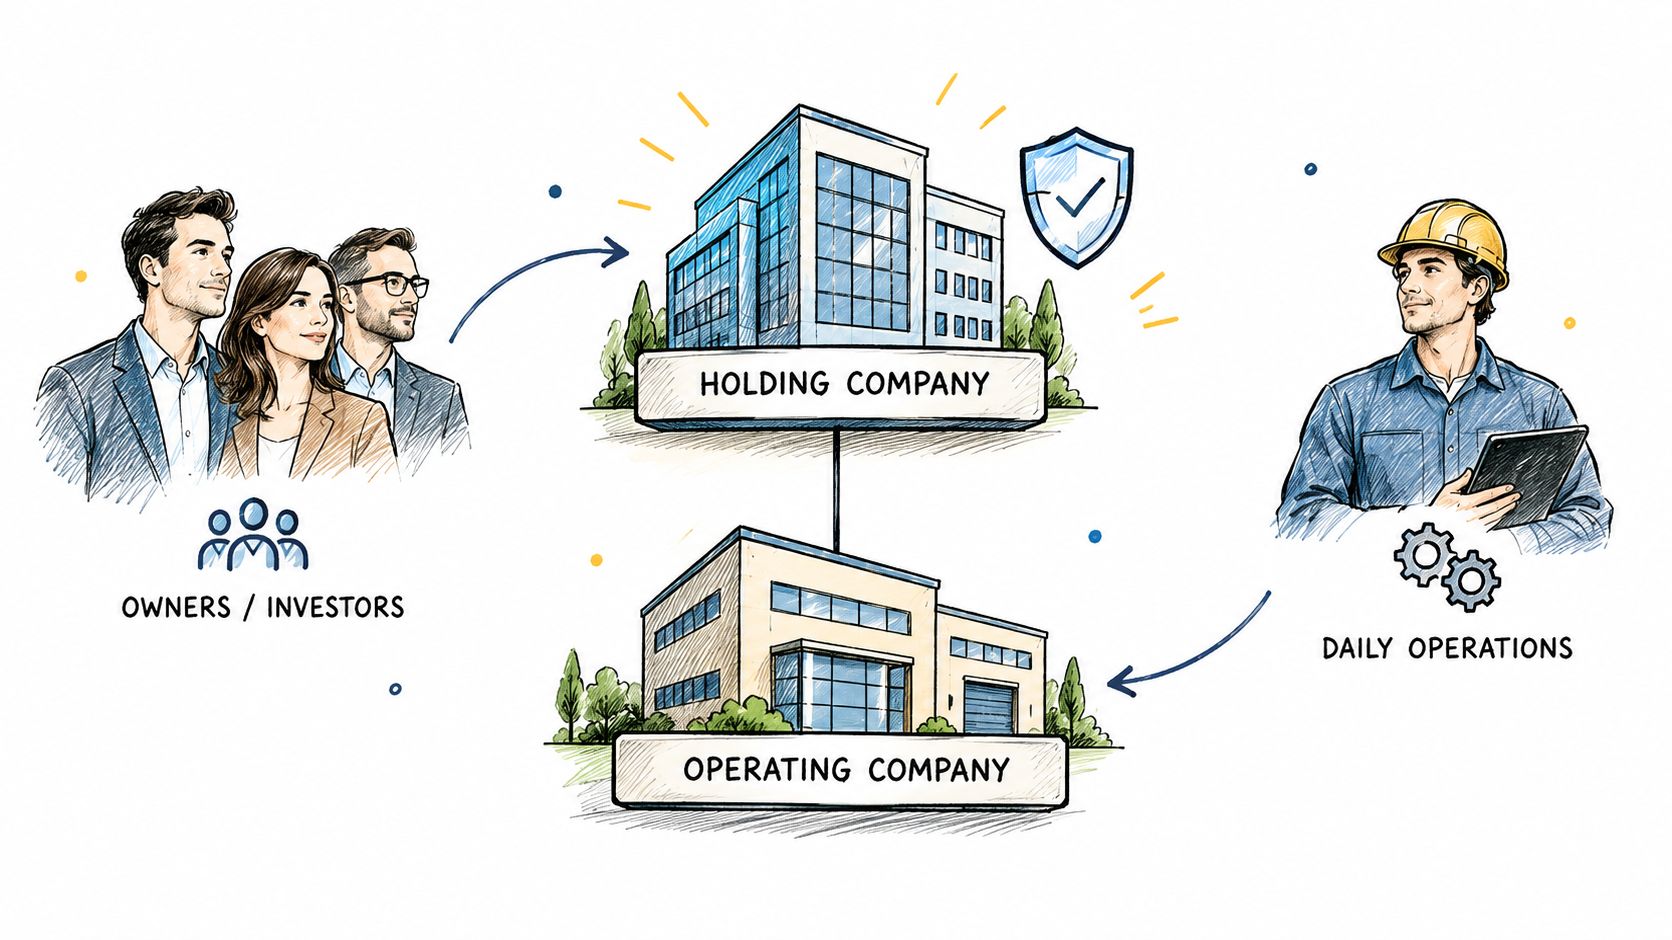
The LP structure has two levels because the parties accept different forms of exposure. The GP normally acts as the partnership's managing and external face, while LPs provide capital and receive economic participation under contractual and statutory limitations.
The trade-off is direct. The GP generally has authority to conduct the business, sign contracts, appoint agents, and make operational decisions. That control comes with potentially unlimited liability for the partnership's debts and obligations. LPs ordinarily avoid day-to-day management and receive protection that is generally connected to their agreed contribution, subject to the governing jurisdiction and compliance with applicable requirements.
Where control and protection meet
An LPA should identify who may bind the partnership and who may only exercise protective rights. The distinction is operational, not cosmetic. Authority to approve a budget or veto a related-party transaction may be intended as investor protection. Authority to negotiate contracts, direct employees, or represent the firm externally may be treated as management participation under some laws.
The United Kingdom illustrates the risk clearly, although the rule is jurisdiction-specific. Under the Limited Partnerships Act 1907, a limited partnership must include at least one GP and one LP. The GP is liable for the firm's debts and obligations, while the LP's liability is generally connected to contributed capital or property. The statute also restricts a limited partner from withdrawing or receiving back that contribution during the partnership's existence. If capital is returned, liability may arise up to the amount returned.
UK registration guidance separately states that a limited partner must not take part in management and generally lacks authority to bind the firm. The official UK registration guidance therefore offers a useful warning for international drafting, but it shouldn't be assumed to state the Israeli or Delaware position.
Oversight without operational authority
The LPA should distinguish reserved matters from management decisions. Reserved matters may include budgets, major acquisitions, borrowing, related-party dealings, admission of investors, changes to the business, or a dissolution decision. The agreement should also specify whether an LP's approval is a veto, a consultation right, or merely an information right.
A disciplined structure usually includes:
- Signature authority: Names the people who may execute contracts and open or operate bank accounts.
- Reserved matters: Defines investor approvals without transferring routine operational control.
- Communications: Identifies who may speak for the partnership to counterparties, regulators, employees, and investors.
- Liability boundaries: Aligns the management provisions with the statutory conditions for limited-partner protection.
The central drafting error is to grant broad investor influence while leaving “management” undefined. A clause that appears commercially sensible may create uncertainty about whether an LP crossed the boundary that supports limited liability. The recommended strategic path is to map every consent right against the governing statute before negotiations close.
Essential Clauses That Define Governance and Capital
A functional LPA is an operating rulebook. It tells the parties when money must be funded, who receives distributions, what happens after default, and which investor can enter the structure.
The U.S. Securities and Exchange Commission identifies capital calls, profit splits, management fees, and limits on LP withdrawals as core terms documented in an LPA. The SEC's private-fund capital-raising guidance is written for a U.S. context, but the drafting lesson is broadly useful: commercial mechanics should appear in the agreement rather than remain in informal understandings.
Turning commitments into enforceable mechanics
A capital-call clause should state the amount or method of determining the commitment, the notice process, the permitted use of funds, and the consequences of failure to fund. A default provision may impose interest, dilution, forfeiture, or a forced-sale remedy. Each remedy changes the bargaining position of the parties, so the agreement should explain how it interacts with valuation, voting, distributions, and any side letter.
Distribution provisions require equal care. A waterfall may return contributions, address a preferred return, and then allocate remaining profits between LPs and the GP through carried-interest mechanics. The drafting must specify whether the calculation applies deal by deal or across the fund, how losses and clawbacks are treated, and which assumptions govern unrealized assets.
The agreement should also separate:
- Management fees, which compensate the GP or manager for agreed services.
- Profit allocations, which determine the parties' economic shares.
- Distributions, which determine when cash or property is paid.
- Tax allocations, which may create taxable income before cash is distributed.
A percentage in the ownership schedule doesn't answer all four questions. A filed Delaware agreement demonstrates the point by assigning a limited partner 99% percentage ownership while giving the GP exclusive authority to manage and operate the business, including authority to dispose of partnership assets without the LP's consent. The agreement separately governs distributions and allocations. The filed Delaware partnership agreement is an example, not a universal rule.
Clauses that protect the relationship
Transfer restrictions should identify permitted transfers, approval standards, regulatory constraints, and the information required from a proposed transferee. The purpose isn't merely to make a sale difficult. It can prevent the partnership from admitting an unsuitable, sanctioned, regulated, or tax-sensitive investor.
Reporting rights should cover financial statements, capital-account information, notices, tax documents, and access to records. Withdrawal restrictions should be coordinated with liquidity rights, valuation procedures, and dissolution provisions.
| Clause category | Operational purpose |
|---|---|
| Capital commitments and calls | Establishes funding obligations, timing, permitted uses, and default consequences. |
| Distributions and waterfalls | Determines how available proceeds move among LPs and the GP. |
| Management authority | Allocates operational power and identifies who may bind the partnership. |
| Fees and expenses | Defines compensation, reimbursable costs, and allocation standards. |
| Transfers and admissions | Controls who may acquire an interest and on what conditions. |
| Reporting and information | Gives LPs the data needed to monitor the investment and tax position. |
| Amendments and consents | Sets approval thresholds and protects negotiated rights. |
| Withdrawal and dissolution | Establishes how the relationship ends and how assets are realized. |
Administrative support can help maintain notices, signature packages, and version control, but it can't replace legal judgment on enforceability or liability. A virtual legal assistant may be useful for document administration after counsel has established the governing framework.
LPA vs Other Business Entities – Flexibility and Control
The right question isn't whether a limited partnership is generally better than an LLC or corporation. The question is whether the business needs control and economics to be separated in a way that the chosen jurisdiction permits.
A corporation typically uses formal directors, officers, share classes, and statutory procedures. An LLC often offers contractual flexibility and may allow members or appointed managers to operate the business. A limited partnership places the GP and LP distinction at the center of the structure, which can make the management boundary clearer but can also make investor participation more sensitive.
Comparing the allocation model
A limited partnership can allocate economic participation, voting rights, consent rights, and management authority through separate provisions. The Delaware example discussed above illustrates that nominal ownership and operational power need not be identical. That flexibility can suit private investment structures in which the sponsor manages assets while investors receive negotiated economic rights.
The same flexibility creates drafting risk. If the agreement gives LPs extensive operational authority, the parties may undermine the very separation on which the structure depends. If it gives the GP unrestricted power, investors may hold an economic interest without meaningful influence over transactions that affect value.
| Structure | Typical organizing document | Main design question | Principal drafting tension |
|---|---|---|---|
| Limited partnership | LPA and formation documents | Who manages, who invests, and what approvals protect investors? | Investor oversight versus management participation. |
| LLC | Operating agreement and formation documents | Are members or appointed managers responsible for operations? | Flexibility versus clarity of authority and fiduciary duties. |
| Corporation | Articles, bylaws, and shareholder arrangements | How do boards, officers, and share classes allocate control? | Formal governance versus transaction-specific flexibility. |
These are general comparisons. The legal result depends on the governing statute, the agreement, the entity's activities, and the way the parties behave after formation. Israeli companies considering a foreign structure should also examine how the arrangement will be characterized for Israeli tax, accounting, reporting, and regulatory purposes.
Choosing by operational reality
A structure that looks efficient on an organization chart may become difficult when investors demand veto rights, the GP seeks to issue a capital call, or an LP wants to transfer its interest. The agreement should therefore be modeled against actual decisions, not only formation documents.
Questions for the design stage include:
- Who hires and dismisses service providers?
- Who approves acquisitions, borrowing, or related-party transactions?
- Can an LP block a transaction without directing the business?
- Can the GP remove or transfer an investor's interest?
- Which rights survive a dispute, sanctions event, insolvency, or regulatory change?
General tax comparisons can be useful for orientation. A business reader reviewing how S Corp treatment is explained in a comparison of LLC and partnership structures should still obtain advice based on the actual jurisdiction and transaction. Entity labels don't determine every tax consequence.
Cross-Border Pitfalls – Management Participation and Tax Risk
Cross-border investors often assume that a clause titled “limited liability” settles the question. It doesn't. The outcome may depend on conduct, statutory conditions, enforceability, creditor remedies, and tax rules that differ between the partnership's governing jurisdiction and the investor's home country.
The management boundary is a clear example. UK guidance warns that an LP participating in management may become liable for debts and obligations incurred while doing so. That rule shouldn't automatically be transplanted into Israeli or U.S. analysis, but it identifies the practical problem: an investor's oversight rights must be drafted and exercised without creating an argument that the investor operated the firm.
The tax allocation must match the economics
For U.S.-taxed structures, Internal Revenue Code section 704(b) principles require an allocation stated in the agreement to have substantial economic effect. The test considers economic effect and substantiality. The allocation should correspond to the underlying economic arrangement, so the partner receiving a benefit receives the related economic benefit and the partner bearing a burden bears the related economic cost. The IRS regulations on substantial economic effect set out the relevant framework.
An LPA should therefore address capital-account maintenance, liquidation mechanics, qualified-income-offset and minimum-gain-chargeback provisions where relevant, and the sequencing of preferred returns, carried interest, losses, and nonrecourse deductions. Silence can be expensive because allocations may instead be determined by the partners' interests in the partnership, which may not produce the intended waterfall.
The commercial model should show both cash and tax outcomes. A partner may owe tax on allocated income before receiving a distribution, so tax-distribution provisions, withholding, documentation, currency conversion, and coordination with side letters deserve separate review.
Labels don't control liability analysis
A narrower issue is addressed in a recent IRS memorandum. A limited partner's conditional promise to restore a deficit capital account may not qualify as a payment obligation where the GP has only discretionary remedies, such as withholding future distributions. The practical question isn't whether the clause is called a capital contribution obligation, guarantee, clawback, or deficit restoration provision.
The relevant questions include:
- Enforceability: Can the partnership compel payment under the agreement?
- Remedies: What happens after default, and are the remedies mandatory or discretionary?
- Liquidation: Does the obligation operate when the partnership winds up?
- Economic risk: Does the partner bear the relevant economic burden?
The IRS memorandum on conditional payment obligations illustrates why drafting labels don't replace analysis. It isn't a universal statement of Israeli law or every foreign tax rule. For an Israeli investor, counsel should examine the partnership law, the investor's domestic tax treatment, withholding exposure, and any treaty or reporting consequences that apply to the actual transaction.
Cross-border warning: A provision can be commercially enforceable under one legal system and produce a different tax or creditor-risk result under another. The agreement, investor conduct, and surrounding documents must be reviewed together.
Drafting for Exit and Dispute Resolution
Many LPAs are negotiated intensely at entry and read only when an investor wants to leave. That timing is backwards. Transfer restrictions, valuation rules, amendment thresholds, removal rights, and dissolution procedures determine whether the investment remains usable when circumstances change.
The agreement should answer whether an LP can transfer its interest, who must approve the transferee, whether the GP has a right of first refusal, and how the interest is valued. It should also state whether a transfer gives the buyer economic rights only or full partner status with voting and information rights.
Exit rights require a valuation process
Publicly filed agreements show that GP powers can be broad. One filed agreement permits the GP to liquidate a limited partner's interest at any time, while other agreements may require a 75% limited-partner vote for dissolution. Those examples are agreement-specific and don't establish a general rule. SEC industry guidance on partnership-interest restrictions and disclosures underscores the need to examine transfer restrictions, suitability requirements, investor documents, and material agreement provisions.
A serious review should identify:
- Trigger events: Default, regulatory restrictions, sanctions concerns, insolvency, death, incapacity, or a change in control.
- Decision-maker: GP, LP committee, majority investors, or an independent valuer.
- Valuation date: The date of the event, notice, transfer, or completed sale.
- Discounts and liabilities: Whether minority, illiquidity, tax, or partnership-level liabilities affect value.
- Payment terms: Cash, installments, set-off, withholding, and security for deferred payment.
A multi-year exit plan can be useful for aligning liquidity, governance, tax, and transaction execution. A general resource on a 3-to-10-year exit planning program may help frame the commercial timetable, but it can't replace the LPA's specific transfer and dissolution provisions.
Disputes should be designed before they arise
Dispute clauses should address governing law, forum or arbitration, interim relief, confidentiality, service of notices, and the relationship between the LPA and side letters. Cross-border parties should also decide how documents will be served and which language controls if versions differ.
Amendment provisions deserve the same attention. A general amendment power can undermine negotiated investor protections unless the agreement distinguishes ordinary amendments from changes affecting economic rights, liability, consent rights, or transferability. A side letter should identify whether it prevails over inconsistent LPA language and whether its protections bind successors.
The recommended strategic path is a clause-by-clause exit exercise before signing. Each investor should test a voluntary transfer, a GP removal dispute, a capital-call default, a sanctions event, an insolvency scenario, and a dissolution vote. If the answer depends on a valuation method or consent threshold that isn't written clearly, the agreement isn't finished.
Conclusion – Building a Robust Partnership Strategy
An LPA is the operating system of a hybrid entity. It connects the commercial bargain to management authority, investor protection, funding obligations, tax allocations, transfers, and exit rights. Israeli companies and international investors should confirm the governing law, preserve the management boundary, model tax and cash waterfalls, and test dispute and valuation provisions before committing capital.
The recommended strategic path is coordinated legal and tax review across every jurisdiction involved. A document that is flexible enough to support the business but precise enough to preserve statutory protections is more valuable than a short template that leaves critical decisions unresolved.
In our experience, the disputes that reach us in partnership structures rarely come from the headline terms. They come from the points nobody modelled at signing: who approves a capital call, how an exit is valued, and what an investor may do without being treated as managing the business. Walking through those three scenarios on paper before the agreement is signed is the cheapest protection an investor or sponsor has.
RNC Group advises Israeli companies and international investors on partnership structures, negotiated LPAs, cross-border risk allocation, dispute-resolution provisions, and commercial exits. To avoid costly mistakes before signing or acting under an LPA, contact RNC Group through its contact page.
Investing through a limited partnership? Read the LPA before the pitch deck.
The LPA sets fees, governance, waterfalls and exit rights. The commercial summary rarely reflects the binding text.
We review and negotiate LPAs for investors and founders. Reach us on WhatsApp or by email.
This article is for general information only and does not constitute legal advice. Laws and their application depend on the facts and jurisdiction and may change. Although we aim to keep this information accurate and current, we do not guarantee that it is complete or up to date. The article may contain omissions or errors. Reading this article does not create an attorney-client relationship with RNC Group. Before making a decision or taking action, seek advice from a qualified lawyer in the relevant jurisdiction.