
Will your Israeli operations face an unexpected tax bill in 2026? A seismic shift is on the horizon. This change fundamentally alters the tax landscape for large multinational corporations. It is a new global floor for corporate taxation.
This guide provides a strategic analysis of the new regulations. The recommended path is to master the new rules. This will ensure full compliance and financial stability.
Navigating Israel’s 2026 Corporate Tax Landscape

Israel’s statutory 23% corporate tax rate is not changing. However, the ground beneath it is shifting. This transformation is due to the OECD’s Pillar Two framework.
Consequently, Israel passed new legislation effective in 2026. The law introduces a Qualified Domestic Minimum Top-up Tax (QDMTT). This action establishes a mandatory 15% minimum effective tax rate.
Who Is Affected by the New Minimum Tax?
This new regulation does not apply to all businesses. Instead, it specifically targets large multinational enterprises (MNEs). The rule uses a clear revenue-based threshold.
- Global Revenue Threshold: The 15% minimum tax applies to MNE groups. Their annual consolidated global revenues must exceed €750 million.
- Impact on Incentives: Companies using generous tax incentives are the primary focus. If an effective rate falls below 15%, a top-up tax is likely.
For example, a company may qualify for a ‘Preferred Enterprise’ rate. The QDMTT still acts as a safety net for the tax authority. It ensures the final tax payment never dips below the 15% floor.
Israel Corporate Tax Rates and Thresholds for 2026
The table below summarizes the main tax rates. It also shows the crucial revenue threshold for MNEs. The 2026 changes require careful attention to these figures.
| Tax Category | Applicable Rate / Threshold | Notes |
|---|---|---|
| Standard Corporate Tax Rate | 23% | The statutory rate applicable to most companies in Israel. |
| Qualified Domestic Minimum Top-up Tax (QDMTT) | 15% | A new minimum effective tax rate under Pillar Two rules. |
| Pillar Two Revenue Threshold | €750 Million | The minimum annual consolidated global revenue for an MNE group to be subject to the QDMTT. |
This data paints a clear picture for large MNEs. The headline rate remains 23%. Yet, the reality is a new, non-negotiable floor of 15%.
Actionable Steps for Risk Mitigation
Understanding these changes now is the only way to mitigate surprises. This new law introduces a significant compliance and reporting burden. Therefore, companies must prepare for it immediately.
- Model Tax Liability: MNEs must proactively model their potential tax liability. This includes factoring in all current tax breaks and incentives.
- Assess Financial Impact: Next, they must assess the bottom-line impact. This involves calculating any potential top-up tax accurately.
- Build Compliance Mechanisms: Finally, companies must build robust compliance mechanisms. These systems will handle new reporting requirements effectively.
Preparing for 2026 is a critical component of strategic financial planning. Understanding the history of Israel’s tax policy provides valuable context. This reveals a drive for global competitiveness.
The Deliberate Path to a Lower Tax Rate
Businesses in Israel faced a different picture in the early 2000s. The corporate tax rate in israel stood at a hefty 36%. This was a significant hurdle for attracting global capital.
Recognizing this, policymakers began a planned campaign of tax reductions. The mission was to make Israel a more attractive investment hub. This would also spark domestic economic growth.
This consistent, long-term approach signals a pro-business environment. It provides stability for long-term investment decisions. Professional reference points like Lloyds Bank Trade offer global context.
The logic was straightforward and effective. A lower tax burden leaves more capital for companies. Consequently, this encourages reinvestment, expansion, and job creation.
Navigating Domestic Policy and Global Pressures
The path to a lower tax rate was not perfectly straight. For instance, local realities influenced national strategy. Social justice protests in 2011 led to the Trajtenberg Committee.
The committee’s recommendations caused a brief, temporary rate hike. This moment showed how internal pressures can steer fiscal policy. However, the interruption did not last long.
Following that, the government got back on course. The corporate tax rate in israel has been cut dramatically. It landed at a competitive 23% on January 1, 2018.
Stabilization and the Current Rate
That move in 2018 brought us to the current state. The corporate tax rate in israel was locked in at 23%. This stability has been a game-changer for business planning.
The 23% rate represents a carefully struck balance. It generates enough revenue for public services. It also maintains a competitive edge against other economies.
Ultimately, this journey from 36% to 23% is significant. It is the story of a nation shaping its economic destiny. Understanding this history is the first step to effective navigation.
Understanding Your Total Corporate Tax Burden
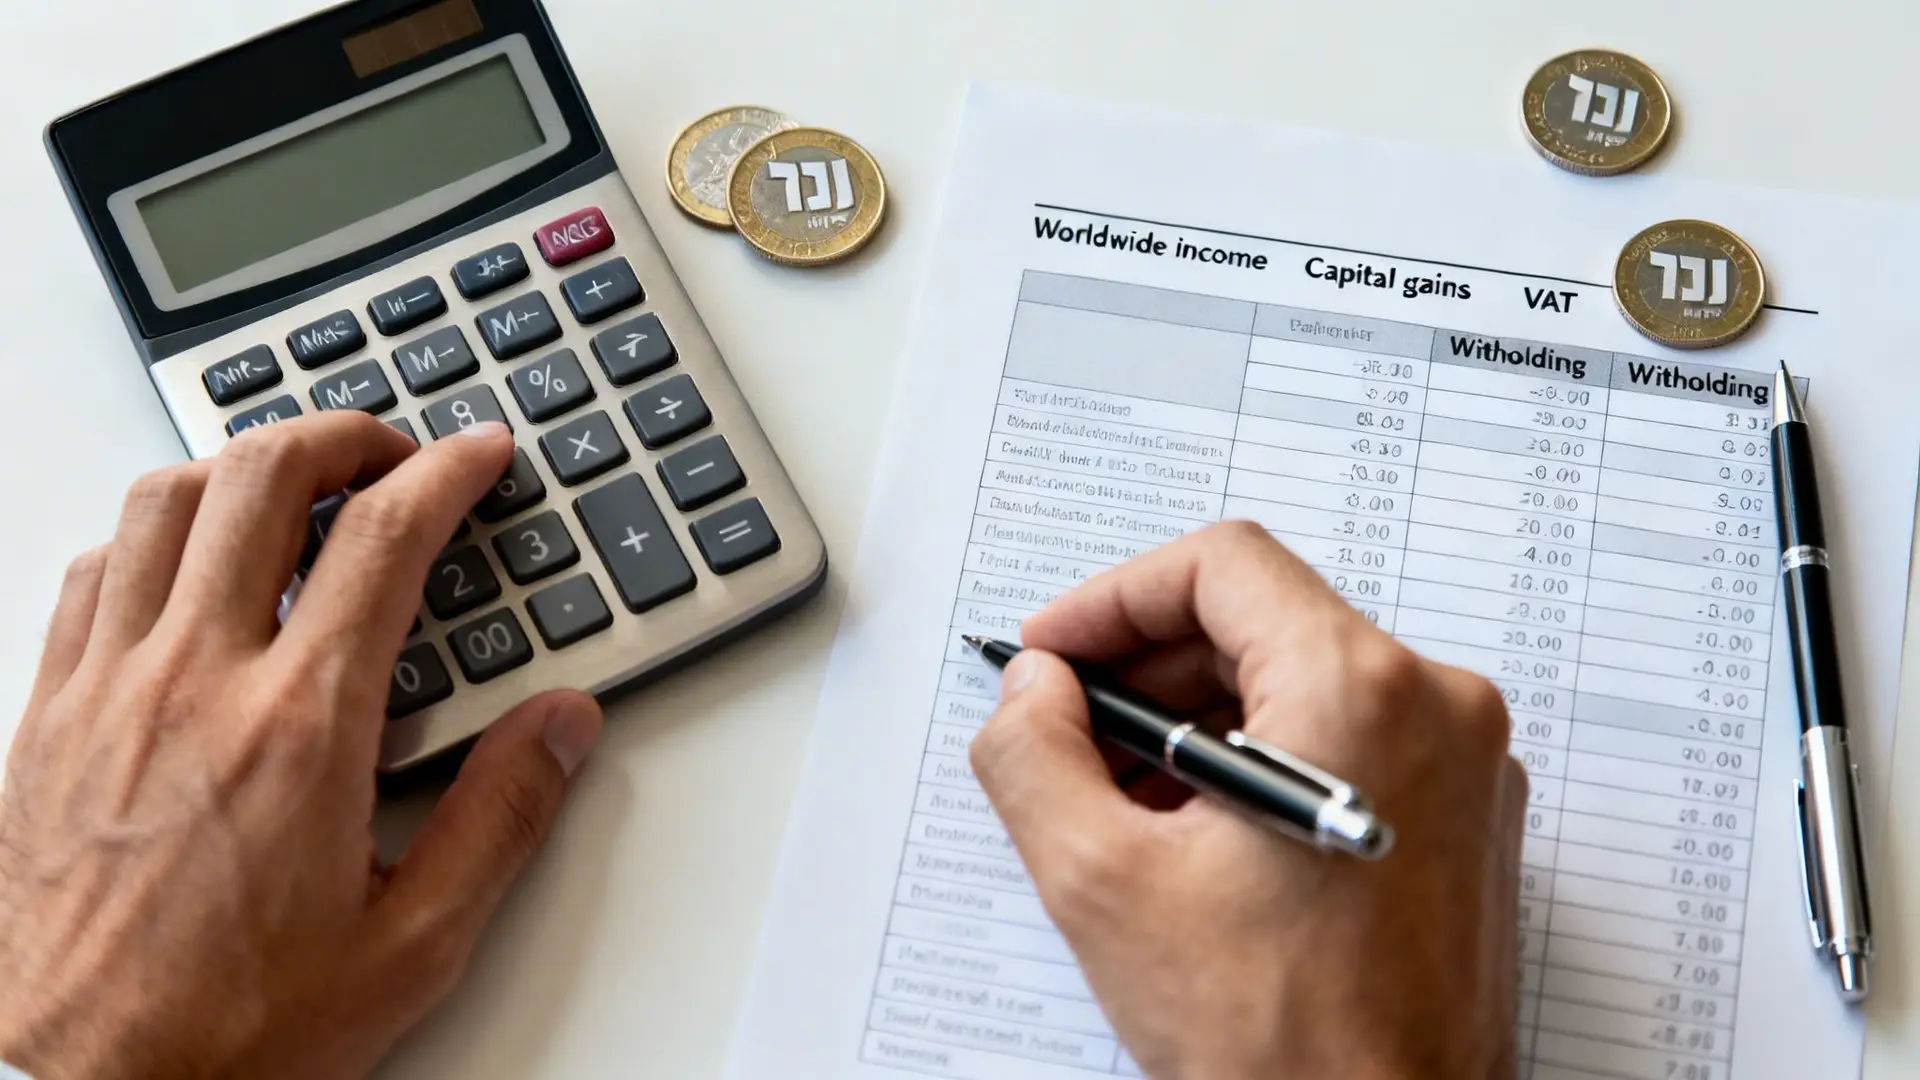
The headline corporate tax rate in Israel is 23%. But that number is just the tip of the iceberg. A company’s actual tax bill is a far more complex equation.
It mixes corporate income, residency status, and capital gains. Getting a handle on this total burden is essential. It is a matter of corporate financial survival.
Clarifying the Scope of Israeli Taxation
The first question is fundamental: where is a company a “resident”? This determination dictates the scope of tax obligations. It is a critical factor for compliance.
An Israeli resident company is taxed on its worldwide income. This means all profits fall under the Israeli tax net. In contrast, a non-resident company is taxed only on Israel-sourced income.
This distinction is the bedrock of compliant tax planning. It shapes everything from cross-border deals to M&A due diligence. Professional resources like PwC’s comprehensive tax summaries provide detailed insights.
Israel’s total tax-to-profit ratio stands at 25.3%. This is lower than in the US (36.6%) or Germany (48.8%). However, this advantage comes with strict rules requiring careful structuring.
How Capital Gains Are Treated
Operational profits are one thing, but asset sales are another. Profit from selling a major asset is a capital gain. This includes buildings, shares, or other valuable assets.
Here, Israeli law is relatively straightforward. Capital gains are taxed at the standard 23% rate. This parity simplifies the math for businesses.
However, a major asset disposal can trigger a large tax event. Companies need to plan for this well in advance. Strategic foresight is therefore essential.
Other Critical Taxes That Impact Profitability
A realistic financial model must look beyond income tax. Several other taxes directly drain cash flow. Ignoring them is a recipe for a nasty financial surprise.
Here are key taxes to factor into calculations.
-
Value Added Tax (VAT): VAT is a standard 17%. It applies to most goods and services in Israel. This constantly impacts a company’s day-to-day cash flow.
-
Withholding Tax on Dividends: Companies must withhold tax on dividend distributions. The rate is 30% for “significant” shareholders. An applicable tax treaty can bring these rates down.
-
Withholding Tax on Interest and Royalties: Paying interest or royalties to a non-resident has a default 23% tax. Again, a tax treaty can often reduce this rate.
These are active financial levers, not just administrative notes. Withholding taxes directly reduce net cash moved across borders. This impacts intercompany loans and IP licensing strategy.
Unlocking Powerful Tax Incentives and Reduced Rates
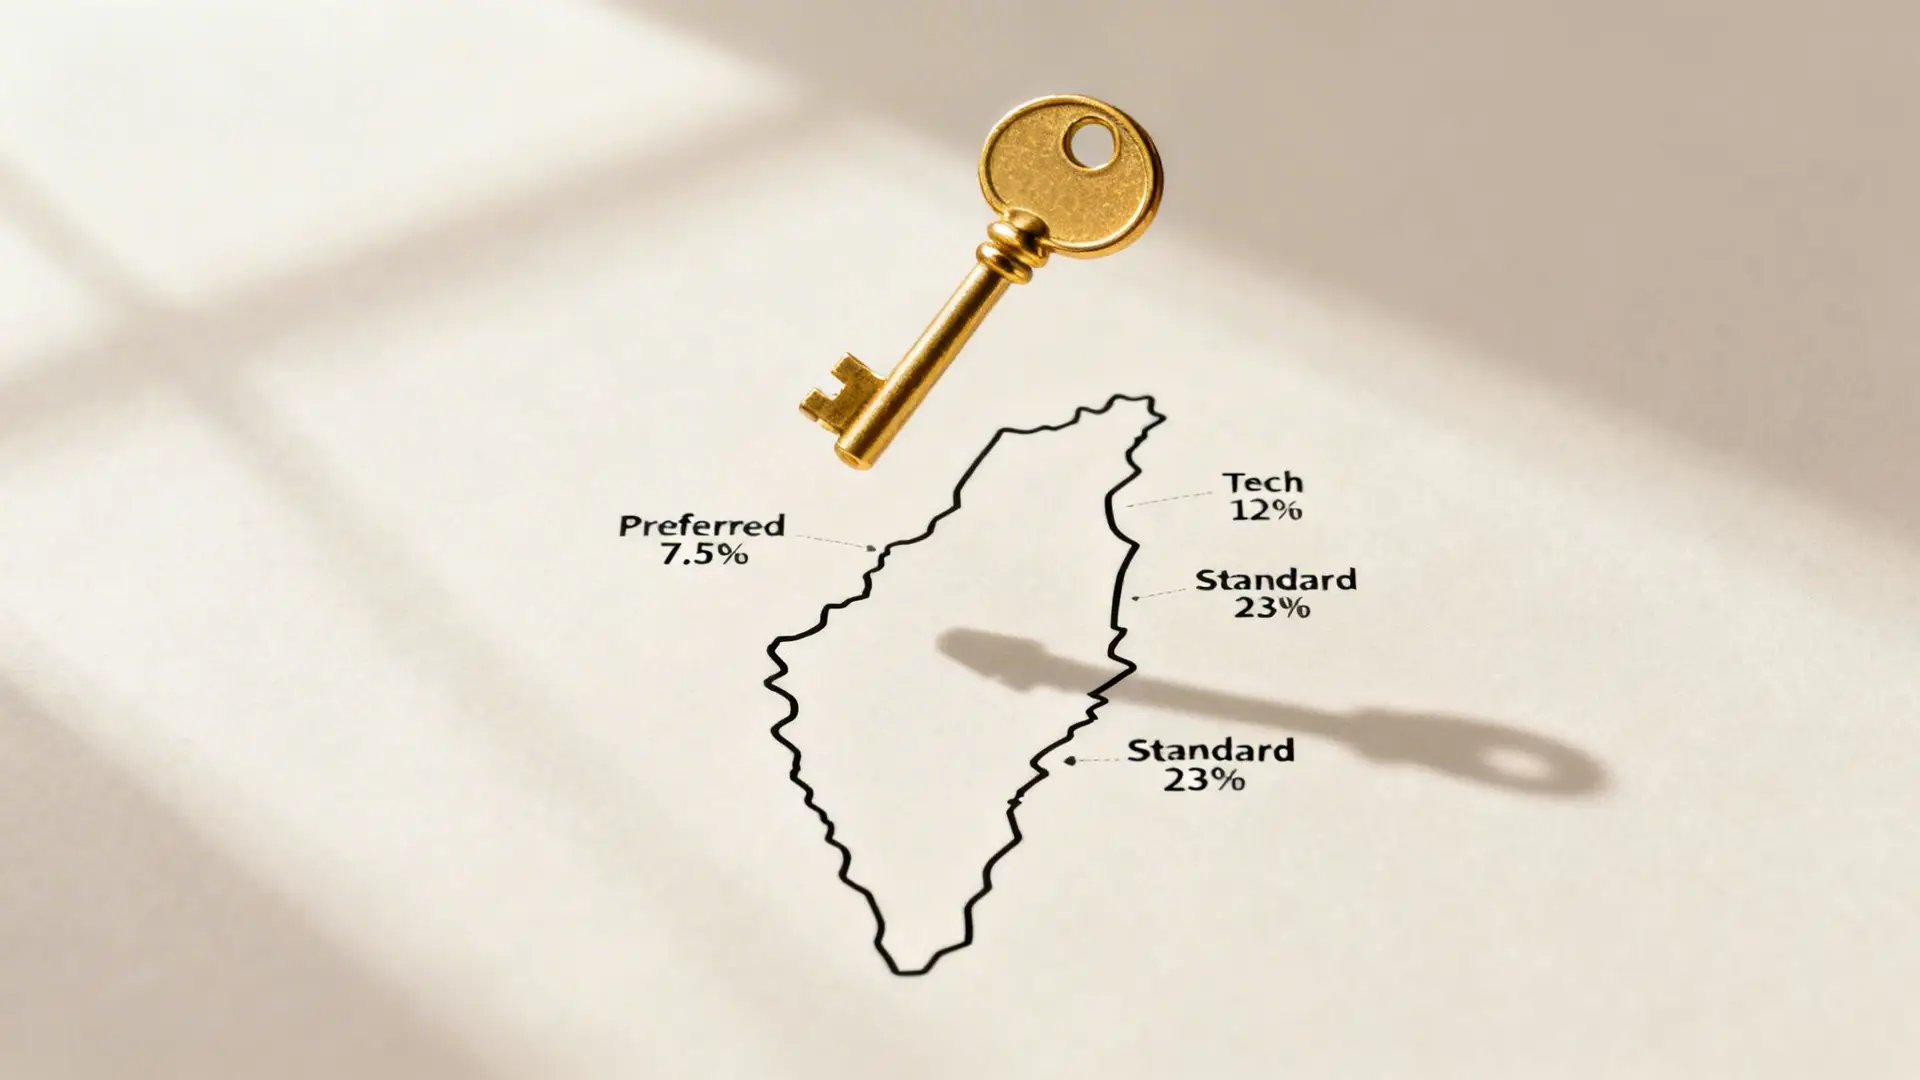
The standard 23% corporate tax rate is often just a starting point. It can lead to a dramatically lower tax bill. The key is qualifying for Israel’s powerful incentive programs.
Israel uses its tax code strategically. The Encouragement of Capital Investments Law attracts specific businesses. Therefore, understanding this landscape is a core strategic function.
Qualifying as a Preferred Enterprise
The first major path is achieving “Preferred Enterprise” status. This designation is for industrial companies contributing to exports. It provides a significant tax advantage.
A company must meet a crucial test to qualify. At least 25% of its total revenue must come from exports. This is for a single market of over 14 million people.
The tax rate then depends on physical location.
The policy’s objective is crystal clear. It uses the tax code for national and regional development. This powerful lever steers investment across the country.
Here’s how the location-based rates break down:
- Development Area A: The corporate tax rate plummets to just 7.5%. This applies to priority regions like the Negev or Galilee.
- Other Areas: The rate is a still-attractive 12%. This is for companies located anywhere else in the country.
This system creates a compelling argument for establishing operations. It encourages moving outside the traditional economic hub. Consequently, it promotes balanced national growth.
The Technology Enterprise Regimes
Israel has created specialized incentive tracks for tech companies. These regimes foster R&D and anchor valuable IP in the country. They are central to the nation’s economic strategy.
The two main categories are technology enterprise regimes. A “Preferred Technology Enterprise” must meet specific criteria. Its R&D spend must equal at least 7% of turnover.
Once approved, these tech firms pay a flat tax rate of 12%. This applies to all their technological income. The special rate makes the corporate tax rate in Israel globally competitive.
For large multinationals, Israel offers an even better option. The Special Preferred Technology Enterprise status targets these groups. These tech giants receive an exceptionally low 6% tax rate.
Finally, dividends paid from these profits have a reduced 4% withholding tax. This combination creates a powerful gravitational pull for major tech companies. The strategy is explorable with legal experts like the ADVOC network.
Your Pillar Two Action Plan for 2026
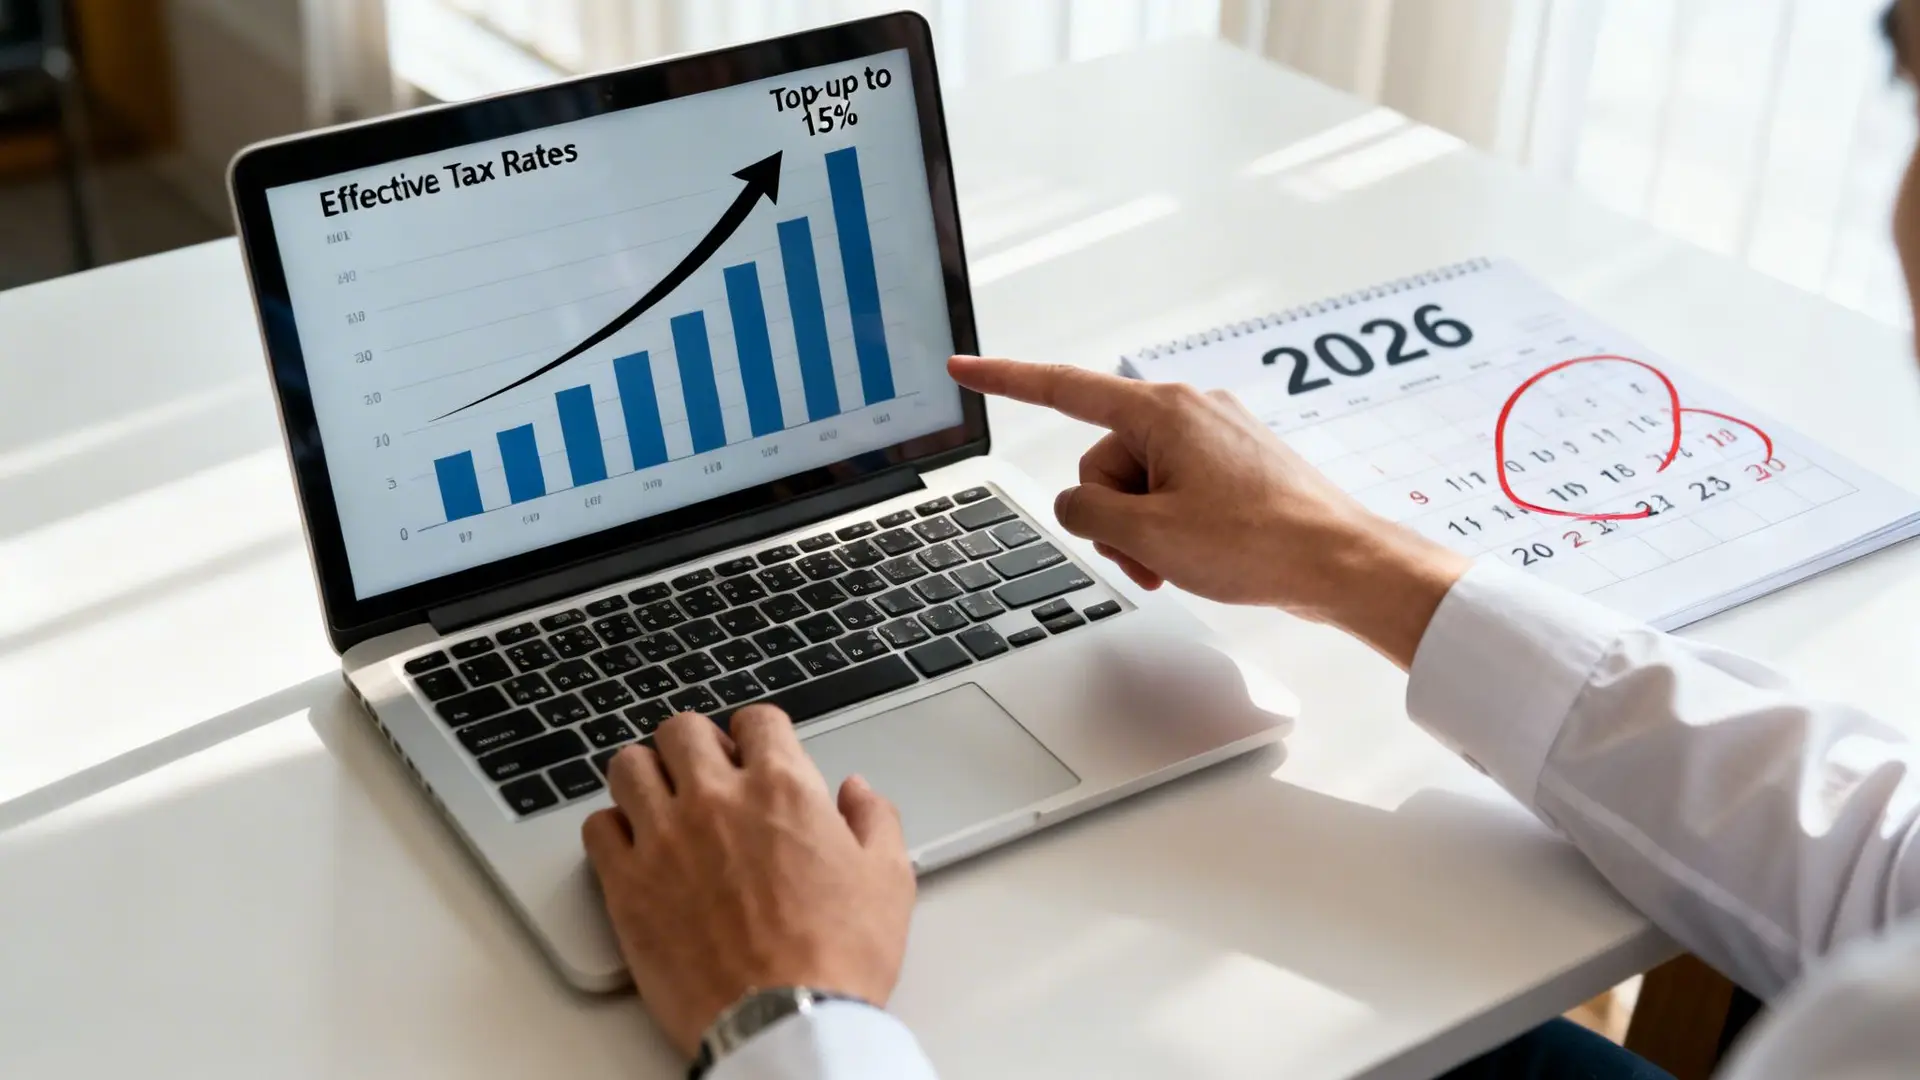
What if Israel’s generous tax incentives become a major liability? The clock is ticking towards 2026. A new era of global tax compliance is already here.
The OECD’s Pillar Two framework has officially arrived. It changes everything for large companies operating in Israel. Understanding it is now mission-critical for financial strategy.
What Pillar Two Means for Israel
Starting in 2026, Israel is implementing a hard tax floor. MNEs must pay a minimum 15% effective tax rate. This applies to every country, including Israel.
To achieve this, Israel rolled out its own QDMTT. This is Israel’s defensive shield against foreign claims. It gives Israel the first right to collect any tax shortfall.
It’s a straightforward mechanism with a clear impact. For example, a company with a 12% rate will face a 3% top-up tax. Its final effective tax bill suddenly jumps to the mandatory 15% threshold.
This new law cements Israel’s authority in the global tax arena. The law requires direct interpretation based on the OECD’s English-language guidelines. Professional references from organizations like the Tax Foundation provide these standards.
How to Assess Your Company’s Exposure
Every CFO needs to ask a simple question. Does the MNE group’s global revenue exceed €750 million? If yes, its Israeli operations are officially on the hook.
The next step is to calculate the true effective tax rate (ETR). This is not about the statutory corporate tax rate in Israel. It is a far more complex calculation under Pillar Two rules.
Companies that gained most from incentives now face the biggest shock. For instance, a company paying 7.5% is staring down a huge tax hike. The QDMTT will add another 7.5% to reach the 15% minimum.
A Three-Step Plan to Mitigate Your Risk
With the 2026 deadline approaching, inaction is not an option. The reporting burdens are immense and will lead to costly surprises. The recommended strategic path is a proactive approach.
Here are three critical actions to take now.
- Model Your ETR Immediately. The first priority is a detailed ETR calculation. This requires a deep dive into the group’s financials. A clear, data-driven picture of where the company stands is necessary.
- Quantify Your Top-Up Tax Liability. Next, determine the exact size of the potential top-up tax. This number is the direct financial exposure. It must be integrated into 2026 financial forecasts immediately.
- Rethink Your Global Tax Strategy. Finally, evaluate how this new liability impacts the entire tax structure. The systems must be ready for new reporting requirements. The first report is due 15 months after the 2026 tax year ends.
This framework moves a company from a reactive to a strategic position. It allows for getting ahead of challenges. Meticulous planning is the only way forward.
Advanced Tax Planning Strategies
Proactive planning is a necessity for any corporation in Israel. Structuring operations correctly can unlock significant tax efficiencies. A few key strategies offer major advantages.
Mergers and acquisitions (M&A) are a perfect example. A deal’s structure carries vastly different tax consequences. This demands sharp analysis long before signing papers.
Holding companies are another powerful tool. An Israeli holding company can act as a central hub. However, the structure must have genuine commercial substance.
Finally, transfer pricing rules remain a battleground. These regulations dictate pricing between related entities. Proof of arm’s-length principles is mandatory.
The most effective approach fuses these elements into one strategy. This turns tax from a simple cost center into a powerful tool. It builds corporate value while managing compliance risk.
Navigating Transfer Pricing with Precision
Make no mistake: transfer pricing is a high-priority audit area. A multinational enterprise must maintain robust documentation. This includes a master file and a local file.
Failing to do so can have severe consequences. Authorities can reallocate profits between entities. This move often triggers double taxation and staggering penalties.
A proactive and documented transfer pricing policy is non-negotiable. It is a critical component of risk management. Therefore, it demands constant attention and expertise.
The Annual Compliance Calendar
Meeting deadlines is the bedrock of good tax governance. A clear, well-managed compliance calendar is the first line of defense. Here are the key dates every company in Israel must master.
- Monthly/Bi-Monthly Installments: Companies must make advance tax payments. These are due on the 15th of each month. They are based on the previous year’s tax assessment.
- Annual Corporate Tax Return: The filing deadline is five months after the fiscal year-end. For most, the due date is May 31. Extensions require prior approval.
- Audited Financial Statements: These must be attached to the annual tax return. This means getting auditors involved well ahead of the deadline. It avoids a last-minute scramble.
- Withholding Tax Reporting: Reports for withheld taxes are due by the 15th of the following month. This applies to salaries, dividends, and supplier payments.
Staying on top of this schedule is a core operational responsibility. It ensures good standing with the authorities. It also prevents the costly distractions of audits.
Answering Your Key Questions on Israel’s Corporate Tax
Understanding the tax landscape is about strategy, not just compliance. Let’s break down the most common questions. This provides clarity for business leaders and investors.
What Is the Standard Corporate Tax Rate in Israel for 2026?
The headline number you need to know is 23%. This is Israel’s standard corporate income tax rate. It has been holding steady since 2018.
This 23% rate is the starting point for calculations. It applies to the worldwide income of Israeli resident companies. It also applies to Israeli-sourced income for non-resident companies.
How Do Tax Incentives Change a Company’s Final Tax Bill?
Israel’s tax incentives can dramatically lower the actual tax burden. A company’s final rate is not one-size-fits-all. It depends heavily on classification and location.
For instance, a “Preferred Enterprise” rate could be 12% or 7.5%. But be aware, a major global shift is changing the game. This will happen in 2026.
Starting in 2026, a new global rule is coming into force. It requires a minimum 15% effective tax rate. This is driven by the OECD’s Pillar Two framework.
Who Is Affected by the New 15% Minimum Tax?
This new 15% minimum tax is not for everyone. It targets MNEs with global revenues over €750 million. If a company meets this threshold, this rule is critical.
Here’s how it works in practice. If an Israeli operation’s tax rate is below 15%, it faces a “top-up tax.” This ensures compliance with the global minimum.
For example, a company with a 7.5% rate will pay an additional 7.5%. This brings the total effective rate up to the 15% floor. The Tax Foundation offers more details on this global standard.
Disclaimer: The information provided in this post, including all visual media and accompanying text, is for informational and educational purposes only. It does not constitute legal, financial, or professional tax advice.
Tax laws in Israel, specifically regarding the OECD Pillar Two framework and the Qualified Domestic Minimum Top-up Tax (QDMTT), are subject to complex regulatory interpretations and legislative updates. Every corporate structure is unique, and the application of these rules depends on specific facts and global revenue thresholds.
Action Required: Do not make financial or strategic decisions based solely on this content. We strongly recommend consulting with a qualified tax advisor or legal counsel specializing in Israeli and international tax law to assess the specific impact on your operations for the 2026 tax year.
The author and publisher disclaim any liability for actions taken or not taken based on the contents of this guide.