
In 2026, the most dangerous M&A document may be the one that looks routine. An asset purchase agreement decides which liabilities follow the business, which remain with the seller, and whether the buyer receives usable assets or a litigation package.
The document also controls tax allocation, employee transitions, contract consents, working-capital adjustments, escrow recovery, and post-closing claims. Treating it as a boilerplate closing form leaves commercial decisions hidden inside definitions, schedules, and exceptions.
Why an Asset Purchase Agreement Is the Most Misunderstood Contract in M&A
An asset purchase agreement is a risk-transfer engineering document, not a standard form attached to a closing checklist. It defines the boundary between the acquired operations and the seller’s historical exposure, then assigns the cost when that boundary fails. In cross-border deals involving Israeli operations, execution depends on whether the schedules, consents, records, employees, and remedies work in practice, not merely whether the clauses look familiar.
The modern U.S. sales-law framework traces a major milestone to Uniform Commercial Code Article 2, published in 1952. It standardized rules for transactions in goods across the United States and became widely adopted by the mid-1960s in all 50 states except Louisiana in full form, as described in this overview of buyer and seller rights under UCC principles. Article 2 still matters when an APA covers inventory, machinery, tangible assets, or transfers combining goods and services.
The buyer generally seeks clean title, limited assumed liabilities, enforceable representations, and a practical path to recovery. The seller generally seeks tax efficiency, a defined liability ceiling, prompt escrow release, and limited post-closing exposure. The 2025 ABA Deal Points Study helps frame these negotiations as recurring allocation choices, but the signed APA must adapt them to the transaction’s assets, liabilities, and enforcement realities.
Practical rule: Convert each material diligence finding into a defined asset or liability, a schedule, a covenant, a purchase-price adjustment, an indemnity, or a closing condition. General assurances rarely protect a buyer after closing.
The cost of boilerplate drafting
Weak drafting can leave environmental obligations, payroll claims, customer consent requirements, and contract termination rights outside the intended allocation. A buyer may believe it acquired an operating business, while the seller later argues that records, logins, data, permits, or employee obligations remained behind.
The trouble often begins with “all assets used in the business.” That wording can capture property the seller meant to retain or omit operational items the buyer needs on day one. Wilkinson Law notes that excluded assets require precise identification, particularly for data, credentials, records, and other less visible operating assets (guidance on excluded assets in asset purchase agreements).
A strong APA should answer three questions for every disputed item: who pays, who performs, and what happens if the assumption proves wrong? The buyer should not sign until material diligence findings connect to the asset schedule, liability schedule, price mechanism, indemnity, or closing conditions.
Asset Deal vs Share Deal vs Merger
The structural choice should begin with liability and execution risk, not tax alone. An asset purchase lets the buyer select assets and liabilities, while a share purchase generally transfers ownership of the existing entity with its history intact.
A statutory merger can provide continuity and simplify the transfer of contracts or employees, but it may also carry the target’s liabilities into the surviving structure. Israeli and multinational buyers must also assess consent requirements, employment rules, tax treatment, regulatory review, and enforcement before selecting the route.
A useful starting point for commercial buyers appears in this practical discussion of whether to sell assets or shares. The answer depends on what the buyer needs to preserve and what it needs to exclude.
| Dimension | Asset Purchase | Share Purchase | Statutory Merger |
|---|---|---|---|
| Liability profile | Buyer assumes listed liabilities and seeks to exclude the rest | Target entity continues with its existing liabilities | Surviving entity generally receives the merger business and obligations |
| Asset selection | Buyer can select assets, contracts, employees, and records | Buyer receives the entity and its assets as they stand | Merger structure usually transfers the business through statutory mechanics |
| Consents | Material contracts may require assignment consent | Change-of-control provisions may require review or consent | Statutory effects may reduce some transfer friction, subject to contract terms |
| Employees | Parties must address transfer, continuity, and termination liabilities | Employees generally remain with the same employing entity | Employees may continue through the surviving entity |
| Tax basis | Buyer commonly seeks a purchase-price allocation and stepped-up basis | Buyer generally inherits the target’s historic asset basis | Tax treatment depends on structure and applicable rules |
| Execution risk | Schedules and transfer instruments require detailed coordination | Entity-level liabilities and historic records require extensive diligence | Statutory approvals and merger mechanics require careful sequencing |
Where the asset route protects
An asset deal works best when the buyer can identify the operating package precisely. That package may include customer contracts, intellectual property, inventory, equipment, permits, data, and selected employees. The buyer then needs enforceable assignment mechanics and a liability schedule that excludes everything else.
However, selective acquisition creates consent friction. A customer contract may prohibit assignment. A licence may depend on the seller’s entity. An employee may hold essential know-how that doesn’t transfer automatically. A buyer can receive a tax step-up yet lose the commercial value of an asset it cannot legally or practically use.
Where shares or a merger work better
A share purchase may suit a regulated business with licences, customer relationships, and workforce continuity tied to the target entity. It reduces the need to transfer each asset, but it also leaves the buyer exposed to historical obligations unless indemnities, escrow, insurance, or other protections address them.
A merger may fit a transaction requiring legal continuity or statutory transfer effects. Yet the buyer still needs a detailed liability and regulatory analysis. The sequencing question should come before the term sheet: which structure preserves the value drivers, and which structure places unacceptable historical risk inside the buyer’s perimeter?
Anatomy of the Essential APA Clauses
An asset purchase agreement succeeds only when its clause groups work together. The asset definition must match the purchase-price allocation. The liability schedule must match the indemnity. The closing conditions must match the consents, filings, and transfer instruments.
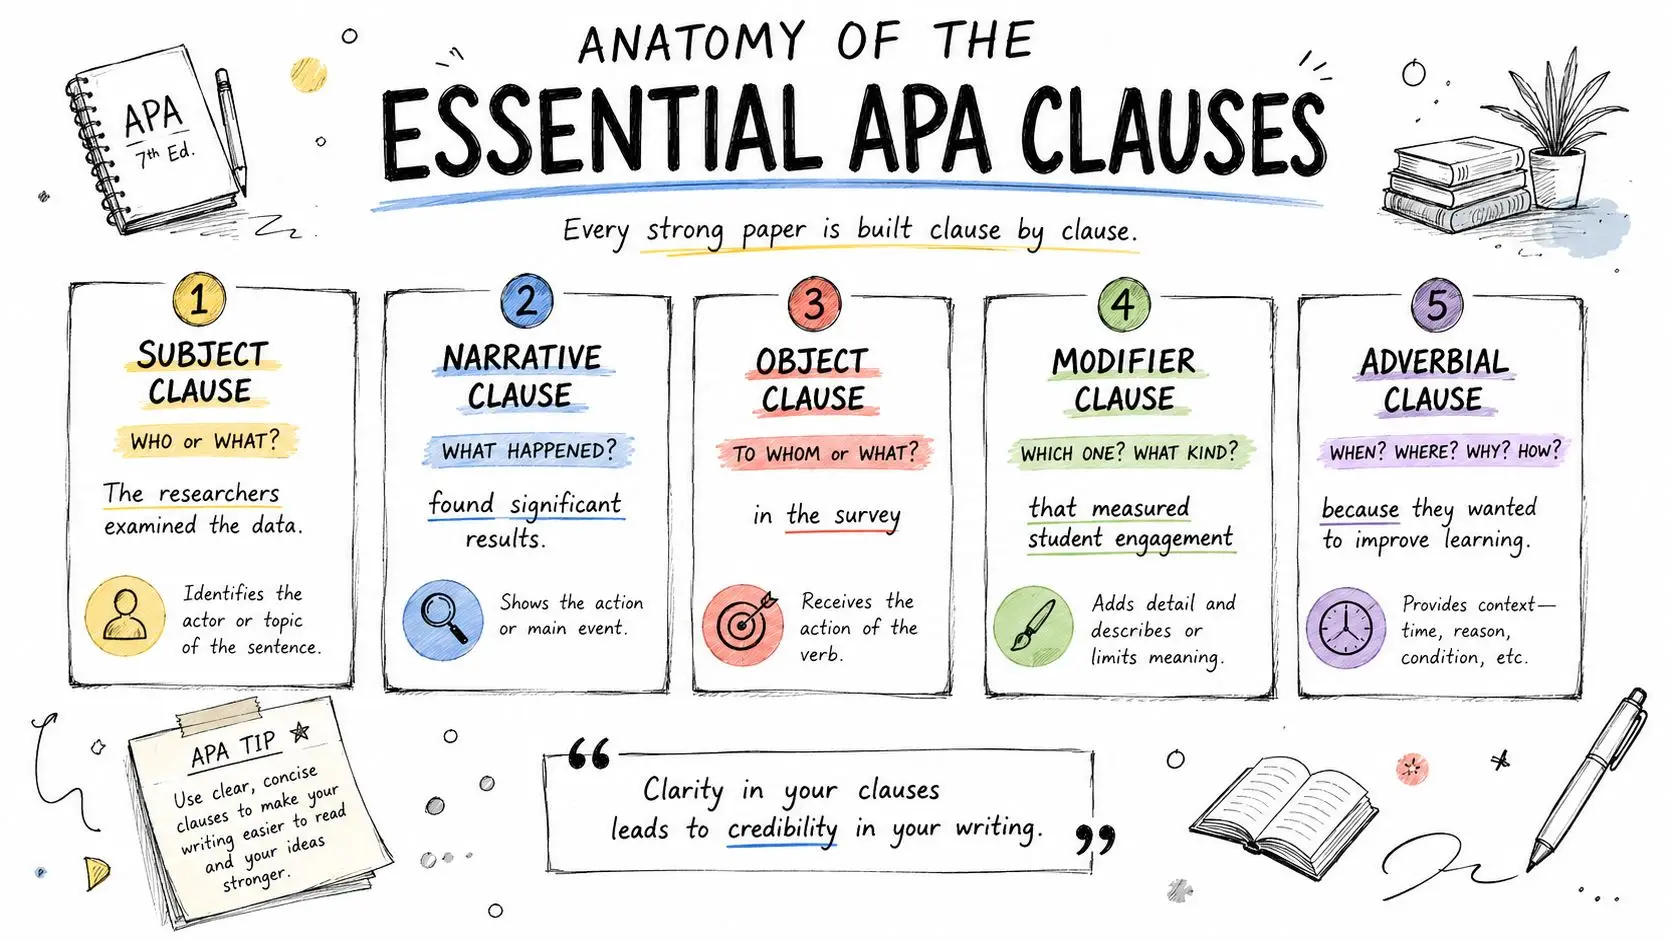
Seven clause groups that carry the deal
-
Purchased and excluded assets. List tangible assets, intellectual property, contracts, receivables, inventory, records, data, credentials, permits, and claims. Then identify excluded cash, tax refunds, insurance rights, corporate records, and unrelated assets with equal precision.
-
Assumed and retained liabilities. The buyer should assume only listed obligations. The seller should retain taxes, pre-closing employee claims, undisclosed litigation, excluded contracts, and other legacy liabilities unless the parties deliberately negotiate otherwise.
-
Purchase price and adjustments. Define working capital, debt, cash, transaction expenses, disputed amounts, accounting principles, review periods, and the decision-maker for unresolved calculations. A formula without defined accounting rules creates a post-closing dispute.
-
Representations and warranties. Cover authority, title, contracts, compliance, tax, employment, intellectual property, data, litigation, environmental matters, and financial information. A buyer should examine knowledge qualifiers carefully. Missing “knows or should have known” language can create arguments about buyer-side negligence and reliance.
-
Indemnities and survival. Specify caps, baskets, exclusions, notice, defence control, mitigation, exclusive-remedy language, and survival periods. A separate escrow can provide practical recovery without immediate litigation.
-
Pre-closing covenants. Control ordinary-course operations, employee changes, contract amendments, capital expenditure, customer communications, regulatory cooperation, and access to information.
-
Closing conditions. Address consents, releases, lien discharges, required filings, tax certificates, delivery of schedules, employment documents, and the absence of specified adverse events.
The public deal record illustrates how substantial APA-linked structures can become. One SEC filing disclosed asset purchase agreement exposure of $5,063 million in 2012, $4,685 million in 2013, and $4,205 million in 2014 (SEC filing disclosure). Those figures show why drafting mechanics deserve board-level attention.
Clause interaction matters more than clause length
A material adverse effect definition without appropriate industry-wide carve-outs can give one side an uncertain termination right. A purchase-price adjustment locked before completion accounts can make the buyer pay for value that the final balance sheet doesn’t support. An escrow release schedule that extends beyond the indemnity cap can also create an unintended recovery structure.
The drafter should test the document through adverse scenarios. Ask what happens if a key customer refuses consent, an employee claims severance, a tax authority challenges allocation, or the buyer discovers an excluded liability after closing. The answer must appear in operative language, not in the parties’ expectations.
Due Diligence and Negotiation Strategy
Diligence should produce drafting instructions, not a document archive. Each workstream must feed a defined APA mechanism, such as a disclosure schedule, purchase-price adjustment, specific indemnity, covenant, or closing condition. In a cross-border Israeli transaction, that mapping also has to account for local registrations, employment rules, tax documentation, and the practical ability to transfer contracts and operating assets.
A sequenced buyer workflow
-
Corporate review: Confirm ownership, authority, liens, subsidiaries, and approvals. Convert the results into title representations, lien releases, and closing deliverables.
-
Financial review: Test revenue, working capital, debt, cash, and transaction expenses. Tie findings to the purchase-price formula, accounting principles, and any completion accounts process.
-
Tax review: Identify unpaid taxes, audits, transfer taxes, VAT, withholding duties, and allocation assumptions. Put material findings into tax indemnities and cooperation covenants, while reserving allocation mechanics for the tax provisions.
-
IP and data review: Verify ownership, registrations, licences, open-source exposure, cybersecurity controls, credentials, and operational records. Schedule each transfer item and identify assets that cannot move without a consent or replacement arrangement.
-
Employment review: Map employees, contractors, benefits, termination exposure, collective arrangements, and transfer obligations. State who bears severance, paid-time-off, and other accrued employment liabilities.
-
Environmental review: Match site findings, permits, contamination, and remediation obligations to specific indemnities and retained liabilities. Avoid relying on a general representation for a known site risk.
-
Contracts review: Identify assignment restrictions, change-of-control provisions, exclusivity, termination rights, customer concentration, and consent timing. Classify each contract by whether it transfers at closing, requires consent, or needs a transition solution.
The 2025 ABA Private Target M&A Deal Points Study records separate escrows for post-closing adjustments in about 58% of deals, references to RWI in 63%, and a mean indemnity cap of almost 16.79% of transaction value. The practical point is not to copy market percentages into the draft. It is to decide whether purchase-price adjustments and general indemnity claims require separate recovery structures, particularly where the seller wants limited post-closing exposure.
Choosing recovery architecture
| Variable | Indemnity Only | Hybrid, RWI on Core Reps | Full RWI |
|---|---|---|---|
| Seller exposure | Broadest negotiated exposure | Reduced exposure for insured risks | Often narrower contractual recovery |
| Buyer recovery | Direct claim against seller, subject to limits | Insurance plus negotiated seller protection | Primarily insurance for covered claims |
| Diligence burden | Contract and seller creditworthiness dominate | Underwriter review supplements diligence | Underwriter scrutiny becomes central |
| Typical exclusions | Negotiated exclusions remain critical | Cyber, sanctions, FCPA, tax, and known issues require review | Policy exclusions can remove expected protection |
| Best fit | Seller has credit strength and accepts meaningful liability | Parties want balanced risk transfer | Seller seeks a clean exit and buyer accepts policy limits |
Negotiate survival periods by claim type. Define whether materiality applies only to the representation or also to damages. A materiality scrape can stop the seller from using the same threshold to defeat breach and reduce loss, but the provision must state exactly how it operates.
Buyer’s checklist: Schedule cyber, sanctions, FCPA, tax attributes, known disputes, and policy exclusions before accepting an RWI structure.
Tax Basis Allocation and Cross-Border Tax Traps
The tax step-up often attracts buyers to an asset deal. The buyer generally receives a basis equal to the purchase price allocated among acquired assets, including assumed liabilities, rather than the seller’s historic basis. That allocation influences future depreciation, amortization, later gain or loss, and the treatment of assumed obligations.
Under the IRS residual method, the allocation starts with Class I assets, proceeds through Classes II to VI, and assigns the residual amount to goodwill and going-concern value in Class VII, as stated in the IRS Form 8594 instructions. The agreement should establish the methodology and attach the allocation schedule at closing.
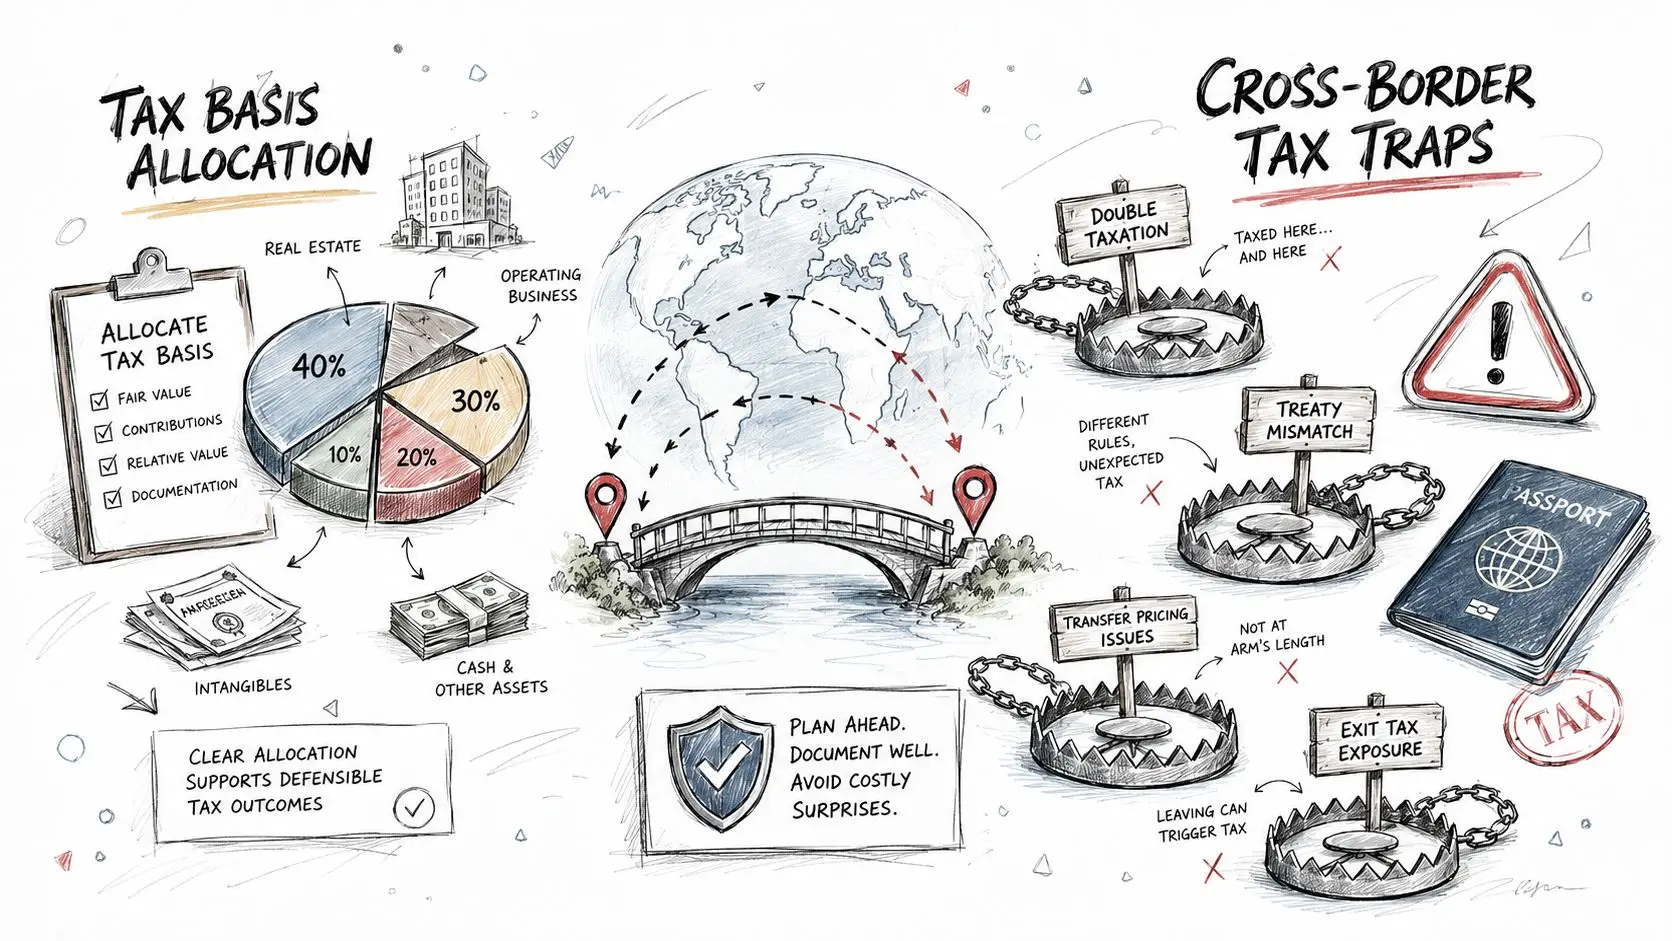
Allocation disputes create economic leakage
The buyer may prefer allocations that support faster deductions. The seller may prefer allocations that reduce immediate taxable gain or preserve favourable treatment. Both parties must also decide who prepares tax forms, who controls an audit, and whether later indemnity payments adjust purchase price.
A public agreement describes a post-closing allocation schedule consistent with U.S. tax rules and treats certain indemnity payments as purchase-price adjustments, which can alter the buyer’s basis retroactively (public asset purchase agreement). The APA should therefore require consistent reporting, dispute procedures, cooperation, and amendments when legally necessary.
Cross-border deals add Israeli withholding, VAT, transfer taxes, currency movements, intercompany debt, and seller-level tax analysis. The parties shouldn’t assume that a buyer’s basis benefit offsets the seller’s tax cost. Corporate sellers may face a double-taxation problem, especially where the asset sale occurs inside a corporate chain before proceeds reach shareholders.
A general comparison of property tax concepts, such as this resource on property capital gains tax in Australia, can help non-Israeli stakeholders understand why local tax analysis cannot rely on a single jurisdictional model. It doesn’t replace Israeli advice or transaction-specific treaty review.
Closing-date tax protocol
Before closing, the parties should:
- Agree on asset classes and valuation evidence.
- Assign responsibility for Form 8594 and local filings.
- Confirm withholding certificates and VAT treatment.
- Allocate transfer taxes and registration costs.
- Document currency conversion and intercompany debt treatment.
- Establish audit control and information-sharing rights.
- Align indemnity payments with purchase-price reporting.
The tax schedule belongs in the closing process, not in a later accounting exercise.
Regulatory Cross-Border and Israeli Practicalities
Signing an APA doesn’t complete the risk analysis. Cross-border buyers must screen the seller, beneficial owners, counterparties, banks, agents, and key suppliers against applicable sanctions regimes. The relevant review may involve U.S. restrictions, EU measures, UK rules, and Israeli compliance requirements.
Foreign investment review can also affect timing and conditions. A transaction may require analysis under the UK NSI Act, EU foreign subsidy rules, U.S. national-security review, or Israeli review through the Advisory Committee for the Examination of Foreign Investments. Even a non-binding review can disrupt a planned closing if the parties leave the process until signing.
Israeli employment transfer issues
Employment liabilities require more than a general employee schedule. The parties should identify whether employees transfer with the going concern, whether the seller terminates and the buyer rehires, and how continuity, severance, vacation, benefits, and pension obligations operate.
The Severance Pay Law and a Section 14 arrangement may affect the practical allocation, but the contract must still address the actual transition. One SEC-filed APA treated liabilities arising solely from termination of transferred employees at closing, including severance and paid time off, as assumed liabilities (SEC-filed agreement). That drafting choice demonstrates why employment assumptions need explicit wording.
Bulk-sale and enforcement mechanics
The parties may seek waivers of statutory bulk-transfer protections. One SEC-filed APA waived compliance with UCC bulk-transfer provisions and applicable state bulk-sale tax provisions (SEC-filed bulk-sale waiver). Israeli transactions require separate analysis of Tax Authority practice, creditor protection, tax certificates, and the consequences of transferring operating assets.
A practical sequence is straightforward:
- Screen parties and beneficial owners before signing.
- Map foreign-investment and antitrust filings.
- Obtain contract and licence consents.
- Confirm employee transition documents.
- Resolve tax certificates and bulk-sale issues.
- Choose governing law, forum, and judgment-enforcement strategy.
- Make closing conditional on every critical approval.
This sequence prevents the APA from becoming enforceable before the business can legally operate.
Common Pitfalls and Sample Clause Patterns
A recurring failure begins with a buyer paying for a business restriction that doesn’t protect the acquired goodwill. The APA may include a non-compete, yet the seller retains a related brand, customer list, domain, or operational dataset. The buyer then discovers that the restriction covers conduct, while the excluded assets preserve the competitive route.
A second failure leaves liabilities in the wrong schedule. The parties negotiate headline price but treat payroll, termination, tax, environmental, and contract claims as drafting details. The result can be a completed transfer with no practical recovery for a liability everyone discussed informally.
Patterns that deserve correction
De minimis and basket language: A buyer-friendly formulation should define the minimum claim size, aggregate threshold, treatment of related claims, and whether the basket applies to fundamental representations.
Tipping versus deductible basket: The agreement must state whether reaching the basket allows recovery from the first dollar or only above the threshold. Ambiguity creates a valuation dispute after the first claim.
Materiality scrape: A practical pattern removes materiality qualifiers when calculating damages, while preserving them for determining whether a representation was breached. The parties should also state whether the scrape applies to disclosure schedules.
Fundamental-representation walkaway: Title, authority, ownership, taxes, and capitalization often require separate caps, survival periods, or escrow treatment. The drafter shouldn’t place them under the same limitations as ordinary business representations.
Consent basket: Define which consents matter, who bears the cost, and whether failure to obtain one permits termination, price reduction, indemnity, or post-closing cooperation.
A buyer researching financing and acquisition mechanics may also consult this practical guide on how to purchase a small business. The legal point remains constant: financing assumptions must match the asset list, liability allocation, and closing conditions.
Closing preparation prevents avoidable disputes
The parties should circulate a single closing checklist. It should identify each transferred asset, required signature, lien release, consent, tax certificate, employee document, payment instruction, and post-closing deliverable.
The checklist should also reconcile the APA against every schedule. A missing login, customer consent, IP assignment, or original record can undermine an otherwise completed transaction. The drafter should resolve discrepancies before the funds move, not through an indemnity claim after operations begin.
Next Steps and Retaining Counsel
An APA needs an operating plan immediately after signing. Confirm that counsel’s engagement covers diligence, tax coordination, regulatory filings, closing, and post-closing administration, then assign decision authority for each workstream.
The transaction team should:
- Clear conflicts and confirm who may approve changes.
- Adopt one closing checklist and responsibility matrix.
- List outstanding consents, filings, and third-party deliverables.
- Freeze schedule changes through controlled versioning.
- Assign responsibility for tax elections and allocation filings.
- Set the escrow and indemnity-claim process.
- Escalate employment, IP, sanctions, and environmental issues early.
Incomplete schedules, delayed consents, undefined accounting methodology, or inconsistent foreign-law advice indicate that the deal requires escalation. Further drafting alone will not cure an ownership or execution problem.
For an Israeli-led transaction, one negotiation owner should coordinate Israeli counsel, foreign advisers, tax specialists, regulatory counsel, and the commercial team. The owner should record which adviser controls each issue and reconcile conflicting positions before they reach the client or counterparty.
RNC Group handles international commercial transactions, M&A structuring, cross-border coordination, and legal risk management, including coordination between Israeli and foreign advisers and preparation of transaction documents.
If you are structuring a cross-border asset purchase, engage counsel experienced in Israeli and international commercial law to review liability allocation, tax coordination, and closing execution. This article provides general information only and does not constitute legal, tax, accounting, or regulatory advice. Obtain qualified professional advice before relying on it.