
Most CEOs still treat deal structure as a drafting issue. In 2026, that assumption can destroy value before diligence even starts, because the wrong structure locks in tax leakage, consent friction, and inherited risk that no elegant purchase agreement can fully reverse.
The evidence is already clear. According to marketplace transaction analysis, stock sales make up about 30% of all deals, and larger companies are much more likely to use them, while sellers often accept 10% to 20% lower pricing in stock deals to reflect inherited liabilities (Website Closers on asset purchase vs stock purchase acquisition structures). That pattern matters because it shows a hard commercial truth. Structure isn’t paperwork. Structure is price, risk, speed, and post-close survivability.
The M&A Crossroads Choosing Your Path in 2026
A buyer can overpay in an asset deal and still recover value through tax treatment. A buyer can also negotiate an attractive headline price in a stock deal and inherit a historical problem that consumes management attention for years.
That is why the asset purchase vs stock purchase decision belongs at the start of the transaction, not at the end. Boards often focus first on valuation, exclusivity, and financing. However, the more disciplined approach starts with one sharper question: What exactly should transfer, and what must stay behind?
For Israeli companies entering the U.S. or Europe, that question becomes more acute. Cross-border acquisitions often involve local licensing regimes, customer contracts with change-of-control provisions, intellectual property chains of title, employee migration issues, and tax leakage across more than one jurisdiction. A structure that looks efficient in a term sheet can become unworkable once local counsel maps the approvals.
Why the common instinct fails
Many management teams assume an asset purchase is always safer because it lets the buyer choose assets and selected liabilities. That is only partly right.
An asset deal often gives better liability control. Yet it can also trigger contract reassignments, permit transfers, title work, payroll changes, and operational breakpoints that a stock deal largely avoids. The legal win can become an integration loss.
By contrast, many sellers assume a stock deal is always the clean exit. Sometimes it is. Yet a stock sale can stall when the buyer’s diligence uncovers unresolved tax, employment, regulatory, or litigation exposure buried inside the entity.
Board-level rule: The first structure discussion should happen before the first valuation discussion, because structure changes what the business is worth to each side.
The issue also matters for founders preparing for selling a business. A company built for a future stock sale looks different from a company that can only be sold through an asset carve-out. Clean entity records, assignable contracts, defensible IP ownership, and liability hygiene all expand strategic options.
What high-stakes buyers get right
Strategic buyers don’t ask which structure is more common. They ask which structure best protects continuity, preserves strategic advantage, and captures value after closing.
They also test second-order effects early:
- Regulatory continuity: Will licenses stay in place through closing?
- Contract transferability: Will key revenue contracts require consent?
- Tax economics: Does the buyer need a basis step-up?
- Liability perimeter: Which known and unknown risks can remain with the seller?
- Integration reality: Can the business keep operating on day one?
That is the critical crossroads in asset purchase vs stock purchase analysis. Once the parties choose the path, many later outcomes become predictable.
Understanding the Fundamental Difference in Deal Structures
The legal form of the acquisition determines what the buyer owns on day one, what risk stays behind, and how much hidden work the business must absorb before and after closing.
A stock purchase transfers the target company itself. The buyer acquires the shares, takes control of the entity, and inherits the full operating platform inside it, including contracts, employees, permits, compliance history, and liabilities that diligence may or may not uncover.
An asset purchase transfers a defined package of business assets and selected liabilities. Everything else remains with the selling entity unless the purchase agreement moves it expressly.
That sounds simple. In practice, it changes almost every execution decision.
Buy continuity or build a clean perimeter
In a stock deal, the legal shell stays intact. That usually protects commercial continuity because customers, vendors, and employees continue dealing with the same entity. It also means the buyer spends more time testing what sits inside that entity, including tax exposures, misclassified workers, open-source software issues, sanctions screening failures, and historical data privacy problems.
In an asset deal, the buyer can draw a tighter liability perimeter. The cost is operational friction. Contracts may need assignment. Bank accounts, payroll arrangements, leases, and local registrations may need to be rebuilt or transferred one by one. In cross-border deals involving Israeli targets, that friction can be severe when key IP was developed through founders, contractors, or service companies and the paperwork does not line up cleanly with the entity selling the assets.
| Issue | Asset purchase | Stock purchase |
|---|---|---|
| What transfers | Selected assets and agreed liabilities | Entire entity through share transfer |
| Liability profile | Buyer can limit assumed liabilities | Buyer inherits liabilities inside the company |
| Contract continuity | Assignments and third-party consents are often required | Contracts often remain with the same entity, subject to change-of-control terms |
| Licensing and permits | Transfer, re-issuance, or new filings may be required | Often stay with the entity, but regulators may still review control changes |
| Employee transition | Workforce may need new offers, benefit alignment, and local onboarding steps | Employees usually remain employed by the same entity |
| Day-one operations | Cleaner risk selection, heavier implementation burden | Faster continuity, heavier diligence and indemnity pressure |
The real dividing line is execution risk
Buyers often describe stock purchases as simpler. The documents can be simpler. The integration is not always simpler.
If the target has weak records, a stock deal can force the buyer to solve old problems inside a live company while revenue must keep flowing. If the deal is cross-border, those problems multiply. A U.S. or European buyer acquiring an Israeli company through shares may preserve customer contracts and employee continuity, but it also acquires the target’s legacy compliance posture, local tax file history, and corporate housekeeping gaps.
Asset deals reverse that equation. They let the buyer leave more history behind, but they create a transfer project. That project can miss assets the business needs. I have seen deals delayed because source code repositories, domain names, government grants, customer data sets, or Israeli Innovation Authority related rights were not mapped correctly at signing. Those are not drafting footnotes. They affect whether the business can operate legally and commercially after closing.
A useful reference point is the IRS treatment of gain reporting in equity transactions, including these IRS Schedule D instructions for capital gains. The form itself does not choose the structure, but it underscores a broader point. Share sales and asset transfers produce different consequences because they are legally different transactions, not cosmetic variations of the same deal.
Immediate consequences after signing
In an asset purchase, counsel builds the business from a transfer list. Every omitted contract, permit, software license, or receivable creates a closing issue or a post-closing dispute. Precision matters more than elegance.
In a stock purchase, the legal transfer is broader and the diligence burden is deeper. The buyer must get comfortable that the company owns what it claims to own, has authority to operate where it operates, and will not hand the acquirer a liability problem six months after closing.
A stock purchase protects continuity inside the existing entity. An asset purchase protects selectivity by forcing the parties to define what moves.
What CEOs should understand early
This choice is not a drafting preference. It is a decision about where the deal will absorb cost, delay, and risk.
A buyer that values uninterrupted operations, regulated continuity, and customer retention may accept the broader risk envelope of a stock purchase and price that risk through diligence, indemnities, escrows, and, in some cases, representation and warranty insurance. A buyer that sees unclear IP ownership, uneven compliance controls, or unresolved legacy exposure should usually start with an asset structure and test whether the business can be transferred without damaging value.
That is the fundamental difference. One structure preserves the company. The other rebuilds the business in a cleaner frame.
The Tax Implications Driving Deal Value
Tax sets the price of this deal long before the purchase agreement is signed.
Buyers and sellers rarely fight over structure in the abstract. They are fighting over after-tax value, timing of cash recovery, and who bears the hidden cost of getting the transaction integrated across jurisdictions. In cross-border deals involving Israeli buyers or founders, that analysis gets harder fast. The legal form chosen at signing can affect not only deductions, but also withholding, repatriation planning, purchase price allocation work, and the cost of cleaning up the structure after closing.
Why buyers often push for asset treatment
An asset purchase usually gives the buyer a new tax basis in the acquired assets. That matters because the buyer can often recover part of the purchase price through future depreciation and amortization deductions, including on goodwill and other Section 197 intangibles. As DeWitt LLP notes in its overview of asset purchase versus stock purchase tax treatment, that basis step-up is often one of the main economic reasons buyers prefer asset treatment.
Discerning buyers do not stop at the headline benefit. They ask a harder question. How much of that tax value will be realized after closing, in what jurisdiction, and over what period? A buyer with losses, limits on deductibility, or a post-closing integration that moves functions outside the original tax footprint may not get the full benefit that looked attractive in the model.
That is where standard deal charts often fail CEOs. They compare asset deal versus stock deal tax outcomes at signing, but they do not price the administrative burden of implementing the tax structure. In a U.S.-Israel transaction, that burden can include transfer pricing updates, intercompany licensing changes, payroll and employee equity treatment, indirect tax review, and alignment between tax elections and financial reporting. Those costs can erode part of the buyer’s expected gain from the basis step-up.
Why sellers usually resist
Sellers often prefer a stock sale because it is cleaner from their side and can produce a better after-tax result. In many cases, especially where a corporation is selling assets and then distributing proceeds, the seller faces tax at the entity level and then again when cash moves to the owners. That result is one reason sellers push hard for stock treatment and often treat an asset structure as a price issue, not just a legal issue.
This point matters in founder-led exits. A founder may hear that the buyer is offering the same nominal price under either structure and assume the economics are equivalent. They are not. If the seller’s tax bill is materially worse in an asset deal, the seller is funding part of the buyer’s post-closing tax benefit unless price is adjusted.
The practical negotiation is usually straightforward:
- The buyer wants basis step-up and the cash tax benefit that may follow.
- The seller wants a structure that preserves more net proceeds at closing.
- The pricing discussion becomes a tax-sharing exercise, whether the parties admit it or not.
Cross-border tax friction changes the answer
Cross-border deals expose a second layer of cost that domestic comparisons miss. Israeli acquirers buying a U.S. business often focus first on whether they can get a basis step-up. They should also model how the structure affects cash extraction, withholding exposure, financing flows, and the compliance cost of operating the target inside the group after closing.
A stock deal may look less attractive on paper because the basis does not reset. Yet it may preserve permits, accounting history, tax attributes, and commercial continuity in a way that avoids expensive post-close remediation. An asset deal may improve future deductions but create registration work, transfer taxes, consent requirements, and restructuring steps that consume management time during the first hundred days. Those second-order effects regularly decide whether the tax thesis survives contact with operations.
One more point gets missed too often. The tax result is not always dictated by the legal form alone. In some transactions, elections can produce share sale mechanics with asset sale tax treatment. That can be an elegant outcome, but only where the entities, jurisdictions, and ownership history support it. It is a tool, not a default answer.
Practical warning: If the tax model appears after the letter of intent, the parties are usually negotiating price with only part of the economics on the table.
What CEOs should require before price terms harden
A serious structure model should answer four questions before exclusivity locks in expectations:
- What deductions or amortization benefits does the buyer expect to use, and when?
- What is the seller’s net after-tax outcome under each structure?
- What implementation costs sit outside the headline tax model, including transfer work, elections, filings, and integration changes?
- Which structure produces the best after-tax result after adding execution cost and delay risk, not before?
For sellers reviewing gain treatment, a practical primer such as the IRS Schedule D instructions for capital gains can help management understand the core tax vocabulary before negotiations become positional.
What usually works in practice
The strongest outcomes come from pricing the tax asymmetry directly. If the buyer expects meaningful future tax savings from an asset deal, part of that value should be reflected in price. If the seller insists on stock treatment, the buyer should assess whether the lost tax benefit is offset by lower execution cost, faster closing, cleaner continuity, or a reduced need for post-closing restructuring.
Tax does not merely influence deal value. In many cross-border acquisitions, it determines whether the value model was real in the first place.
Allocating Legal Liability and Business Risk
Most failed acquisition logic starts with optimism about what was bought. Strong buyers think first about what they might be inheriting.
A stock purchase places the buyer inside the target’s legal history. The entity remains the same, so the liabilities remain there too. Some are visible in financial statements and dispute schedules. Others are contingent, undisclosed, or misunderstood until after closing.
What follows the entity in a stock deal
In a stock purchase, the buyer usually takes the company with all of its legal baggage. That can include tax exposures, employment claims, regulatory non-compliance, environmental issues, customer disputes, and historical conduct that did not appear material during diligence.
That doesn’t mean stock deals are reckless. It means stock deals require a different protection architecture.
The legal team typically responds through:
- Expanded diligence: The buyer investigates the target’s history, controls, contracts, filings, and known risk areas.
- Representations and warranties: The seller confirms defined facts about the business.
- Indemnities: The seller agrees to bear specified losses if certain liabilities emerge.
- Escrow or holdback arrangements: Part of the purchase price remains available to satisfy post-closing claims.
None of those tools fully recreates the protection that structural isolation can provide. They only shift the economic burden after the problem appears.
Why asset deals often feel safer
An asset purchase lets the buyer specify which liabilities it assumes. That is a powerful tool when the target has uneven compliance, legacy disputes, or unclear historical records.
The value lies in selectivity. The buyer can acquire the machinery, customer base, intellectual property, and inventory, while leaving behind liabilities that don’t support future operations.
That said, lawyers should never present asset deals as impenetrable shields. Courts and regulators can still impose liability in certain settings, especially where the transaction resembles a disguised continuation of the seller’s business, or where statutory obligations follow the business activity.
Cross-border risk gets more complicated
Israeli and European cross-border transactions add another layer. Local employment protections, consumer rules, tax enforcement, and regulatory doctrines may affect whether a buyer can leave liabilities behind.
The legal answer depends on jurisdiction, sector, and transaction facts. A buyer acquiring a regulated activity, a public-facing brand, or a business with product exposure should assume that formal structure alone won’t eliminate every successor risk.
If the target operates in a litigious or regulated sector, liability allocation should drive structure, not the other way around.
What effective diligence looks like
Risk allocation becomes practical only when diligence is built around the chosen structure.
For a stock transaction, the most important diligence questions are often historical:
| Diligence area | Core question in a stock purchase |
|---|---|
| Tax | Did the company comply in every relevant period and jurisdiction? |
| Employment | Are there unpaid obligations, misclassification risks, or disputes? |
| Regulatory | Did the business operate with all required approvals and filings? |
| Litigation | Are there pending, threatened, or latent claims? |
| IP and data | Does the company actually own and lawfully use what it relies on? |
For an asset transaction, diligence shifts toward transferability and perimeter control. The buyer must confirm ownership, lien status, assignability, title, and whether key operating rights can move without interruption.
The decision standard
The cleanest practical rule is this. If the target’s value lies mainly in transferable assets and customer relationships that can be migrated, an asset purchase often offers better risk containment. If the target’s value lies in entity-level continuity, licenses, and contracts that resist transfer, a stock purchase may be necessary, but the buyer must price and paper the risk with discipline.
In asset purchase vs stock purchase analysis, legal risk is never abstract. It either stays with the seller, or it becomes the buyer’s problem after closing.
Navigating Operational Continuity and Hidden Costs
The tax model may favor an asset purchase. The operating model may punish it.
That is where many transaction teams get blindsided. They compare tax savings against purchase price, but they fail to price the administrative and commercial friction required to move a living business from one legal shell to another.
The continuity advantage of stock deals
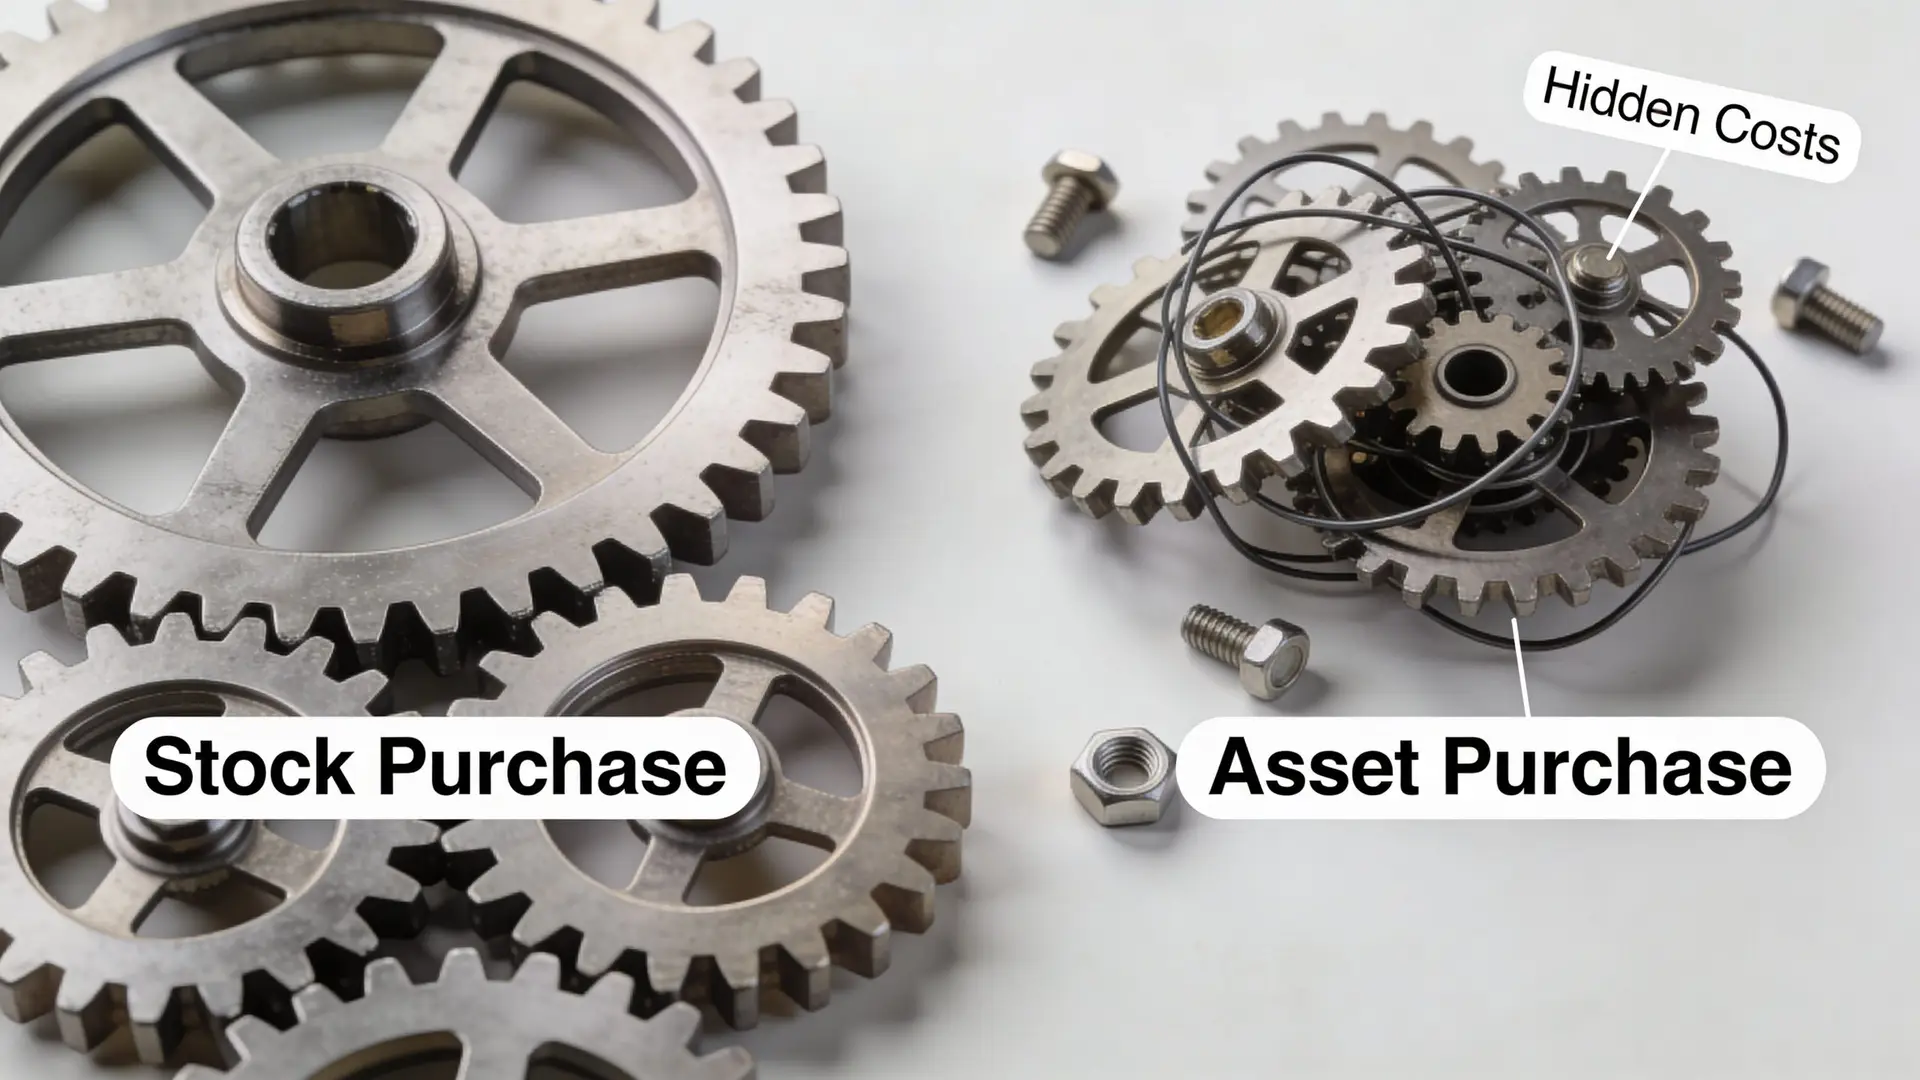
A stock purchase usually preserves the business on day one. The same entity continues to hold contracts, employ staff, use licenses, and interact with customers and vendors.
That continuity has real strategic value. Customers don’t like consent requests. Regulators don’t like rushed transfer filings. Employees don’t like uncertainty about payroll, benefits, and employer identity.
The hidden cost trap in asset deals
Asset purchases require movement. Contracts may need assignment. Assets may need retitling. Leases may require landlord approval. Intellectual property assignments may need recordation. Employees may need transfer planning under local law.
The critical gap in standard commentary is quantification. Melcap notes that the tax benefits of an asset purchase can be eroded by hidden operational costs, and gives a practical example: a trucking company with 2,000 vehicles may find that retitling costs exceed the tax savings, making a stock deal operationally superior despite its tax disadvantages (Melcap on hidden retitling and contract transfer costs).
That example matters because it captures the second-order effect. A theoretically superior structure can become inferior once execution costs are accurately counted.
Where operational friction usually appears
The most common pressure points are not exotic:
- Customer contracts: Anti-assignment clauses can hand bargaining power to counterparties at the worst possible moment.
- Supplier arrangements: Critical vendors may slow-walk approvals or demand revised terms.
- Real estate: Leases, land registrations, and security packages can delay transfer.
- Employees: Transfer mechanics differ sharply by jurisdiction, especially in Europe.
- Licenses and permits: Some approvals follow the entity. Others do not.
- Systems integration: Banking mandates, invoicing details, procurement records, and ERP mappings may all require change.
The best asset deals are not the ones with the largest tax step-up. They are the ones that can actually be implemented without breaking the business.
A workable decision filter
Before choosing an asset structure, management should force an operational transfer memo that answers three questions:
- Which contracts require consent?
- Which assets require title work or registration changes?
- Which people, permits, and systems cannot move cleanly by closing?
If the list is short and manageable, an asset deal may still outperform. If the list runs through revenue-critical contracts, regulated permits, and high-volume retitling tasks, the stock option often deserves renewed attention.
Asset purchase vs stock purchase isn’t decided by legal doctrine alone. The winning structure is the one that survives contact with operations.
Valuation and Negotiation in Cross-Border Deals
Valuation doesn’t exist in a vacuum. Structure changes what the target is worth to the buyer and what the seller can keep.
That is why two bids for the same company can both be rational and still differ sharply. One bidder values continuity and accepts entity-level risk. Another bidder values a tax basis reset and insists on selective liability assumption. The headline number alone tells very little.
Structure changes the economics
According to investor modeling summarized by Ascot International, the choice between an asset and stock purchase can produce 20% to 40% higher internal rate of return over 5 to 7 years. The same analysis states that asset purchases can generate annual tax shields averaging 5% to 10% of deal value through fair market value basis reset, accelerated depreciation, and 15-year goodwill amortization (Ascot International on IRR and NPV effects of deal structure).
For negotiation purposes, that means a buyer may legitimately pay more in an asset deal because the post-close economics are better. It also means a seller demanding a stock deal cannot ignore the buyer’s inherited risk profile.
Cross-border deals amplify the pricing tension
In Israeli outbound acquisitions, the structure question often affects more than tax. It influences financing, approval pathways, operational launch timing, and local counsel cost.
A buyer entering a foreign regulated market may accept a stock structure to preserve licenses and customer continuity. Another buyer may insist on assets because the target’s legal history is too opaque. Both positions can be correct depending on the target.
What strong negotiators actually trade
Experienced parties don’t reduce the debate to “asset versus stock.” They trade specific economic burdens.
A practical negotiation map usually includes:
| Negotiation issue | Buyer position | Seller position |
|---|---|---|
| Tax benefit | Buyer seeks to retain basis step-up value | Seller seeks sharing through higher price |
| Legacy liabilities | Buyer discounts value for inherited risk | Seller argues risks are remote or covered by indemnity |
| Closing certainty | Buyer may prefer stock for continuity | Seller may resist complex carve-out mechanics |
| Post-closing claims | Buyer wants escrow and survival protection | Seller wants cleaner release and lower holdbacks |
The Israeli perspective on leverage
Israeli buyers often bring strong execution discipline to cross-border deals, but they can still lose negotiating advantage by treating structure as a legal annex rather than a negotiation engine.
The better approach is to quantify every structural consequence in a commercial memo before the first draft agreement. That memo should connect tax, liability, operational transfer burden, and jurisdiction-specific approvals to the purchase price mechanism.
This matters especially in multi-jurisdiction deals. A stock acquisition can look simple until local counsel identifies consent rights, change-of-control triggers, or hidden compliance defects inside the entity. An asset deal can look defensive until the transfer map shows dozens of commercial dependencies that cannot be replicated quickly.
Price is the visible term. Structure is the invisible model underneath it.
What usually wins the negotiation
The strongest position usually belongs to the party that can quantify consequences better than the other side.
For buyers, that means showing exactly why inherited liabilities, missing basis step-up, or consent risk affects value. For sellers, it means proving that continuity, regulatory stability, and transition simplicity justify either a stock structure or a pricing adjustment.
In asset purchase vs stock purchase negotiations, the best argument is rarely doctrinal. It is mathematical, operational, and credible.
Making the Strategic Choice A Dealmaker’s Guide
There is no universally superior structure. There is only the structure that best matches the target, the sector, the jurisdiction, and the parties’ risk tolerance.
The recommended strategic path is to decide by hierarchy. First, protect continuity if the business cannot survive transfer friction. Second, isolate liabilities if the target’s history cannot be trusted. Third, optimize price through tax and negotiation once the first two issues are clear.
When an asset purchase usually makes sense
An asset purchase often fits best when the buyer wants a controlled perimeter.
That is usually the better path when:
- Historical risk is uneven: The target has unresolved legal, tax, compliance, or environmental concerns.
- The buyer wants only part of the business: A division, product line, IP portfolio, or customer segment can be carved out.
- Transferability is manageable: Key contracts and permits can move without crippling the deal.
- The buyer values future deductions: The tax profile materially improves post-close economics.
When a stock purchase usually makes sense
A stock purchase often fits best when continuity is worth more than selectivity.
That is usually the better path when:
- Licenses and permits sit at entity level: Re-application risk is too high.
- Customer relationships depend on uninterrupted operation: Assignment requests could damage revenue.
- The target is operationally dense: The business has too many contracts, registrations, or assets to transfer efficiently.
- The seller has an advantageous position: Clean records and strong performance let the seller demand share sale treatment.
Buyer checklist for risk mitigation
- Map the liability perimeter. Identify what can remain with the seller and what will likely follow the business anyway.
- Build a transfer matrix. List contracts, permits, IP, employees, leases, and regulated assets that must move.
- Run side-by-side tax models. Compare stock and asset outcomes before finalizing price.
- Stress-test continuity. Ask whether the business can operate normally the morning after closing.
- Draft for failure points. Include indemnities, conditions precedent, escrows, and post-close covenants that match the chosen structure.
Seller checklist for value protection
- Clean the entity records: Share registers, board approvals, tax filings, and IP ownership should be internally consistent.
- Review assignment restrictions: A seller who knows which contracts can move holds more influence in structure talks.
- Prepare a tax narrative: Management should understand why a stock sale is preferable, and what price adjustment could justify asset treatment.
- Segment non-core assets early: If a carve-out may be necessary, define it before negotiations force rushed decisions.
- Anticipate buyer diligence themes: Tax, compliance, employment, and disputes should be organized before the data room opens.
The final decision test
The best final question is simple. Which structure preserves the most enterprise value after accounting for tax, legal risk, execution cost, and post-close continuity?
If the answer is uncertain, the parties should not rush to paper. They should force the comparison until the trade-offs are explicit.
That discipline is what separates a completed deal from a successful one.
For companies handling high-stakes cross-border acquisitions, restructurings, or disputes connected to Israel, the recommended next step is to obtain structure-first legal analysis before price and documentation harden. RNC Group advises on international M&A, commercial risk allocation, and cross-border execution strategies where tax, liability, and operational continuity must be aligned from the outset.
Disclaimer: The information provided in this article constitutes a general strategic analysis and does not constitute binding legal, tax, or business advice. Every M&A transaction requires a specific examination of the circumstances, applicable law, and tax implications by qualified professionals. Reliance on this content is solely at the user’s risk.