
A commercial lease in 2026 is not a rent form. It is a risk machine. The most dangerous advice is still the simplest, sign the headline rent, trust the broker, and read the rest later.
That approach fails because commercial leases are built around a lease-by-lease financial review, not a single number on page one. Analysts track the expiration date, the current rental rate, the rental growth rate, and the share of operating expenses paid by the tenant when they estimate income, because rent is usually a stack of base rent, escalations, and sometimes percentage rent in retail deals (Texas A&M Real Estate Center PDF). So the right question is not “What is the rent?” It is “Which clause changes cash, and which clause changes control?”
Why Reading a Commercial Lease Backwards Costs Money
Most foreign tenants start with the rent line and end with surprises. That is backward. A commercial lease usually contains at least seven clause families that decide exposure, rent stack, term and exit, transfer rights, maintenance, indemnities, default, and fit-out or handback.
Practical rule: Read every clause as either a cost lever or a control lever. If you cannot name which one it is, the clause is probably dangerous.
The reason is simple. A lease can look stable while hidden pass-throughs, repair covenants, and exit restrictions eat cash for years. Commercial leases are also multi-year commitments, not one-year residential arrangements. In U.S. market data cited in an industry guide, the average office lease term was about 8 years in Q3 2023, prime office buildings averaged 107 months from 2021 to 2024, and non-prime buildings averaged 86 months (Nomad Group). That duration exists because fit-outs, tenant improvements, and occupancy recovery take time.
A smarter reading order
Start with the clauses that can trap the business, not the clauses that merely describe the space. A useful sequence is use rights, exit rights, transfer rights, repair liability, handback, rent stack, and only then boilerplate.
- Use rights first. A narrow permitted-use clause can kill pivots and franchise rollouts.
- Exit rights second. Breaks, renewal mechanics, and holdover terms decide whether the tenant can escape.
- Transfer rights third. Assignment and subletting show whether the lease is a business asset or a cage.
- Cost clauses fourth. Base rent matters, but pass-throughs, escalations, and reconciliations matter more.
- Physical obligations last. Repairs, fit-out, and make-good language often hide the largest end-of-term bill.
For a plain-English comparison of how commercial clauses affect operating control, a useful outside reference is Bryan Fagan PLLC lease help. The point is not to admire the formatting. The point is to map each sentence to cash or influence before the signature lands.
The Rent Stack Base Rent Step Ups CAMs and Service Charges
Commercial rent is rarely just rent. It is usually base rent plus escalations, plus operating expenses, plus service charges, and sometimes percentage rent in retail leases. That is why a tenant can accept what looks like a reasonable headline number and still end up with an expensive building.
The legal drafting matters because occupancy cost is a stack of charges, not a single line item. Market guidance for U.S. and major-market leases highlights base rent plus CAM, taxes, insurance, utilities, repairs, and reconciliation mechanics, and it warns that uncapped pass-throughs can materially raise the effective cost (AILawyer commercial lease terms guide). In NNN structures, the tenant can bear nearly all property expenses. That structure demands skepticism, not optimism.
A landlord can also shift cost through the definition of rentable versus usable square feet, gross-up formulas, and reconciliation language. Even when the nominal rent stays fixed, the occupancy cost can rise if the tenant pays for common-area inefficiency or vague management charges. That is why practitioners benchmark the all-in rent, not the face rent.
| Component | What It Covers | Typical Tenant Exposure | Negotiation Lever |
|---|---|---|---|
| Base rent | Core payment for the space | Predictable but often stepped up | Cap escalations and tie changes to clear formulas |
| CAM or service charges | Shared area costs and building operations | Can rise through reconciliation | Add audit rights and expense caps |
| Taxes and insurance | Property tax and insurance pass-throughs | Often passed through in net deals | Define exclusions and allocation rules |
| Utilities and repairs | Operating consumption and routine fixes | Can become broad and open-ended | Narrow the repair and utility scope |
| Percentage rent | Extra rent above a revenue threshold | Relevant in retail deals | Set the threshold and reporting mechanics |
For a deeper grounding in net structures, a useful reference point is guide to NNN investing. The commercial lesson is blunt: never negotiate only the headline rent when the service-charge language can move the actual number far more.
What to insist on
- Caps on pass-throughs. If the lease leaves operating expenses uncapped, the tenant inherits the landlord’s inefficiency.
- Audit rights. If CAM reconciliations are opaque, the tenant should get backup documents and review rights.
- Square-foot clarity. Rentable and usable area must be defined with precision, or the tenant may pay for space it never uses.
A stable face rent is not a stable lease. A disciplined tenant prices the whole stack, then negotiates the stack, not just the label on top.
Term Renewal Options and Break Clauses as Decision Tools
Lease term is strategy, not calendar math. A short nominal term with real break rights can function like a much shorter commitment than the headline suggests. A long term without exits can trap a company in a bad location long after the market, or the business, has changed.
Commercial lease duration also reflects economics. Multi-year terms let landlords recover fit-outs and tenant improvements over time, and they let both sides spread risk across occupancy and cost recovery. That is why long leases are common in office markets, while short or flexible terms often hide behind renewal and break mechanics.
Test the renewal option, not the marketing pitch
A renewal option is only useful if the rent formula is locked. If the renewal rent is fixed or indexed, the tenant has a real right. If it is left to later negotiation, the option is a courtesy note dressed up as protection.
A renewal notice date is the critical trigger. Miss it, and the tenant often loses negotiating power before any renegotiation starts.
Renewal notice mechanics matter because they usually decide when the tenant must choose between staying and relocating. In practice, the notice window often falls months before expiry, so the business has to plan well ahead. The lease should be tested against the company’s expansion plan, fit-out payback, franchise rollout timeline, and personal guarantee exposure before signature. That is the point where renewal language stops being a legal detail and starts being a cost-control term, especially once VAT treatment, Arnona exposure, and guarantee practice are in the mix.
A simple business-horizon test
- Short operating horizon. Use a shorter lease or a real break clause.
- Expansion horizon. Avoid permits and transfer rights that block new formats or branch changes.
- Fit-out payback horizon. Match the lease length to the time needed to recover build-out cost.
- Owner-risk horizon. If a personal guarantee is on the table, shorten exposure or narrow the guarantee.
A renewal right only helps if the tenant can exercise it without drama. A break clause only helps if the notice period, exit conditions, and any break fee are clean. Anything else is a trap.
Assignment Subletting and the Control Traps Foreign Tenants Miss
Transfer rights decide whether the lease can adapt when the business changes. That is why assignment and subletting deserve more attention than they usually get. A tenant that cannot transfer space, restructure occupancy, or bring in a subtenant owns a liability, not an asset.
Assignment transfers the tenant’s rights and obligations to another party. Subletting leaves the original tenant in place and adds another occupant below it. Those two tools look similar in conversation, but the legal effect is very different. A lease that allows one and forbids the other can still be restrictive if landlord consent sits entirely in the landlord’s discretion.
The hidden veto
Permitted-use language can block business-model changes long before transfer rights become relevant. A franchise group may want to rotate formats. A SaaS company may want a client-facing showroom. A co-working operator may want flexible occupancy. A narrow use clause can stop all of it.
Control rule: If the landlord can withhold consent for any reason, the tenant does not really have a transfer right.
Foreign tenants should check three things before signing. First, whether landlord consent can be unreasonably withheld, delayed, or conditioned. Second, whether the landlord’s recapture right is mutual. Third, whether a change of control in the tenant entity triggers a transfer default.
| Issue | Western-style expectation | Risk in tighter practice |
|---|---|---|
| Consent standard | Consent not unreasonably withheld | Broad landlord discretion |
| Recapture right | Limited and mutual | Can let landlord take the site back |
| Change of control | Usually treated as corporate housekeeping | Can trigger default or re-approval |
A lease that blocks assignment but allows the landlord to recapture may look balanced on paper and lopsided in reality. The tenant then pays for flexibility it never receives. That is especially dangerous for cross-border groups with parent guarantees or rolling entity changes.
The draft should also protect business-model changes without landlord veto. If the company plans future pivots, the lease should say so in plain language. If the landlord wants approval rights, those rights need objective standards, not open-ended discretion.
Maintenance Fit Out and Handback Liability
Maintenance language often looks boring. It is not. It is one of the cleanest ways for a landlord to push structural risk onto the tenant without changing the rent line at all.
A lease may be full repairing, internal-repairs-only, or effectively handed over as-is. The difference matters. A broad repair covenant can sweep HVAC, plumbing, and even roof risk into the tenant’s cost base. That is expensive, and it is usually hidden behind tidy drafting.
Fit-out approval can stop the opening clock
The fit-out clause is not just about aesthetics. It controls landlord approval for plans, contractors, working hours, insurance, and bonding. If the landlord drags its feet, the tenant can lose time, delay opening, and burn cash before the business earns a cent.
Handback or make-good liability is where many foreign tenants get hurt. The lease may require the tenant to remove improvements, repaint, reinstate demising walls, or restore the premises to base building condition. Those obligations can become a large end-of-term project if nobody scopes them early.
A tenant should scope handback obligations 18 to 24 months before exit, not in the final month.
For a useful external benchmark on inspection discipline, a practical reference is guide to rental property checks. The inspection habit matters because it helps the tenant separate normal wear from restoration liability before the landlord turns every item into a dispute.
A handback checklist that actually helps
- Survey existing alterations. Identify what must stay and what can be removed.
- Check reinstatement duties. Look for demising walls, ceilings, flooring, and cabling.
- Test approval language. See whether landlord consent is objective or discretionary.
- Review insurance and bonding. Make sure the fit-out process does not create extra financial exposure.
- Plan the exit early. Build a restoration budget before the final year begins.
The business should never treat fit-out as a one-time construction problem. It is a lease issue from day one. If the tenant ignores that, the landlord usually wins twice, first on approval delay and then on handback cost.
Indemnities Guarantees Default and Termination Rights
Risk allocation becomes real in the indemnity, guarantee, and default clauses. These provisions tie the whole lease together. If they are broad, they can turn a manageable breach into a company-threatening event.
Indemnity language often reaches beyond direct damage and into third-party claims, insurance gaps, and landlord losses. That matters because an insurance policy limit is not the same thing as a contractual ceiling. If the lease promise is broader than the policy, the tenant can still face uncovered exposure.
A personal guarantee in Israel often goes further than many foreign tenants expect. It can extend to the lease’s obligations, not just rent. That means repairs, make-good, and other charges can follow the individual signer. Cross-default language can also drag in related guarantees, parent-company debt, and even other property holdings.
Default clauses need a hard reading
Monetary defaults usually carry a cure period, often in the 14 to 30 day range. Non-monetary defaults usually take longer. But the practical question is whether the cure period is real or just cosmetic. If the landlord can accelerate obligations, re-enter the premises, or seize goods quickly, the tenant has very little room to fix anything.
The landlord’s remedies can also be more aggressive than many Western tenants expect. In Israel, distraint can allow a landlord to seize tenant goods on the premises for unpaid rent. That changes negotiation power at the drafting table because default is not only a contract question, it is an operational threat.
Red flags to isolate before signature
- Cure periods that are too short. A brief cure window can create a technical default trap.
- Uncapped indemnities. These can outgrow insurance and bank guarantees.
- Cross-default language. One problem can spread across other credit lines or entities.
- Termination asymmetry. If the landlord has convenience rights and the tenant does not, the lease is one-sided.
- Waiver language. Boilerplate waivers can foreclose remedies the tenant would expect elsewhere.
The best lease review assumes the landlord will enforce every contractual advantage. That is not pessimism. It is discipline.
The Israel Overlay VAT Arnona Guarantees and the Strategic Path
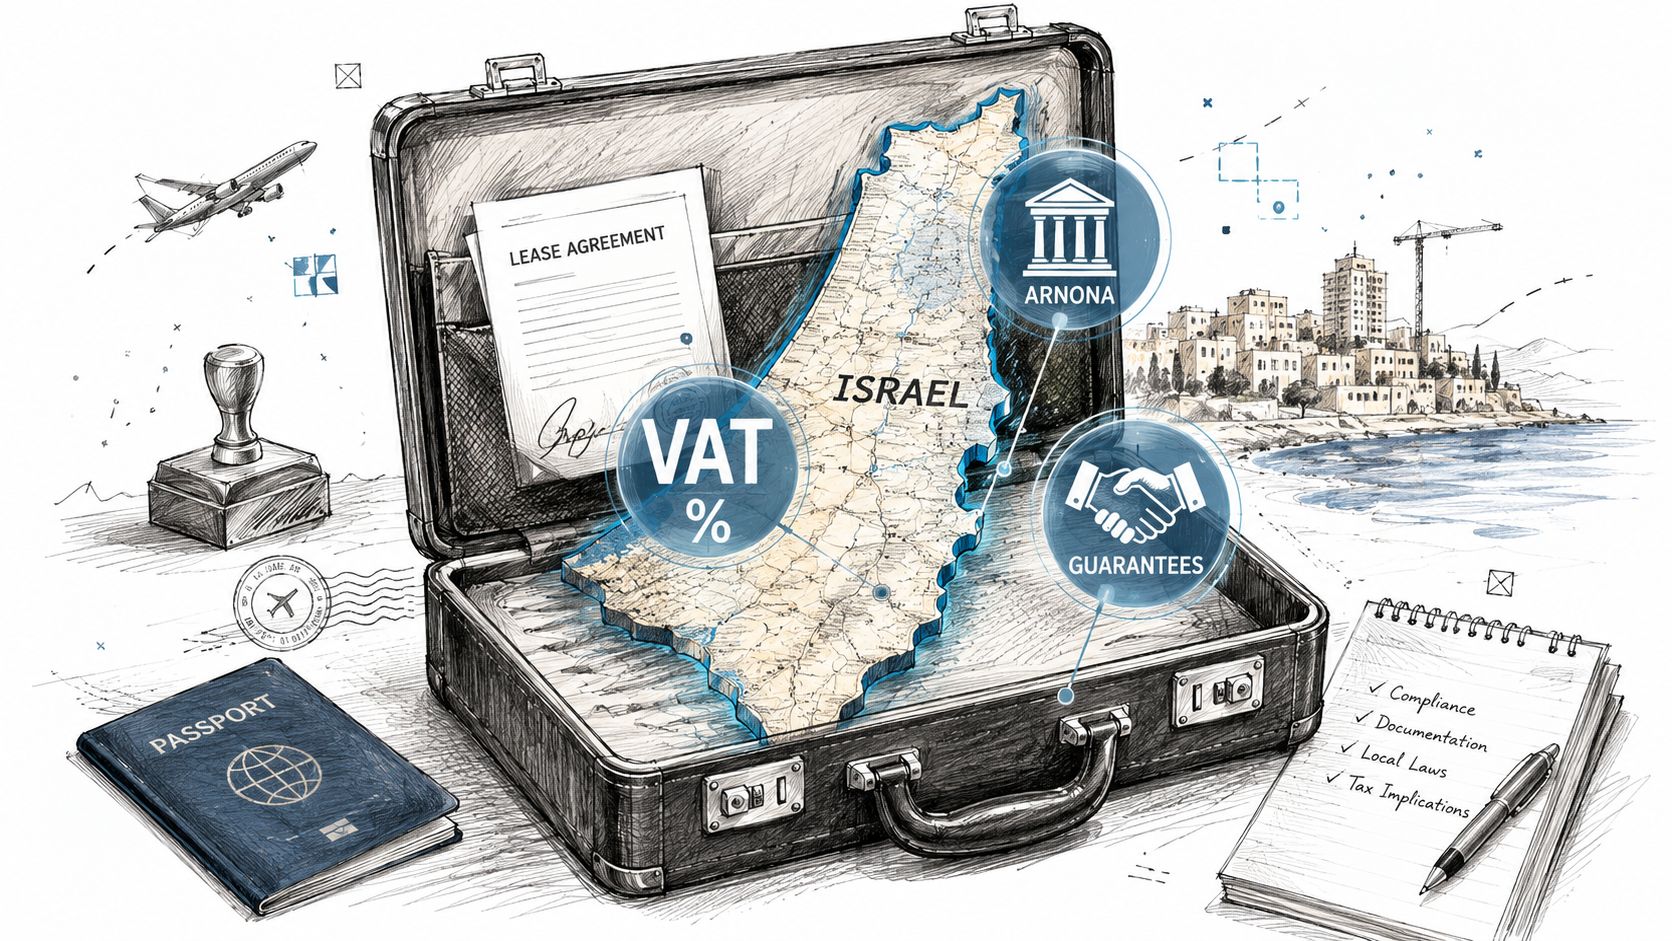
Israel adds a layer that many foreign tenants underestimate. The lease may look familiar on paper, yet VAT, Arnona, and bank guarantee practice can shift the economics fast. That is why cross-border tenants should treat the document as a financial instrument, not as a generic form.
Commercial rent and service charges can attract VAT treatment, so the contract must say who bears it and how it is calculated. Arnona, the municipal property tax, also needs clear allocation between landlord and tenant. In a gross lease, the rent may appear simple while the tenant still absorbs municipal and service-cost shifts through the back door.
Israeli bank guarantees are another pressure point. They often operate differently from a Western security deposit and can be set at a level tied to rent plus VAT. The result is immediate liquidity pressure, not just contingent exposure. A foreign tenant should never assume the guarantee behaves like a refundable deposit.
The indexation clause needs special care too. A foreign-currency-linked CPI escalation can create both inflation exposure and currency risk. That is a different problem from a local anchor tied to domestic business cycles. The right drafting therefore depends on who carries exchange-risk volatility, not just who signs the lease.
The strategic path that prevents avoidable loss
- Run pre-signing due diligence. Check zoning, Arnona status, and existing liens before the draft advances.
- Build a clause-by-clause risk matrix. Rank each clause by cash impact and control impact.
- File a written relocation and handback plan. Do it before opening, not during exit stress.
- Assign one legal owner. Cross-border leases fail when too many people “monitor” them and nobody owns escalation.
- Renegotiate priority first. Fix exit, transfer, guarantee, and repair risk before haggling over face rent.
The recommended strategic path is to treat the lease as a multi-year financial instrument, not a real estate form. That approach is also the only sensible way to handle Israeli VAT mechanics, Arnona allocation, and bank guarantees without costly surprises. For foreign tenants, the right response is not to accept landlord templates and hope for the best. It is to renegotiate the high-impact clauses first and leave the cosmetic edits for last.
RNC Group handles commercial lease review, cross-border lease negotiation, and related Israeli commercial risk issues for foreign tenants and corporate groups. The practical next step is to review the draft before signature and build a clause-by-clause risk map around VAT, Arnona, guarantees, transfer rights, and exit obligations. Visit RNC Group to start that process and avoid the mistakes that usually surface only after the keys are handed over.
The information above is general and does not replace specific legal advice. Commercial leases turn on specific facts, local law, and negotiated wording, so any tenant should obtain jurisdiction-specific review before signing or relying on any clause discussed here.