
Commercial law is the layered legal framework governing how businesses form, contract, finance, perform, and enforce deals across the full transaction lifecycle. In 2026, its real boundary sits where commercial relationships overlap with data, AI, and crisis enforcement.
That answer sounds straightforward, yet it carries a counterintuitive risk. A company can sign a carefully drafted contract and still face exposure through payment systems, mandatory local rules, evidence failures, data obligations, or an emergency bank restriction. Commercial law therefore works less like a single rulebook and more like an operational risk map.
For foreign boards entering Israel, investing in Israeli companies, or contracting with Israeli counterparties, that distinction matters. The right question isn’t only, “What does the contract say?” It’s also, “Which legal system controls each stage, which protections cannot be waived, and what happens when performance breaks down?”
Defining Commercial Law in 2026
Commercial law operates as a business risk map. It governs negotiations, contract formation, performance, payment, delivery, financing, breach, remedies, and enforcement, while connecting those stages to the rules that affect a transaction in practice. The Cornell Legal Information Institute’s explanation of commercial law captures that breadth by describing the field as rules governing business transactions.
A foreign board should review the business process, not only the signed agreement. Negotiators create obligations before execution. Procurement teams shape delivery, quality, and supplier exposure. Finance teams control payment, credit support, and security. Operations teams produce the records that may later prove performance or breach. Counsel must test each activity against applicable law, mandatory Israeli rules, and the contract’s chosen forum.
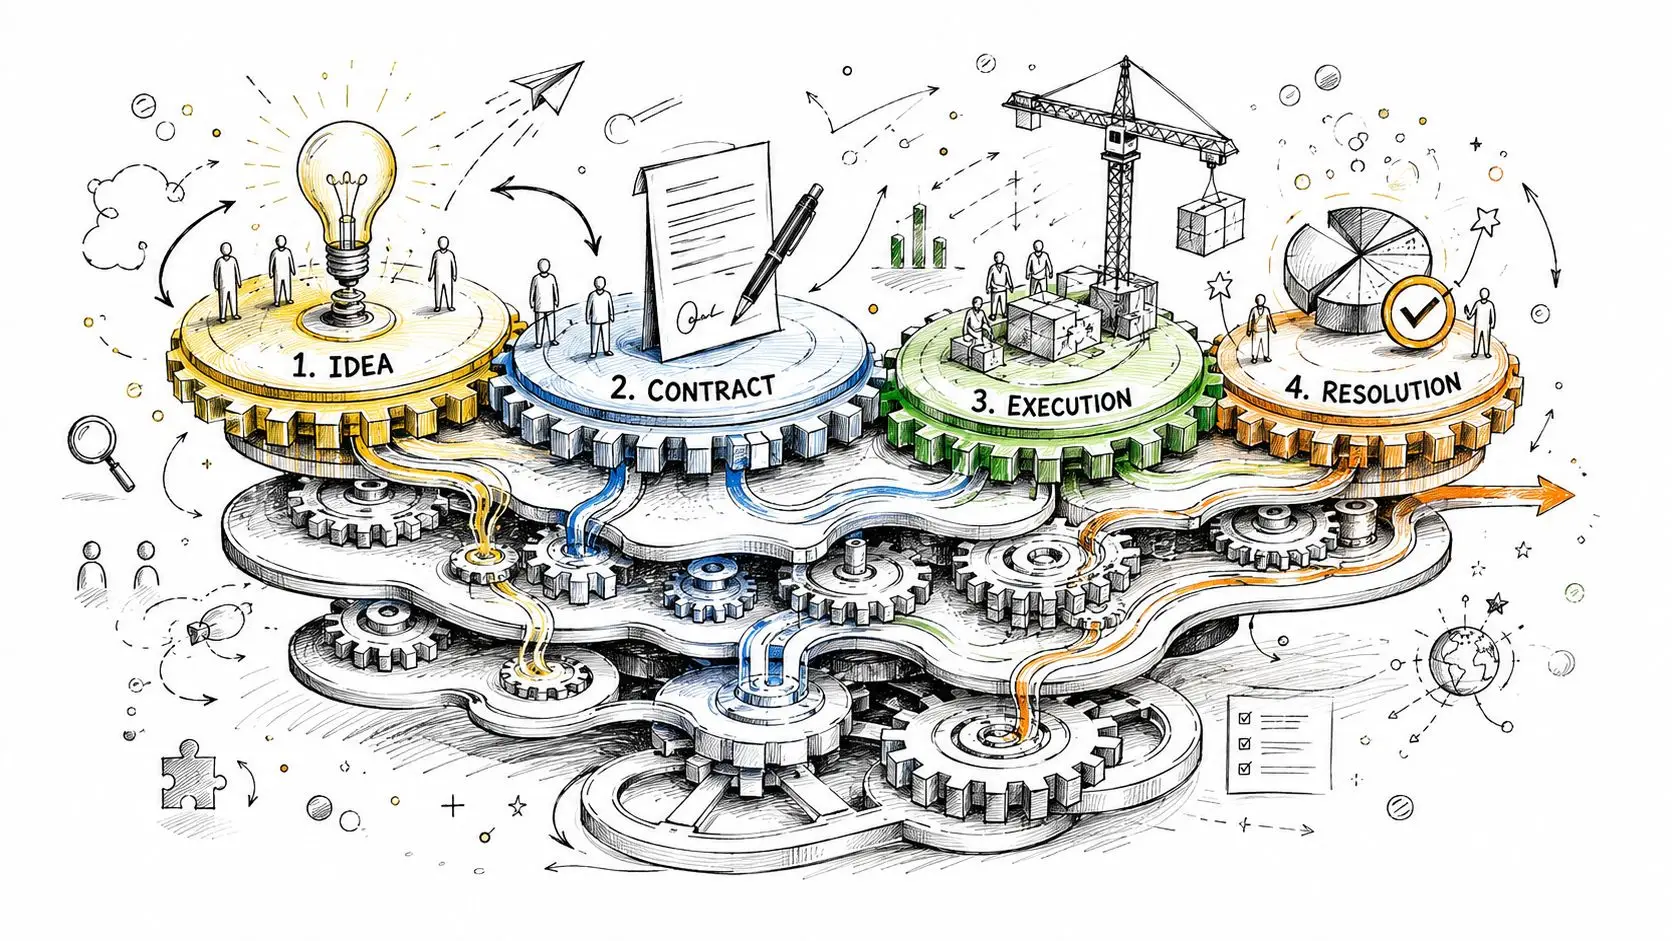
The operational map
A practical review starts with four questions:
- What was promised? Check the contract, incorporated specifications, purchase orders, and negotiation records.
- Who must perform? Examine corporate authority, agency, subcontracting, licensing, and partnership rules.
- How will payment work? Credit support, security interests, banking restrictions, currency, tax, and insolvency may alter the commercial outcome.
- What follows a breach? Governing law, court or arbitration forum, interim relief, evidence, and enforcement determine whether a remedy works outside the contract text.
Compliance belongs in that same review. Businesses assessing best compliance solutions for SMBs should connect controls to contracting, vendor management, data handling, and escalation procedures. A policy that never reaches the deal desk will not protect the transaction.
The modern boundary
Commercial law intersects with data protection, consumer protection, competition, procurement, sustainability, crypto regulation, and AI-related compliance. A customer-data clause can trigger privacy duties. An automated decision tool can create evidence and discrimination concerns. A franchise restriction can raise competition issues. A payment failure can develop into a banking, insolvency, fraud, or bank-restriction problem.
The clause and the crisis mechanism must therefore be read together. Cross-border arbitration may provide a forum, yet mandatory local rules can still control performance, evidence, payment channels, or enforcement. Contract analysis that ignores those pressure points leaves the board with a remedy on paper and limited control in practice.
Practical rule: Define commercial law by the business process it controls, the mandatory rules it cannot override, and the enforcement path available when performance breaks down.
How Merchant Custom Became Global Trade Governance
Commercial law began with merchants who needed dependable rules before national legal systems offered detailed commercial codes. By the 13th century, expanding local, regional, and intercontinental trade helped create the lex mercatoria, commonly called the law merchant (historical overview of commercial law).
Merchants needed rules that traveled with transactions. They negotiated sales, extended credit, arranged transport, managed partnerships, and resolved disputes across political boundaries. Custom therefore performed an economic function. It reduced uncertainty between parties who could not rely on one shared court or legal tradition.
In 1553, Benvenuto Stracca published De mercatura seu mercatore tractatus, often described as one of the first works focused specifically on commercial law. Later, national systems gradually codified merchant practice, including France’s Code de Commerce in 1807, Germany’s commercial code framework in the 19th century, and England’s Sale of Goods Act in 1893.
From custom to codification
Codification did more than organize legal doctrine. It converted repeated commercial expectations into enforceable rules for contracts, sales, banking, insolvency, and partnerships. That transformation explains why modern commercial drafting emphasizes certainty, allocation of risk, and remedies.
A written clause doesn’t merely record a deal. It also answers questions that merchant custom once answered informally:
- Which obligations are conditions and which are warranties?
- When does title or risk pass?
- What evidence proves delivery or acceptance?
- Can a party suspend performance?
- Which forum can grant urgent relief?
- How will a judgment or award become enforceable?
The answers now depend on national law, international conventions, and institutional dispute systems. They still serve the same commercial purpose, namely making trade workable between parties with different expectations.
Global instruments and predictable sales
The World Trade Organization reported 164 members, covering the vast majority of world trade, which makes cross-border commercial rules essential for international businesses (Oxford Academic discussion of commercial law and global trade). The same source identifies the United Nations Convention on Contracts for the International Sale of Goods, effective from 1988, as having been adopted by over 90 states.
The CISG illustrates the continuing value of harmonization. It can provide a common framework for international sales, but parties still need to examine exclusions, interpretation, remedies, and interaction with mandatory local rules.
For a foreign company, history offers a practical warning. Global trade creates shared patterns, but it doesn’t erase jurisdictional differences. A contract must still identify the law, forum, language, evidence standard, and enforcement route that will govern the relationship.
Mapping the Transaction Lifecycle to Legal Risk Buckets
A transaction becomes easier to manage when executives divide it into stages. Each stage creates a different evidence trail and activates different legal domains. Treating every problem as a contract dispute often misses the rule that controls the outcome.
The lifecycle map
| Business Stage | Primary Legal Domains | Typical Risk Trigger |
|---|---|---|
| Negotiation | Contract law, authority, confidentiality, competition | Unclear commitments, unauthorized promises, or leaked information |
| Formation | Contract formation, agency, corporate authority, applicable sales rules | Conflicting documents, unclear acceptance, or defective execution |
| Performance | Sale-of-goods rules, services law, licensing, regulatory compliance | Late delivery, defective goods, missed milestones, or unauthorized use |
| Payment and finance | Banking, secured transactions, credit support, insolvency | Nonpayment, weak collateral, blocked funds, or competing creditors |
| Breach and remedies | Contract remedies, arbitration, litigation, interim relief | Termination dispute, evidence loss, or unenforceable remedy |
The first stage requires discipline before any signature appears. Teams should preserve term sheets, emails, drafts, approvals, and authority records. Those materials can later determine whether a statement became a binding commitment or remained part of negotiation.
At formation, document hierarchy matters. A master agreement may conflict with a purchase order, service schedule, online terms, or invoice. The contract should state which document controls and how later amendments become effective.
Performance creates the evidence
Performance disputes rarely turn only on the final invoice. They often involve acceptance records, inspection notices, change orders, support tickets, delivery confirmations, and internal communications. A company that fails to preserve those materials may weaken a strong legal position.
Payment requires a separate review. A business may hold a contractual claim yet lack effective security, face banking restrictions, or encounter an insolvent counterparty. Counsel should therefore map payment mechanics alongside credit support and enforcement options.
A payment dispute isn’t always a simple breach claim. Security, banking, insolvency, and forum rules can control recovery.
At breach, the response should match the trigger. A minor delay may justify notice and cure. Fraud indicators may require evidence preservation and urgent relief. A recurring service failure may justify termination, but only after the contract’s notice and cure mechanism receives careful review.
Build the map before escalation
The strongest process identifies risk buckets during contracting, not after failure. A foreign board should ask operational owners to identify the documents, systems, approvals, and personnel connected to each stage.
That exercise exposes gaps quickly. It can reveal that the sales team promised service levels absent from the agreement, that finance lacks enforceable security, or that the chosen forum cannot grant the interim remedy the business needs.
Israeli Commercial Law and Cross-Border Contract Realities
Foreign companies often assume that a governing-law clause solves jurisdictional uncertainty. Israeli commercial contracts generally respect choice-of-law provisions, but mandatory Israeli rules can still apply when public policy or statutory protections arise (Israeli commercial contracts and governing law).
That creates a two-track review. Counsel must interpret the chosen foreign law, then identify Israeli rules that the parties cannot contract away. A clause selecting English, New York, or another law may guide contractual interpretation, yet it won’t automatically displace mandatory Israeli protections.
Negotiable terms and mandatory rules
Parties usually retain meaningful control over several commercial issues:
- Governing law: The clause can establish the primary interpretive framework.
- Forum or arbitration: The parties can often choose courts or arbitration institutions.
- Notice and cure: The contract can establish procedures before termination.
- Risk allocation: Indemnities, limitations, warranties, and insurance provisions can allocate exposure.
However, enforceability depends on the transaction and the applicable mandatory rules. A foreign board should commission a local review rather than rely on the assumption that a familiar template travels unchanged.
The Standard Contracts Law, 1982, can invalidate unfair boilerplate provisions in standard-form contracts. It can also affect clauses limiting a customer’s access to court, excusing supplier liability, or allowing a supplier to suspend performance unreasonably (Israel’s Standard Contracts Law).
Why templates create exposure
Franchise, service, licensing, and recurring commercial agreements often use standardized language. That convenience creates a predictable weakness. A supplier may insert broad suspension rights, unilateral discretion, or sweeping liability exclusions, then discover that the clause cannot operate as drafted.
Foreign parties should distinguish negotiated terms from inherited boilerplate. The more a template controls the relationship, the more carefully counsel should test its fairness, local enforceability, and interaction with sector-specific rules.
Forum selection creates another practical trade-off. A local Israeli court may offer proximity to assets and witnesses. Arbitration may provide confidentiality, procedural flexibility, and a neutral forum, but it still requires carefully drafted provisions on governing law, interim measures, evidence, language, and enforcement.
A contract that says “arbitration in Israel” without addressing those mechanics leaves strategic questions unanswered. The clause should identify the institution or rules, seat, language, tribunal structure, service method, and available emergency relief.
Where Commercial Law Ends and Crisis Enforcement Begins
Commercial law becomes an operational risk map when a routine transaction meets regulation, technology failure, or financial restrictions. The contract may remain commercially sound while data protection, digitalization, sustainability, consumer enforcement, crypto regulation, and AI create duties that change drafting, due diligence, insurance, evidence, and continuity planning.
Digital obligations change contract risk
A vendor agreement may allocate responsibility for a data breach, yet privacy law can impose duties beyond the contract. A customer may require defined security controls, incident notices, audit rights, or deletion procedures. These provisions affect insurance coverage and may determine whether the company can investigate, preserve, and disclose evidence after an incident.
AI creates a separate proof problem. AI-generated documents, altered signatures, synthetic communications, and manipulated records can make authority and performance difficult to establish. Contracting teams should specify approved systems, human review, access controls, and retention rules whenever AI enters a commercial workflow.
Competition and consumer rules apply alongside the contract. A franchise restriction, pricing instruction, or platform term may raise regulatory concerns even if both parties negotiated it freely. Counsel should test those provisions against Israeli mandatory rules, sector requirements, and the chosen dispute forum.
Crisis triggers need an escalation ladder
Fraud, insolvency pressure, ransomware, or a restricted bank account requires an immediate sequence of decisions. A foreign board should establish authority, preserve options, and avoid treating a banking restriction as an ordinary payment default.
- Stabilize operations. Protect payment access, customer service, payroll processes, and critical records.
- Preserve evidence. Secure contracts, emails, logs, approvals, banking notices, and communications.
- Classify the trigger. Separate contractual default from fraud, regulatory exposure, insolvency, or banking enforcement.
- Choose the forum. Assess court relief, cross-border arbitration, negotiation, and enforcement against assets in the relevant jurisdiction.
- Control communications. Align legal correspondence with operational and reputational objectives.
Recent litigation reporting identifies rising business bankruptcies, AI-related forgery risks, and enforcement involving data breaches and ransomware as factors affecting commercial disputes (2025 commercial litigation outlook). Crisis clauses and preservation protocols therefore belong in ordinary commercial planning, particularly where Israeli mandatory rules, an arbitration clause, and bank restrictions may apply at the same time.
Commercial Disputes and Debt Collection Under Pressure
A commercial dispute becomes expensive when the claimant chooses the wrong first move. A foreign creditor may send an aggressive demand, overlook a notice requirement, or file in a forum that cannot reach the debtor’s assets.
International arbitration provides a major channel for cross-border disputes. The ICC reported 881 new arbitration cases in 2025, involving construction, energy, pharmaceuticals, telecommunications, financing, insurance, and general trade (ICC dispute resolution statistics).
Start with the claim architecture
Suppose an Israeli company misses payment under a distribution agreement. The creditor should first review the governing law, invoice terms, acceptance records, security, notice clauses, and forum provisions. It should then send a formal demand that identifies the contractual default, required cure, supporting documents, and consequences of nonpayment.
For Israeli commercial debt collection, a formal demand letter often serves as the practical first step. Claims up to NIS 2.5 million go to the Magistrates Court, while larger claims go to the District Court, according to an Israeli commercial debt-collection guide (Israeli commercial debt collection procedure).
The same source states that a standard demand period ranges from 14 to 21 days. That window can support a structured escalation plan, but the contract may require a different notice period or cure procedure.
International creditors can also compare local requirements with state-by-state debt collection laws when their group structure involves United States entities. The comparison matters because collection strategy depends on the debtor’s location, assets, contract, and procedural rules.
Bank restrictions create operational pressure
Israel uses a staged mechanism for accounts affected by returned checks. The Bank of Israel states that an account becomes restricted for one year when 10 or more checks without cover return within a 12-month period. The restriction doesn’t apply when fewer than 15 days separate the first and tenth returned checks (Bank of Israel guidance on insufficient funds).
The Bank of Israel also states that a warning must follow five returned checks, because that level signals potential restriction risk. The sequence gives businesses an escalation point before restriction takes effect.
Payment controls should respond to that ladder. Finance teams should monitor returned checks, identify signing authorities, reconcile bank information, and escalate unusual payment failures immediately. A creditor should also assess whether the account restriction signals broader liquidity or insolvency pressure.
For a foreign board, the key issue isn’t merely recovery. It’s continuity. The legal strategy should protect evidence, preserve essential operations, and coordinate demand, negotiation, court relief, and enforcement.
A Practical Risk Mitigation Checklist for Business Leaders
A board can apply the following checklist before signing a cross-border commercial agreement or escalating a dispute.
Contract controls
- Map the documents: Identify the master agreement, schedules, purchase orders, online terms, invoices, and amendments.
- Test authority: Confirm the signatory’s corporate authority and preserve approval records.
- Define performance: Specify milestones, acceptance, inspection, service levels, delivery terms, and change-control procedures.
- Allocate liability carefully: Review indemnities, exclusions, caps, insurance, confidentiality, data obligations, and intellectual-property rights.
- Control termination: State notice, cure, suspension, termination, transition, and post-termination duties.
Jurisdiction and enforcement
- Select the law deliberately: Check the chosen law against mandatory Israeli provisions and public policy.
- Draft the forum clause completely: Address court jurisdiction or arbitration institution, seat, language, rules, interim relief, and enforcement.
- Locate assets early: Identify where the counterparty holds funds, inventory, receivables, intellectual property, or other recoverable value.
- Preserve multilingual meaning: Use controlled translations for correspondence, notices, and evidence when parties operate in different languages.
Crisis readiness
- Set payment triggers: Monitor returned checks, delayed transfers, covenant breaches, and unexplained account changes.
- Preserve evidence immediately: Secure originals, metadata, transaction records, approvals, communications, and system logs.
- Separate urgency levels: Distinguish ordinary default from fraud, cyber incidents, insolvency, regulatory exposure, and asset dissipation.
- Escalate proportionately: Begin with contractual notices where appropriate, then consider negotiation, interim relief, arbitration, litigation, or enforcement.
External counsel should become involved when several jurisdictions, material assets, urgent relief, fraud indicators, insolvency pressure, or conflicting agreements appear. Early review usually gives the business more choices than emergency litigation permits.
Strategic Commercial Law Planning for 2026 and Beyond
Commercial law gives business leaders a control system. It connects the commercial promise to the payment mechanism, performance evidence, regulatory perimeter, dispute forum, and crisis response.
The strongest strategy begins before conflict. It maps mandatory Israeli rules, cross-border enforcement, arbitration mechanics, digital obligations, AI-related evidence risks, and banking triggers. It then converts that map into contract language, internal approvals, monitoring, and escalation procedures.
RNC Group operates in this space through international commercial law, commercial agreements, bank-account restriction matters, multilingual legal correspondence, strategic crisis management, and cross-border litigation. Its approach treats courts and media as strategic tools within a phased plan, rather than assuming that litigation should always become the destination.
This article provides general information, not legal advice. The applicable result depends on the contract, facts, parties, jurisdictions, evidence, and mandatory rules, so readers should obtain advice from qualified counsel before acting.
RNC Group advises foreign companies, Israeli businesses, founders, franchise networks, and multinational corporations on commercial contracts, cross-border disputes, debt recovery, bank restrictions, and crisis execution. To avoid costly mistakes in governing-law clauses, payment controls, evidence preservation, and enforcement strategy, visit RNC Group or contact the firm through its international commercial law team.