
An M&A deal is decided in diligence and drafting, long before the signing photo.
Structure, representations, indemnity caps and closing conditions decide who carries what after completion. Understanding the mechanics changes what you negotiate.
We lead M&A transactions for buyers, sellers and investors with Israeli touchpoints. Reach us on WhatsApp or by email.
Mergers and acquisitions law is the body of corporate, antitrust, securities, and cross-border rules that governs how companies buy, combine, or restructure themselves. It operates from the first term sheet through post-closing integration, not just at signing.
That scope explains why the subject matters commercially. Worldwide reported deal value reached $3.98 trillion in 2025, up from $2.81 trillion in 2024, while transaction count moved from 44,379 to 44,817 and average deal size reached $88.9 million, according to WilmerHale’s 2026 M&A report. This shows that M&A law governs a continuous commercial process, not only exceptional megadeals.
For a CFO or founder, the practical question is sequencing. Which approvals must be secured before signing, which risks belong in the purchase price, which liabilities survive closing, and which jurisdictions can block the transaction even when the parties have agreed on the economics?
Table of Contents
-
The Short Answer on What Mergers and Acquisitions Law Actually Covers
-
Inside the M&A Transaction Lifecycle From Mandate to Closing
The Short Answer on What Mergers and Acquisitions Law Actually Covers
A U.S. technology acquirer may agree to buy an Israeli artificial-intelligence startup through a stock-for-stock transaction with founder rollover equity. At the same time, Israeli merger control, foreign-investment review, possible European turnover analysis, and U.S. antitrust filing obligations may all affect the timetable and the documents.
That is what is mergers and acquisitions law in operational terms. It governs mergers, share purchases, asset purchases, tender offers, and hostile takeovers, while allocating risk and coordinating approvals before closing, as explained in Cornell Law School’s M&A overview.
Four legal lenses control the outcome
Corporate law determines the transaction structure, board authority, shareholder approvals, fiduciary duties, and the consequences of choosing a merger, asset deal, or share purchase.
Antitrust and merger control examines whether the deal could create monopoly power or substantially lessen competition. It includes U.S. premerger notification, European review, and Israeli competition-law analysis.
Securities and disclosure law governs public-company reporting, accuracy of representations, material adverse change provisions, insider trading controls, and disclosure of information to shareholders and the market.
Foreign-investment screening examines whether a foreign buyer’s access to sensitive technology, infrastructure, data, or defense-related activity requires additional review. The relevant process can involve U.S. CFIUS review, European foreign-investment mechanisms, or Israel’s Advisory Committee for the Examination of Foreign Investments.
The best counsel doesn’t treat these as separate workstreams. The structure selected for corporate reasons can create a filing obligation. A disclosure decision can affect fiduciary-duty exposure. A rollover arrangement can alter ownership and control analysis. Counsel should therefore prepare a regulatory map before the parties commit to an irreversible signing timetable.
How Modern M&A Law Took Shape and Why It Went Global
Modern merger control developed from a simple concern, whether a transaction changes market structure in a way that threatens competition. In the United States, the Clayton Act of 1914 made merger review a specialized part of competition and corporate regulation, and the Celler-Kefauver amendments of 1950 expanded federal control to asset acquisitions and transactions involving parties that weren’t direct competitors, according to the Federal Trade Commission’s history of U.S. merger law.
The Hart-Scott-Rodino Act later added premerger notification for large transactions. That changed the legal sequence. Regulators could receive information before closing instead of investigating only after a transaction had produced harm. The result was a model in which deal certainty depends on legal clearance as much as on signed documents.
|
Jurisdiction |
Foundational statute |
Year |
Key mechanism |
|---|---|---|---|
|
United States |
Clayton Act |
1914 |
Federal review of acquisitions that may harm competition |
|
United States |
Celler-Kefauver amendments |
1950 |
Extended review to asset acquisitions and non-horizontal transactions |
|
United States |
Hart-Scott-Rodino Act |
1976 |
Premerger notification and review before closing |
|
European Union |
European Community Merger Regulation |
1990 |
Centralized review of qualifying concentrations |
|
Israel |
Economic Competition Law framework |
1988 |
Merger control and substantive competition analysis |
Why the framework became international
Multinational companies needed rules that could be compared across jurisdictions. The U.S. approach supplied a vocabulary based on market definition, concentration, competitive effects, efficiencies, and remedies. European and other regulators developed their own procedures, but the underlying question remained familiar.
For Israeli transactions, this history is useful because merger control isn’t a local technicality. Israel’s regime applies the same broad economic logic while imposing its own filing triggers, suspensory rule, and institutional process. A transaction can therefore be commercially agreed but legally incapable of closing until the relevant authority has been notified and the statutory waiting or review requirements have been addressed.
That distinction should shape the term sheet. A buyer that promises an unconditional closing date before mapping competition and foreign-investment issues is negotiating from an avoidable position of weakness.
Inside the M&A Transaction Lifecycle From Mandate to Closing
M&A counsel creates value before the first draft of the definitive agreement. The legal work should follow the transaction’s risk sequence, not the parties’ preferred announcement date.
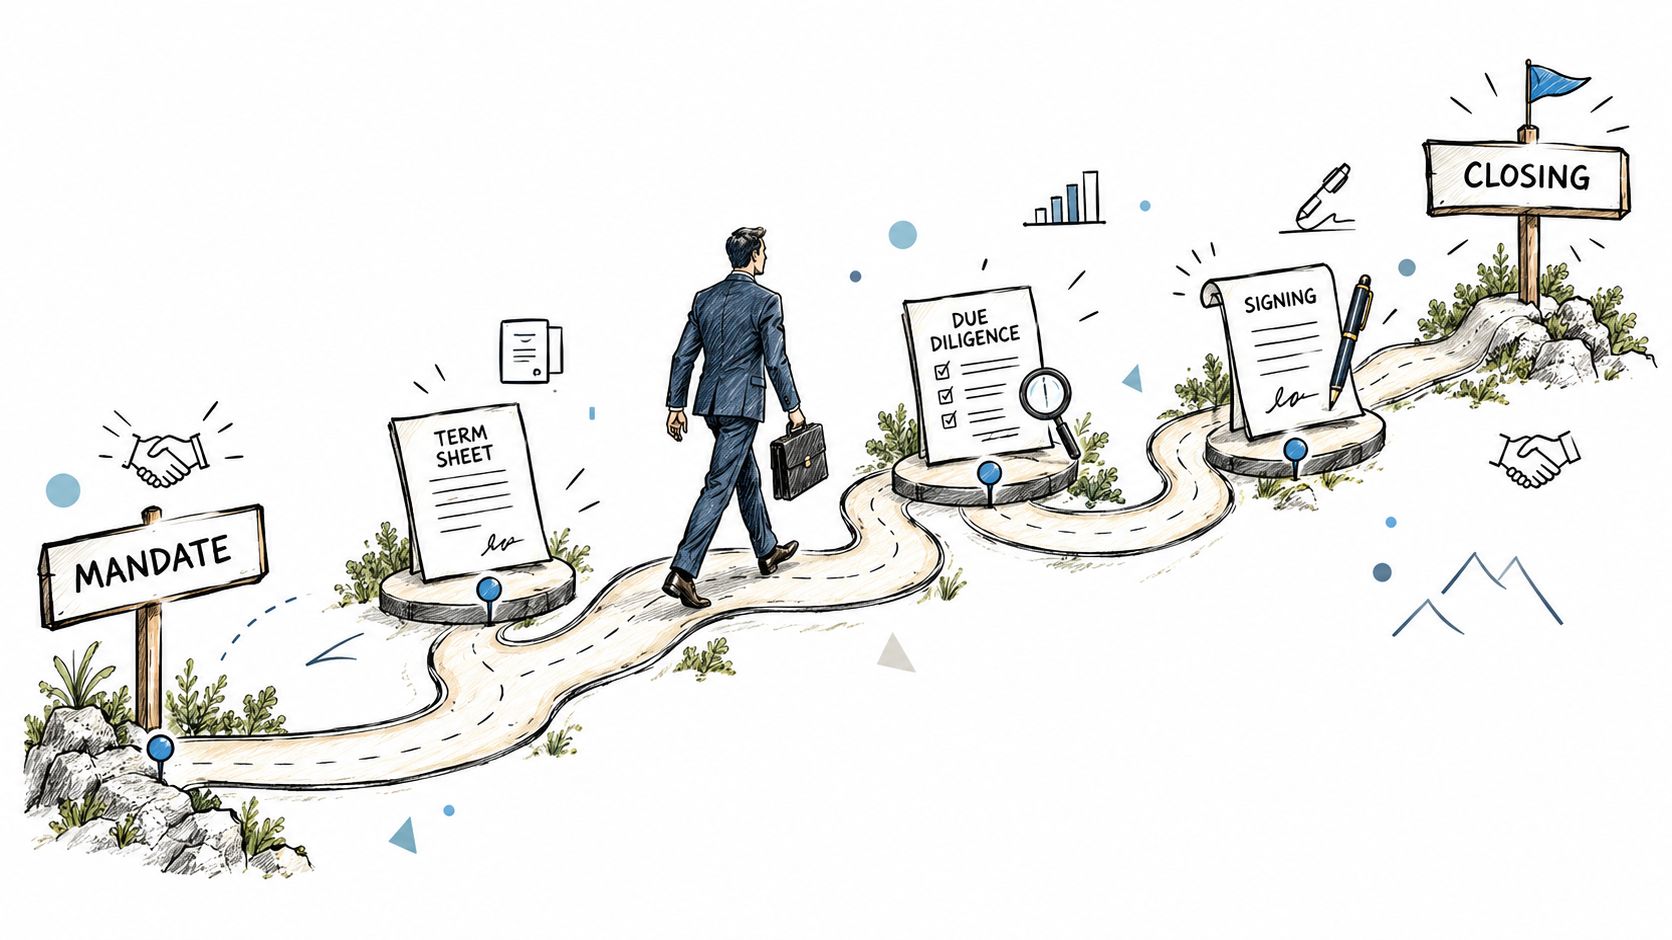
The early phases
-
Mandate and engagement. Counsel confirms board authority, clears conflicts, defines the engagement letter, agrees the fee structure, allocates responsibility among local and foreign advisers, and establishes the protected-data perimeter.
-
Preliminary structure. The team prepares a corporate red-flags memorandum, reviews the capitalization table, and compares share, asset, merger, and rollover structures. Tax, licensing, control, and foreign-investment consequences should first be surfaced at this stage.
-
Term sheet and letter of intent. Exclusivity, no-shop obligations, confidentiality, access rights, expense allocation, and any breakup fee require deliberate drafting. Even provisions intended to be non-binding can influence negotiating power and later disputes.
-
Due diligence. Counsel puts the NDA and virtual data room in place, creates an information request list, and converts findings into a report that management can use for valuation and risk decisions. A buyer considering acquisition financing should also align the legal timetable with the financing structure, including lender requirements and equity contributions. A practical overview of how parties may finance a business acquisition can help frame that coordination.
The execution phases
The definitive documentation normally includes the share purchase agreement, disclosure schedules, and ancillary agreements. Counsel then tracks antitrust filings, foreign-investment clearances, customer and supplier change-of-control consents, financing conditions, shareholder approvals, and the accuracy of representations at closing.
The conditions-precedent schedule should be a live document, not an appendix forgotten after signing. At closing, counsel coordinates funds flow, escrow, equity issuance, releases, board changes, and delivery of bring-down certificates. Post-closing work then turns to integration, employee transitions, data access, contract novations, remediation, and the enforcement of continuing covenants.
Practical rule: A signing date is only credible when every required closing condition has an owner, evidence standard, and regulatory dependency.
Legal Due Diligence as the Spine of Any Deal
Due diligence isn’t a document-counting exercise. It is a risk-pricing discipline that tests whether the business being bought matches the business described in the negotiations.
The buyer should review corporate records, material contracts, intellectual property, litigation, liens, tax, employment, regulatory status, privacy, sanctions exposure, and financing arrangements. These categories can reveal liabilities that change valuation, require indemnities, become closing conditions, or prevent the buyer from obtaining the intended commercial benefit. Thomson Reuters’ due-diligence guide describes this process as a systematic review of the target’s legal and regulatory position.
A red-flag report is appropriate when management needs rapid triage. Vendor due diligence serves a different purpose, presenting the seller’s business in a structured format for multiple potential buyers. Neither replaces targeted follow-up on missing records, inconsistent explanations, or contracts whose practical operation differs from their wording.
|
Diligence finding |
SPA risk-allocation mechanism |
Typical pricing lever |
|---|---|---|
|
Unresolved tax exposure |
Specific tax indemnity, escrow, covenant |
Purchase-price adjustment or holdback |
|
Unclear IP ownership |
Closing condition, special indemnity, remediation covenant |
Reduced value or delayed closing |
|
Change-of-control consent absent |
Condition precedent or termination right |
Timing protection and price leverage |
|
Regulatory non-compliance |
Specific indemnity and post-closing remediation |
Risk premium or escrow |
|
Litigation with uncertain exposure |
Representation, indemnity, conduct-of-claim provisions |
Retention, escrow, or revised consideration |
The same contract clause can have very different economic consequences depending on the evidence behind it. A broad representation may look protective until the disclosure schedule reveals a recurring compliance failure. Conversely, a narrow indemnity may be acceptable where the buyer has verified the underlying records and secured insurance coverage.
Real-estate acquisitions illustrate the same principle. A separate buying property Israel inspection checklist can help non-specialists understand why title, physical condition, planning, and recorded rights must be verified rather than assumed.
Cross-Border Antitrust and Israeli Merger Control in 2026
Cross-border review should be sequenced before the parties promise signing or closing dates. U.S. HSR analysis generally examines the size of the transaction and the size of the parties, while European review turns on applicable turnover thresholds and may provide a one-stop review for qualifying concentrations. The exact filing analysis remains jurisdiction-specific and depends on the transaction structure, parties, activities, and applicable thresholds. These foreign-law references are a general overview, not an Israeli-law conclusion; current U.S. and EU requirements must be checked separately by counsel in the relevant jurisdiction.
Israel requires particular discipline. A merger notification is generally required when the transaction qualifies as a merger of companies and at least one statutory trigger applies. Section 17 covers three alternative triggers: the merger creates a combined market share above 50%; one merging company already holds more than 50% of a relevant market under section 26(a)(1); or combined Israel turnover exceeds NIS 423,780,000 in the prior financial year where at least two merging parties each had Israel turnover of at least NIS 23,040,000. The statutory merger definition, group calculation and required Israeli nexus must also be checked. The Israel merger-control guide provides background, while the updated 2026 figures are reported in Arnon, Tadmor-Levy’s July 2026 merger-control review: https://arnontl.com/news/israel-merger-control-2026-icas-new-merger-guidelines/
The regime can also apply to acquiring more than 25% of rights where the stake provides the relevant level of nominal share capital, voting power, board-appointment power, or participation in profits. The analysis is revisited when the holding rises above 50%, as described in the Israeli control-threshold analysis.
The suspensory rule changes the timetable
The Israel Competition Authority’s regime is suspensory. Where notification is required, parties cannot complete a merger before they notify and obtain the Commissioner’s approval, so filing alone is insufficient and the process is a condition to closing rather than an informational formality, as stated in the Authority’s explanation of suspensory effects.
The April 2026 draft Israeli guidelines described a rebuttable presumption where either post-merger HHI exceeds 1,800 or combined market share is at least 30%, and in either case the HHI increase exceeds 100, according to the published analysis of the draft guidelines. Because these are draft guidelines, counsel should treat them as a planning signal, not as an adopted current rule or a substitute for the operative legal test. Separately, section 21 of the Competition Law permits objection or conditions where there is a reasonable concern of significant harm to competition or to the public; numerical draft thresholds do not replace that statutory test.
|
Regime |
Filing trigger |
Review timeline |
Substantive test |
|---|---|---|---|
|
U.S. HSR |
Applicable size-of-transaction and size-of-person criteria |
Statutory waiting process before closing |
Likely effect on competition |
|
EU EUMR |
Applicable turnover thresholds |
Pre-notification and formal review |
Significant impediment to effective competition |
|
Israeli merger control |
Statutory merger definition and applicable trigger |
Notification and the Commissioner’s approval before completion because the regime is suspensory |
Effect on competition, with draft HHI presumptions as a planning reference |
Foreign-investment screening may run beside antitrust review, particularly in defense, telecommunications, finance, sensitive technology, and data-rich sectors. Counsel should decide early whether Israeli clearance must precede a foreign filing, whether information can be shared safely, and whether the transaction documents need long-stop dates, cooperation covenants, or termination rights.
Hidden Liabilities and Post-Closing Risk Management
Signing doesn’t make historical risk disappear. In a share acquisition, the legal entity generally remains the same entity that incurred its prior obligations. The buyer can therefore inherit exposure connected to tax, labor, sanctions, anti-money-laundering controls, fraud, intellectual property ownership, privacy incidents, and environmental conditions, subject to the governing law and transaction documents.
Historical sanctions or export-control failures can become visible only after integration gives the buyer access to records that were previously fragmented. A pre-closing data breach may also create notification and remediation issues under applicable privacy regimes. Unclear invention assignments can undermine the value of a technology target even where the SPA contains broad IP representations.
How buyers should allocate the exposure
Experienced buyers use several tools together:
-
Specific indemnities for identified tax, labor, regulatory, IP, or compliance risks.
-
Escrow or holdbacks where a claim may take time to quantify.
-
Representations and warranties insurance where coverage is available, while checking exclusions, retention, disclosure standards, and subrogation terms.
-
Post-closing covenants requiring remediation, cooperation, record preservation, and assistance with claims.
-
Claims procedures that define notice, control of defense, settlement authority, and recovery limits.
The SPA cannot paper away every statutory obligation or regulatory consequence. Contractual recovery may also be limited by survival periods, caps, baskets, exclusions, governing law, and the financial strength of the indemnifying party.
The recommended strategic path is a post-closing liability map with named owners, priority ratings, evidence preservation, and a remediation calendar. Within the first ninety days after closing, the buyer should confirm access controls, sanctions and AML procedures, employee files, IP assignments, privacy incident records, tax positions, permit status, and all open disputes. Integration should be treated as a legal-control process, not only an operational project.
An Action Checklist for Buyers, Sellers, and Founders
A CFO or founder can impose useful discipline before counsel completes every document. The checklist below separates decisions that prevent structural mistakes from tasks that merely improve administration.
Before the mandate
-
Clean the capitalization table. Identify options, warrants, convertible instruments, founder rights, minority protections, and missing approvals.
-
Run conflicts checks. Confirm that proposed advisers can act for the relevant entity and identify existing relationships that could restrict representation.
-
Set the approval matrix. Specify who may approve the structure, price range, exclusivity, signing, disclosure, and closing.
-
Define the deal team. Allocate responsibility among management, finance, tax, regulatory advisers, and local counsel.
-
Protect sensitive information. Establish the NDA, access levels, data-room rules, and a log of information shared with potential buyers.
Before signing
The parties should confirm the filing analysis across U.S. HSR, EU review, and Israeli merger-control criteria, including the 2026 draft HHI framework as a planning consideration rather than an operative replacement for the applicable legal test. They should also complete sanctions and AML checks through the ultimate-beneficial-owner chain, finalize exclusivity and no-shop language, and identify every required third-party consent.
The non-delegable question is signing readiness. Management must know whether the agreement can be signed without violating a filing restriction, whether the disclosure schedules are complete enough to support the representations, and whether the financing and regulatory assumptions are documented.
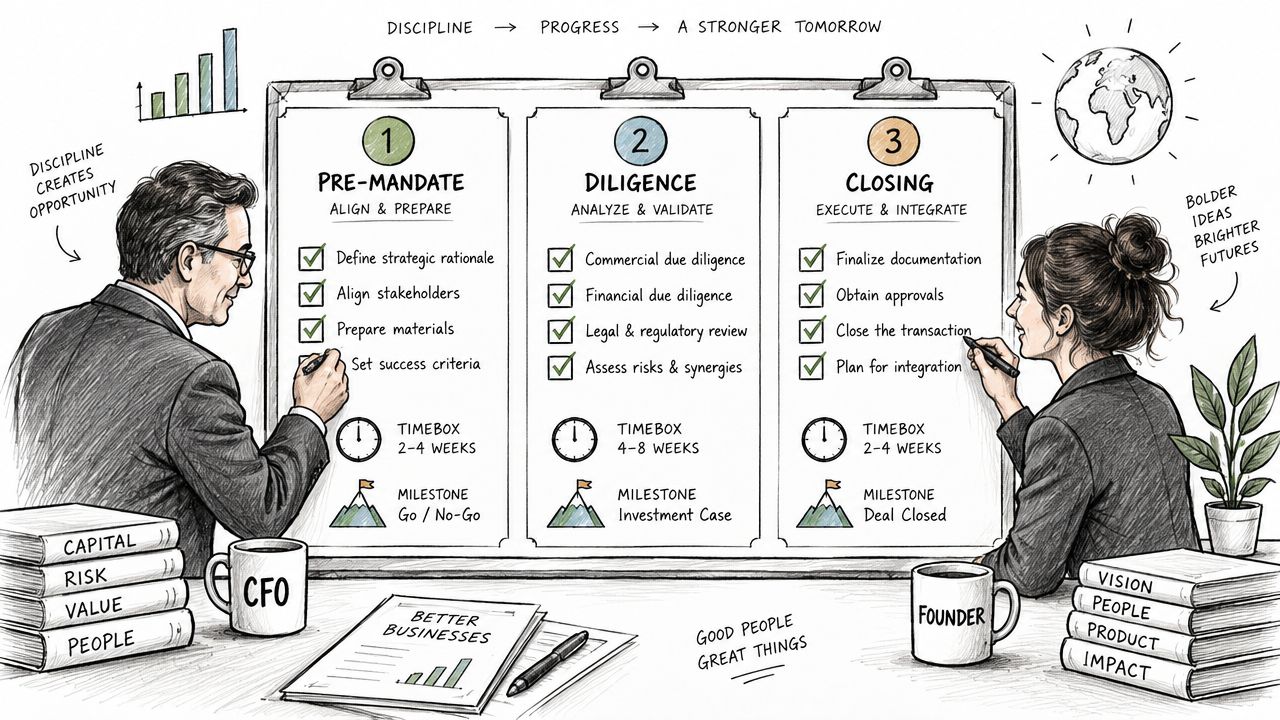
Before closing
-
Maintain a conditions-precedent tracker. Assign an owner and evidence standard to each condition.
-
Calendar regulatory clearances. Include filing dates, response dependencies, information requests, and long-stop consequences.
-
Bind the risk-transfer package. Confirm escrow mechanics, insurance terms, indemnity caps, exclusions, and claims procedures.
-
Prepare a Day-One integration brief. Cover employees, systems, data, contracts, permits, customer communications, and open remediation.
-
Conduct the bring-down review. Recheck representations, material adverse change provisions, litigation, compliance events, and required certificates.
Each item addresses a specific failure mode. Cap-table cleanup prevents ownership disputes. Filing analysis prevents unlawful completion. Diligence tied to indemnity prevents unpriced liabilities. A conditions tracker prevents an apparently complete deal from failing at the final procedural step.
Recap, Common Questions, and How to Engage Counsel
M&A law works through four connected lenses: corporate authority and structure, competition review, disclosure and securities compliance, and foreign-investment screening. The transaction lifecycle runs from mandate and preliminary structure through the LOI, diligence, definitive documents, regulatory clearances, signing-to-closing conditions, closing mechanics, and integration.
Three controls create the greatest impact. First, diligence must change the SPA and the price, not sit in a report. Second, antitrust and Israeli merger-control analysis must precede promises about signing and closing. Third, post-closing liability mapping must begin before integration obscures the target’s historical records.
Common questions
How long does a mid-market deal take from LOI to closing? There is no reliable universal duration. The timetable depends on diligence quality, financing, shareholder approvals, third-party consents, regulatory filings, foreign-investment review, negotiation complexity, and whether authorities request additional information. Counsel should build a critical-path schedule rather than promise a generic closing period.
Should an Israeli founder sign an English or Hebrew SPA? The governing language should match the parties, financing documents, enforcement forum, and transaction structure. An English agreement may be commercially practical in an international deal, but the parties should address translation, interpretation, notices, signing formalities, and any Israeli-law requirements with counsel before execution.
What triggers mandatory Israeli Competition Authority notification in 2026? The answer depends on whether the transaction is a statutory merger of companies and whether a filing trigger applies. Relevant filing triggers include monopoly or combined market-share thresholds and the stated Israel turnover thresholds, alongside the required Israeli nexus and the statutory merger definition. By contrast, the acquisition of more than 25% of qualifying rights is part of the merger-definition analysis, not an independent filing trigger, and the step above 50% also belongs to that merger-definition analysis. The 2026 draft HHI thresholds are a substantive-review planning signal, not a replacement for transaction-specific advice.
How does R&W insurance interact with seller indemnities? Insurance doesn’t automatically replace the seller’s indemnity. The SPA must allocate retention, caps, exclusions, disclosure standards, fraud treatment, special risks, and subrogation rights. Identified risks commonly require specific indemnities or escrow because insurance may exclude them.
RNC Group handles international commercial matters involving Israeli and foreign parties, including M&A structuring, diligence coordination, negotiation, and transaction execution. The recommended first-call materials are the capitalization table, proposed structure, term sheet or LOI, target and buyer jurisdiction details, regulatory footprint, financing outline, material contracts, and any known compliance or dispute issues.
RNC Group advises founders, Israeli companies, and multinational buyers on cross-border M&A sequencing, Israeli merger control, diligence-based risk allocation, and closing preparation. To avoid costly mistakes before signing or closing, the recommended strategic path is to contact RNC Group with the proposed structure and transaction timetable.
This article is for general information only and does not constitute legal advice. Laws and their application depend on the facts and jurisdiction and may change. Although we aim to keep this information accurate and current, we do not guarantee that it is complete or up to date. The article may contain omissions or errors. Reading this article does not create an attorney-client relationship with RNC Group. Before making a decision or taking action, seek advice from a qualified lawyer in the relevant jurisdiction.