
A cross border transaction can look finished on signature day and still fail on settlement day, which is why 2026 boards need to stop treating it like a payment formality. The underlying risk sits in the sequence, not the headline price. Tax, banking, compliance, enforceability, and dispute paths all have to line up before the first wire leaves the account.
The Deal That Looked Perfect Until the Second Wire
An Israeli SaaS company signs a licensing deal with a German distributor. The business team celebrates the signature, finance prepares the first invoice, and the lawyers file the agreement away as done. Then the second wire stalls, the bank asks questions, the tax team notices no withholding position was built into the payment clause, and the audit right in the contract has no clear enforcement path if the distributor resists.
That pattern is common in cross border transactions. The commercial deal closes on paper, but the operational deal has not been sequenced.
The mistake is usually structural
The parties often negotiate the business terms first and leave the legal mechanics for later. However, later is exactly when the advantage disappears. Once funds move, the payer has less room to condition performance, and the recipient gains more room to argue that the contract says one thing while local law says another.
Practical rule: If the transaction touches more than one jurisdiction, the contract must absorb tax, banking, and enforcement risk before signature.
That is why a cross border deal behaves like a chain. One missed link can trigger a bank review, a tax exposure, or an unenforceable clause. A strong commercial price does not fix a weak payment sequence.
The cross border market is also too large for casual drafting. The IMF cited estimates that the total addressable market reached about US$194.6 trillion in 2024, and its 2025 paper said the market for cross-border payments reached US$190 trillion in 2023. FXC Intelligence sized the combined wholesale and retail market at US$208 trillion in 2025, with a US$625 billion revenue pool across use cases, as noted in the IMF paper itself. For executives, that scale means tiny drafting errors can hit very large flows. IMF cross-border payments market paper
A good contract does not just describe the deal. It sequences the deal so the transfer, the compliance review, and the enforcement route all survive contact with reality.
Defining Cross Border Transactions Beyond the Wire
A cross border transaction is any financial or commercial transaction between parties in different countries, usually moving funds or rights through banks or other institutions across national borders. That sounds simple, but the legal work starts only when the transaction is broken into layers. Each layer creates a separate exposure.
The three layers that change the deal
The first layer is the counterparty layer. One party sits in one jurisdiction, the other in another, and that difference changes how notices, warranties, and disputes work. It also changes who can be sued, where evidence sits, and whether a local judgment will matter.
The second layer is the currency layer. A domestic contract can ignore conversion timing, FX spread allocation, and payment currency clauses. A cross border contract cannot. If the deal uses more than one currency, the payment clause becomes part of the commercial bargain, not just back-office administration.
The third layer is the regulatory layer. Every jurisdiction that touches the flow can impose its own rules on taxes, licensing, AML review, and reporting. That is why the contract must say who handles compliance, who supplies information, and who bears the loss if the bank rejects the transfer.
What changes compared with a domestic deal
A domestic transaction usually allows simpler governing-law choices, simpler enforcement, and fewer moving parts in the payment chain. A cross border deal needs more. It needs a realistic forum, a tax position, and a compliance process that can survive bank screening.
For practical drafting, a deal team should ask four questions before calling something cross border. Which jurisdictions touch the money, which jurisdictions touch the rights, which jurisdictions can freeze the transfer, and which jurisdiction can enforce a remedy. If those answers are not documented, the transaction is not ready.
A useful external reference on modern cross-border payment flow is Axcnh transforming cross border trade, especially for teams comparing operational payment options with legal design.
Four Core Transaction Types and Their Risk Signatures
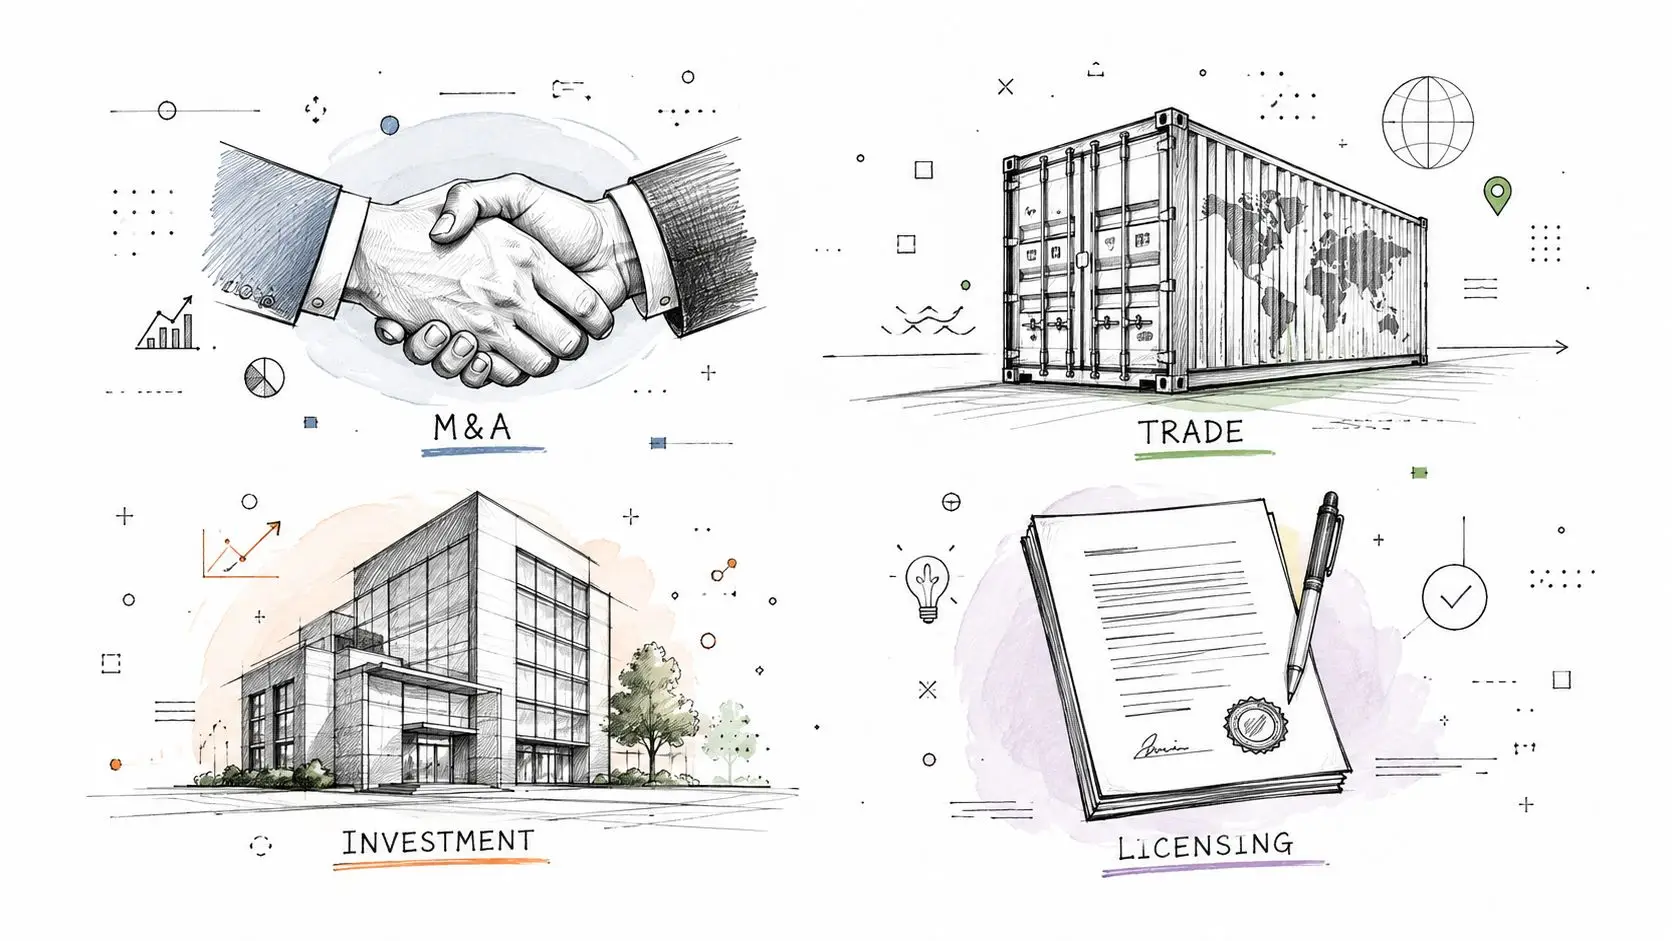
Not every cross border transaction carries the same legal weight. The contract should match the archetype, because the risk pattern changes with the structure.
M&A, licensing, distribution, financing
M&A is the highest-stakes format because it transfers control. It invites securities, antitrust, disclosure, and post-closing liability questions. The signing package must therefore cover title, reps, indemnities, disclosure schedules, and the enforcement route for a breach.
Licensing is a recurring-revenue structure. The main risks are IP leakage, royalty reporting, source-code access, and repatriation mechanics. If the licensee controls the local market, the licensor also needs audit rights that work in the destination jurisdiction.
Distribution is a volume model. Here the pressure comes from local agent liability, product liability, customs handling, and how much control the exporter retains over pricing, promotion, and inventory. A distribution contract that reads like a passive supply agreement usually under-protects the manufacturer.
Cross border financing is the most banking-heavy form. It turns on repayment enforceability, security perfection, sanctions screening, and FX exposure. Even a clean loan can become messy if the repayment path conflicts with local currency rules or the borrower’s bank demands new compliance material.
| Transaction type | Main commercial driver | Main legal pressure point |
|---|---|---|
| M&A | Control transfer | Closing liability and enforcement |
| Licensing | Recurring royalties | IP control and audit rights |
| Distribution | Market reach | Local liability and channel control |
| Financing | Capital movement | Repayment and banking compliance |
Draft to the structure, not the label. A licensing deal with exclusivity can behave more like a strategic collaboration. A distribution deal with branded know-how can behave like a partial IP transfer.
That is why a practitioner must identify the transaction shape early. Once the wrong structure is chosen, the contract starts solving the wrong problem.
The Regulatory Stack That Governs Every Cross Border Deal
Cross border deals are not governed by one rulebook. They sit under overlapping stacks, and the contract should allocate responsibility for each stack explicitly.
Tax, AML, FX, securities
Tax is often the first cash-flow issue. Withholding, treaty eligibility, transfer pricing, and gross-up mechanics determine what the recipient receives. A deal can look profitable and still leak margin if the payment clause ignores tax allocation.
AML and KYC sit in the payment path. Businesses must deal with beneficial ownership checks, sanctions screening, and suspicious-activity processes, while banks can stop the transfer if the data set is incomplete or inconsistent. ACI Worldwide explains that cross-border payments usually route through correspondent networks, where each intermediary can add compliance checks and delay settlement. ACI Worldwide on correspondent banking frictions
FX and capital controls matter where conversion timing or repatriation limits exist. If local law restricts conversion or reporting, the contract should say who bears the timing risk and who must secure the approvals.
Securities regulation is triggered when the structure crosses into equity, debt, or convertible rights. That can happen faster than many commercial teams expect, especially when a revenue-sharing or investment-style instrument is documented loosely.
In the United States, cross-border payment providers generally face federal registration with FinCEN as a Money Services Business under the Bank Secrecy Act, plus separate state-level Money Transmitter Licenses where they operate. That two-tier structure matters because the provider’s licensing posture affects the client’s payment risk. US licensing overview for cross-border providers
Transparency is not optional
In the EU, Directive (EU) 2015/2366 requires transparency over the charges and exchange rate used in cross-border payments. That makes fee disclosure a legal duty, not a courtesy. EU cross-border payments transparency summary
Global compliance also has no single unified standard. Businesses must work through overlapping AML, KYC, sanctions screening, and jurisdiction-specific licensing and reporting requirements. Visa compliance overview
The practical rule is simple. If the contract does not allocate which party supplies compliance data, pays withholding, and handles bank queries, the payment stack will rewrite the economics after signing.
Contract Architecture for Cross Border Enforceability
A cross border contract is not a domestic contract with an international address. It is a different document, because it has to survive two legal systems and usually more than one payment system.
The clauses that decide whether the deal holds
Governing law determines which legal rules interpret the text. Forum selection determines where the dispute gets heard. Those are not interchangeable. A strong governing-law clause with a weak forum clause can still leave the client chasing relief in the wrong place.
The payment language needs equal care. Currency of performance should identify the exact payment currency. Netting should state whether offsets are allowed. Gross-up clauses should say who bears withholding and how the recipient is protected if tax is deducted at source.
If the payment clause is vague, the bank often becomes the real drafter.
The risk-allocation layer matters just as much. Indemnities should cover tax surprises, regulatory breaches, and local-law claims. Limitation of liability should match the deal economics, not a template imported from a domestic contract. Representation and warranty insurance can help in some transactions, but it does not replace a clean indemnity chain.
IP controls must be operational, not decorative
If the deal licenses software, technology, or know-how, the contract needs escrow, audit rights, termination triggers, and source-code controls that work in the target country. Without those tools, the licensee can continue exploiting the asset long after the relationship breaks down.
The same logic applies to multilingual transactions. If the deal will be enforced abroad, the notice package, the exhibits, and the correspondence should be drafted with translation in mind from the start. RNC Group’s commercial practice includes cross-border transaction work and multilingual legal correspondence, which matters where local execution and notarial formalities need to align with the deal documents.
The cleanest clause set is the one that answers a breach before it happens. Who pays, where it gets litigated, what law applies, and how the asset survives if the other side walks away.
Operational Risks From Banking to IP Leakage
Even a well-written contract can fail if the payment rail and the operational setup are wrong. That is where most cross border deals break.
Banking design shapes settlement speed
Cross border transfers usually route through correspondent banking chains, not directly between domestic systems. Each additional intermediary can add screening, reconciliation, or message-format risk. That is why the same USD or EUR transfer can feel immediate in one corridor and slow in another.
The BIS notes that approximately 75% of cross-border transactions are credited to the recipient within one hour under the global payments target framework. BIS bulletin on speed benchmarks That benchmark matters because it shows speed is often a design choice, not a mystery. Banks, cut-off times, and routing decisions shape the result.
IP leakage is often an operational problem
A foreign distributor, licensee, or joint-venture partner does not need to steal source code outright to damage the owner. Control over operational data can be enough to replicate, redirect, or dilute the asset. That is why data segregation, limited user permissions, and escrow logic belong in the operational plan, not just the contract appendix.
Operational rule: If the other side can see everything, it can often keep more than the contract intended.
For teams moving SaaS or digital services globally, a practical payment layer can reduce friction, but it does not remove legal risk. A useful operational comparison is Creem international payment solution, because it shows how payment routing and product design sit together in global software commerce.
The strategic point is straightforward. Bank selection, corridor choice, and data control need to be drafted together. A contract that ignores operational routing leaves the business exposed when the payment stalls or the partner learns more than it should.
Dispute Resolution and Cross Border Enforcement
A cross border dispute starts before the first letter goes out. The enforcement route has to be built into the original transaction, or the remedy may become expensive theater.
A phased response beats panic
The first step is pre-action evidence preservation. Save the contract version, payment trail, bank correspondence, and compliance notices. If the other side is likely to move assets, act early and document the gap.
The second step is forum selection and interim relief. A neutral arbitration seat often works better than a home-court instinct, because neutrality can make recognition easier in the counterparty’s jurisdiction. London, Geneva, and Singapore are often chosen for that reason, not for convenience.
The third step is recognition and enforcement. A judgment or award only matters if it can be turned into a recovery path where the assets are located. That is why the enforcement seat in the other jurisdiction matters as much as the seat on the signature page.
Translation can decide the dispute
Many cross border disputes fail on wording, not substance. If a demand letter, notice of default, or pleadings package goes out in the wrong language or with the wrong certified translation, the other side gains time and an advantage. Multilingual legal correspondence is therefore a tactical tool, not an administrative chore.
Use the enforcement map before signature
- Identify asset locations before the deal is signed.
- Choose the forum that can produce a usable remedy.
- Align notices with the language and form that local counsel can enforce.
- Preserve negotiating power by planning interim relief, not just final judgment.
- Trace the payment path so the collection plan follows the money, not just the contract.
RNC Group is often used in this type of work because its commercial and litigation practice combines contract drafting, international correspondence, and cross-border dispute handling. That combination matters when the enforceability question is more important than the negotiation story.
Pre-Signing Checklist and When to Engage Counsel
Before signature, the deal team should slow down and answer the hard questions. If the answers are not clear, the deal is not ready.
The minimum gate list
First, identify every jurisdiction that touches the transaction. That includes the counterparty’s place of incorporation, the payment corridor, the bank location, and the place where enforcement might be needed.
Second, map the regulatory stack. Tax, AML, licensing, FX, sanctions, and sector-specific rules all need an owner. If no one owns the layer, no one owns the risk.
Third, test the enforcement path. Ask where assets sit, where a judgment can be recognized, and whether arbitration or court litigation gives the better route. Then write that choice into the contract.
Fourth, allocate the residual risk. If the bank freezes the wire, who answers? If withholding applies, who bears the deduction? If the licensee breaches audit obligations, what is the termination trigger?
Board-level question: What changes in the real world if the counterparty breaches on day one after signing?
When specialist counsel is not optional
Specialist counsel should be engaged when more than two jurisdictions are involved, when regulated payment flows are part of the deal, or when the contract covers IP, financing, or long-term distribution rights. Those are the points where template drafting starts to fail.
The same is true when the exit matters more than the launch. If the business needs a clean unwind, a local enforcement path, or multilingual execution support, the transaction should be structured by counsel who handles cross border contracts as a legal system, not a paperwork exercise.
RNC Group structures and reviews cross border transactions with the tax, compliance, payment, and enforcement sequence built into the deal from the start. For Israeli and international clients facing licensing, distribution, financing, or dispute risk, the recommended strategic path is to review the transaction before signature and align the contract with the enforcement route. Visit RNC Group to initiate that review and avoid costly mistakes.
This article provides general information only and does not constitute legal advice. Cross border outcomes depend on the facts, the governing documents, and the jurisdictions involved, so readers should obtain specific legal advice before acting on any transaction or dispute.